Car Loan When Starting a New Job in Alberta — What Lenders Want to See
You accepted a job offer and need a vehicle to get there, but you may not have a pay stub yet. Lenders usually want to see your first pay stub or stubs, and your offer letter helps as a supporting document. Here is how lenders handle a new job, probation and employer checks.
Last reviewed: October 2026
Do banks call your employer for a car loan?
Sometimes. Some lenders confirm your job and pay with your employer, by phone, email or a form. Others go by your pay stubs, with your offer letter as support. Every lender sets its own rules, and we review every application and call you back.
This page is part of our guide to what car lenders verify when you work. It covers the new-job side: first pay stubs, offer letters, probation and employer checks.
Starting a New Job?
Tell us what you have. We review every application and call you back.
5.0121+ Google ReviewsAMVIC LicensedFree Delivery 300km
Who this page is for
- You accepted a job offer, or you started a new job in the last few months.
- You are on probation, changed jobs or industries, or had a gap between jobs.
- Your credit took a hit and you want to know what the lender will check.
Key Facts
- Income proof
- Lenders usually want your first pay stub or stubs; your offer letter supports them
- Probation
- Each lender sets its own rule on time on the job
- What happens next
- We review every application and call you back
- Credit situations
- We work with all credit situations
Bring Your Offer Letter and Your First Pay Stubs
Do Lenders Call Your Employer?
Sometimes. Some lenders confirm your job and pay with your employer, by phone, email or a form. Others go by your pay stubs, with your offer letter as support.
Lenders handle it differently. Some run an employment and income check, and if a lender does not ask for a letter, it may contact your employer directly by phone or email, or send a short form for your employer to fill out. Others go by your pay stubs and ask for a letter from your employer or your offer letter to go with them.
What a lender wants confirmed is usually a short list: your job title, your pay, whether you work full-time, part-time or on contract, and when you started.
If a lender may check, tell your HR contact or your manager to expect it, and give us a name and a number that works.
For the bigger picture of what lenders ask for, see pay stubs, overtime and what lenders check on your job.
Can You Get a Car Loan Before Starting a New Job?
You can apply, but lenders usually want your first pay stub or stubs before they finish the file, and an offer letter does not take their place. We review every application and call you back, and every lender decides each file.
Lenders commonly list a recent pay stub among the proof they ask for, and a brand-new employee may not have one yet. An offer letter or an employer letter helps as a supporting document while you wait for your first stub.
Your Offer Letter Supports Your Pay Stubs
Lenders usually want to see your first pay stub or stubs. A signed offer letter that shows your position, your start date and your pay (a salary, or an hourly rate with your hours) helps as a supporting document alongside them. It does not take the place of pay stubs. Tell us what you have when you apply.
What an Offer or Employer Letter Should Show
Proof of employment shows your income, your title or position and your work arrangement. A good employer letter also says whether you work full-time, part-time or on contract, and when you started. Letterhead and a signature help. If something is missing, ask your HR department for a revised letter.
Full-Time, Part-Time or Contract
Pay and hours are part of what a lender weighs, so say clearly which one your job is. Part-time or contract income can be part of an application, but the income a lender can count is lower, and that can limit the price range of the vehicle.
Applying Before Your Start Date
You can send in an application once you have a signed offer. Lenders usually want your first pay stub or stubs, so a file may not be finished until after you start. Tell us your start date and your first pay date. We review every application and call you back, and when we do we go over what the lender needs.
Timing matters here. If you need the vehicle to commute to your new job, starting the conversation as soon as you have your offer letter gives us the most lead time to talk through what the lender will want and to match you with the right vehicle.
What If You Are in a Probation Period at Your New Job?
You can apply while you are on probation. Lenders set their own rules on time on the job, and every lender decides each file.
One Canadian auto lender publishes a minimum of three months on the job, with exceptions when you take a new job in the same or a similar field after at least a year at your last one. Some lenders also ask your employer about probation. Teaching contracts and public sector jobs spell out probation too: see teachers and educational assistants and public sector employees.
Probation and Alberta's Employment Standards
Your offer letter or contract sets the length of any probation, so check it. Alberta's Employment Standards use a different line: notice to end a job is not required if employment is 90 days or less. That is a rule about ending a job, not a lender rule.
Same Field or a New One
One published lender exception is for a new job in the same or a similar field after at least a year at the last job. Other lenders have their own rules. When you apply, tell us how long you held your last job and what field it was in.
If a Lender Is Cautious
If a lender is cautious about a new job, the usual ways to close the gap are a bigger down payment, a smaller loan or a co-applicant. None of these is a promise, and every lender decides each file.
After Probation
Once you have a few months of pay stubs and on-time payments behind you, you may have more options, including refinancing. A longer pay history gives a lender more to look at.
Read do cosigners help with a bad credit car loan and how down payments work before you decide. If you later want to revisit your terms, see car loan refinancing in Alberta.
What Documents Go With Your First Pay Stubs?
Lenders list a pay stub, an employer letter, a T4 or other tax document and bank statements. A new employee usually has the offer letter first, but lenders usually want the first pay stubs, so the offer letter is the supporting document.
The goal is to give the lender more than one view of your income. Pairing your first pay stubs with your offer letter, your employment contract and recent bank statements fills out the picture, and if you have a first pay stub by the time the lender asks, send it.
The Offer Letter: Your Supporting Document
Your first pay stubs are what lenders usually want to see. Your offer letter backs them up. Before you apply, check that your letter shows your name, the employer's name and contact details, your job title, your start date and your pay. If anything is missing, ask your HR department for a revised letter or a short employment confirmation.
Employment Contract
If your employer also issued a formal contract, include it. Contracts often spell out bonuses, commissions, benefits and probation terms, which gives a lender a fuller picture of your pay.
Bank Statements From Your Last Job
If there is a gap between your last job and this one, or you want to show your pay landing in your account, recent bank statements with your last job's payroll deposits help. Have pay stubs or bank statements ready in case your lender asks.
Once you have your first pay stubs, send them if the lender asks. If you applied during probation and want to look at your terms again after a few months of pay history, call us.
How Does Changing Jobs Affect Your Credit Application?
Lenders look at whether your income continues: does the new job pay as well as the old one, and was there a gap between them? Industry changes, relocations and raises all come up, and each lender decides each file. Moving to a flat-rate or commission pay plan? See which papers show pay that moves.
Gaps Between Jobs
A short gap between jobs is common. Have the end date of your last job and the start date of the new one ready. Recent bank statements that show your last paycheques can help fill in the story. A longer gap needs more explanation, so tell us what happened.
Record of Employment (ROE)
When your pay stops at a job, your employer issues a Record of Employment. The government describes it as information on your employment history, and it carries your last day paid and the reason it was issued. The lender checklists we read do not list one among the proof they ask for, so you may never need it. If a lender asks about a gap, your ROE is the paper that shows when your last job ended. You can view or print yours in My Service Canada Account.
Changing Industries
Moving from one industry to another is common. Some lender rules ask whether the new job is in the same or a similar field, so tell us your old field and your new one. A move to lower pay, or to pay that is mostly commission, may need more documents.
A Raise With the New Job
If the new job pays more, make sure your offer letter clearly shows the new figure, so the lender works from it and not from your old pay.
Relocating for Work
If you moved for the job, have your new Alberta address and your offer letter ready. A recent bill or statement sent to your address is a common proof of residence. If you are on a temporary address, tell us.
New Job Car Loan FAQs
How soon after accepting an offer can I apply for a car loan?
You can send in an application once you have a signed offer letter, but lenders usually want to see your first pay stub or stubs before they finish a file. Your offer letter helps as a supporting document: it shows your position, start date and pay alongside your stubs. Tell us your start date and your first pay date when you apply. We review every application and call you back.
Do I need pay stubs to get a car loan on a new job?
Lenders usually want to see your first pay stub or stubs, and an offer letter does not take their place. The offer letter helps as a supporting document, because it shows your position, start date and pay. Lenders commonly ask for a recent pay stub, a letter from your employer, a T4 or bank statements, and each lender sets its own list. Our guide to what car lenders verify when you work has the details.
Does a probation period mean higher interest rates?
Not that we can point to in any published lender rule. Rates are set by market conditions, your credit score and the lender, and your credit tier mostly sets the rate. Some lenders do set a minimum time on the job, though. Every lender decides each file.
What if my new job is contract or temporary?
Contract and temporary work can be harder to finance than a permanent job, but lenders still look at the whole file. The length of the contract, a history of back-to-back contracts in the same field and your income all come into it. For recurring contract work, like much oilfield and construction work, some lenders look at your contract history as a sign of steady earning. Every lender decides each file.
Can I use my previous job's income if I haven't started the new one?
If you recently changed jobs, your previous income can support the file, especially if your new offer letter, together with your first pay stubs, shows the same pay or more. If there is a gap between the two jobs, bank statements with your previous pay deposits can help fill it. Lenders want to see that your income continues, and each lender decides how it counts what you show.
What if my offer letter doesn't show salary, only an hourly rate?
An hourly rate can be used. Lenders usually multiply your hourly rate by your regular weekly hours to estimate monthly income. For example, $25 an hour at 40 hours a week works out to about $4,333 a month before tax. If your hours vary, a lender may use a more cautious figure, so include anything that shows your usual hours.
Do lenders call my new employer to verify?
Some do. Some lenders confirm your job and pay with your employer by phone, email or a form, and others go by your pay stubs, with your offer letter as support. Tell your HR contact or manager to expect a call, and give us a name and a number that works. Every lender decides what it needs.
Do car lenders ask for a Record of Employment (ROE)?
The lender checklists we read do not list an ROE among the proof they ask for. An ROE is the record your old employer issues when your pay stops, and it shows your last day paid and the reason it was issued. If a lender asks about a gap between jobs, it is the paper to have. You can view or print yours in My Service Canada Account.
Cars in stock you could finance
See all inventory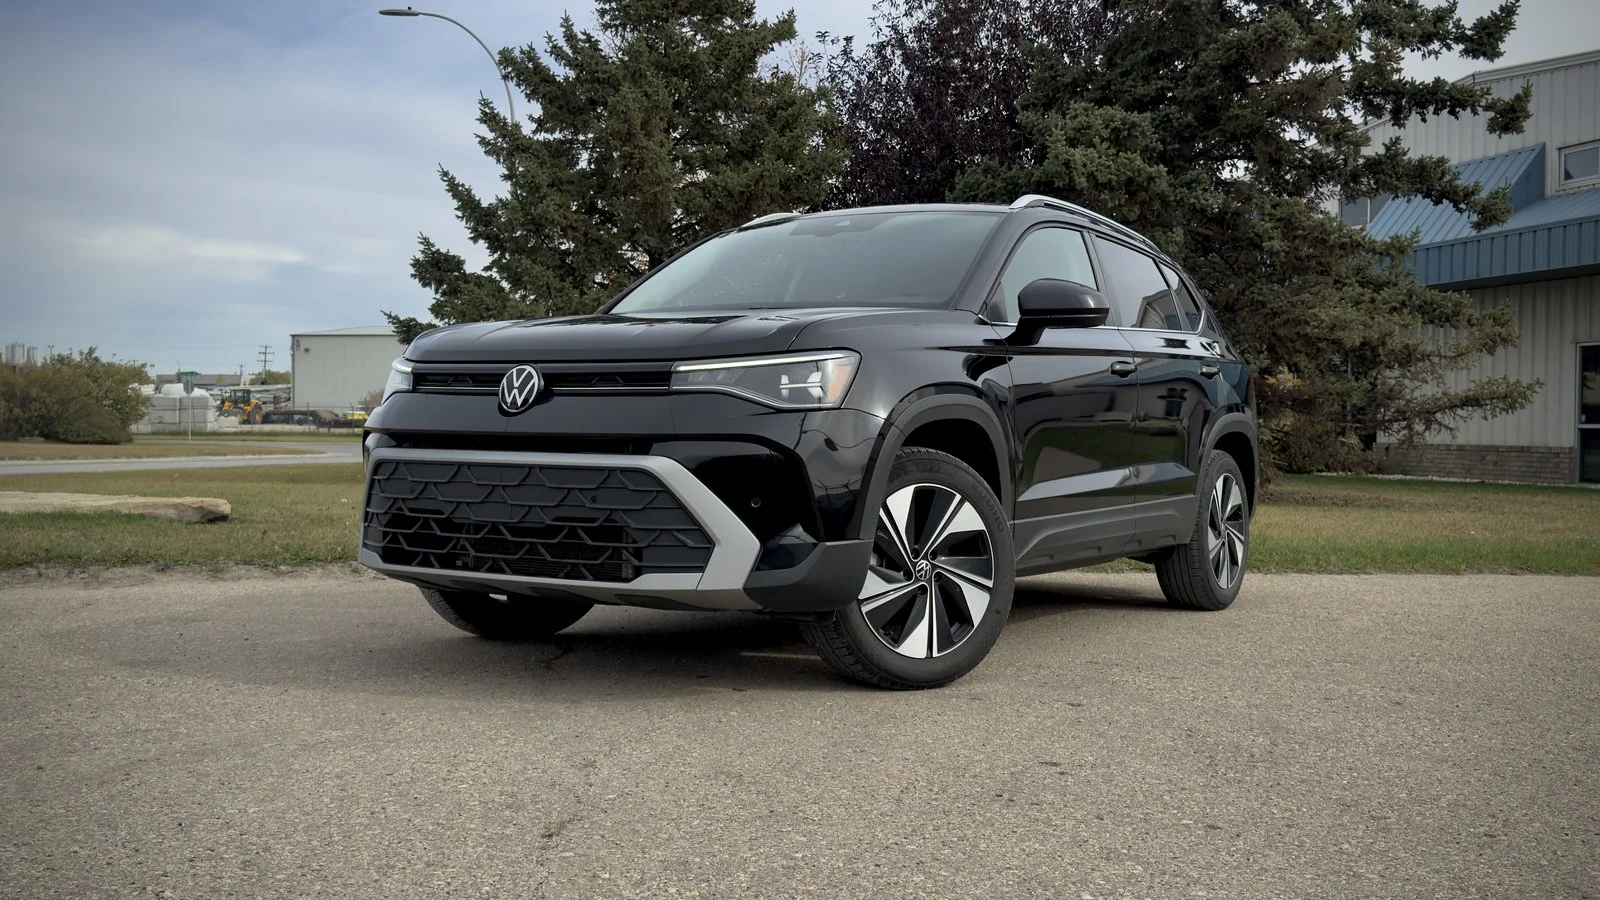
2025 Volkswagen Taos Comfortline
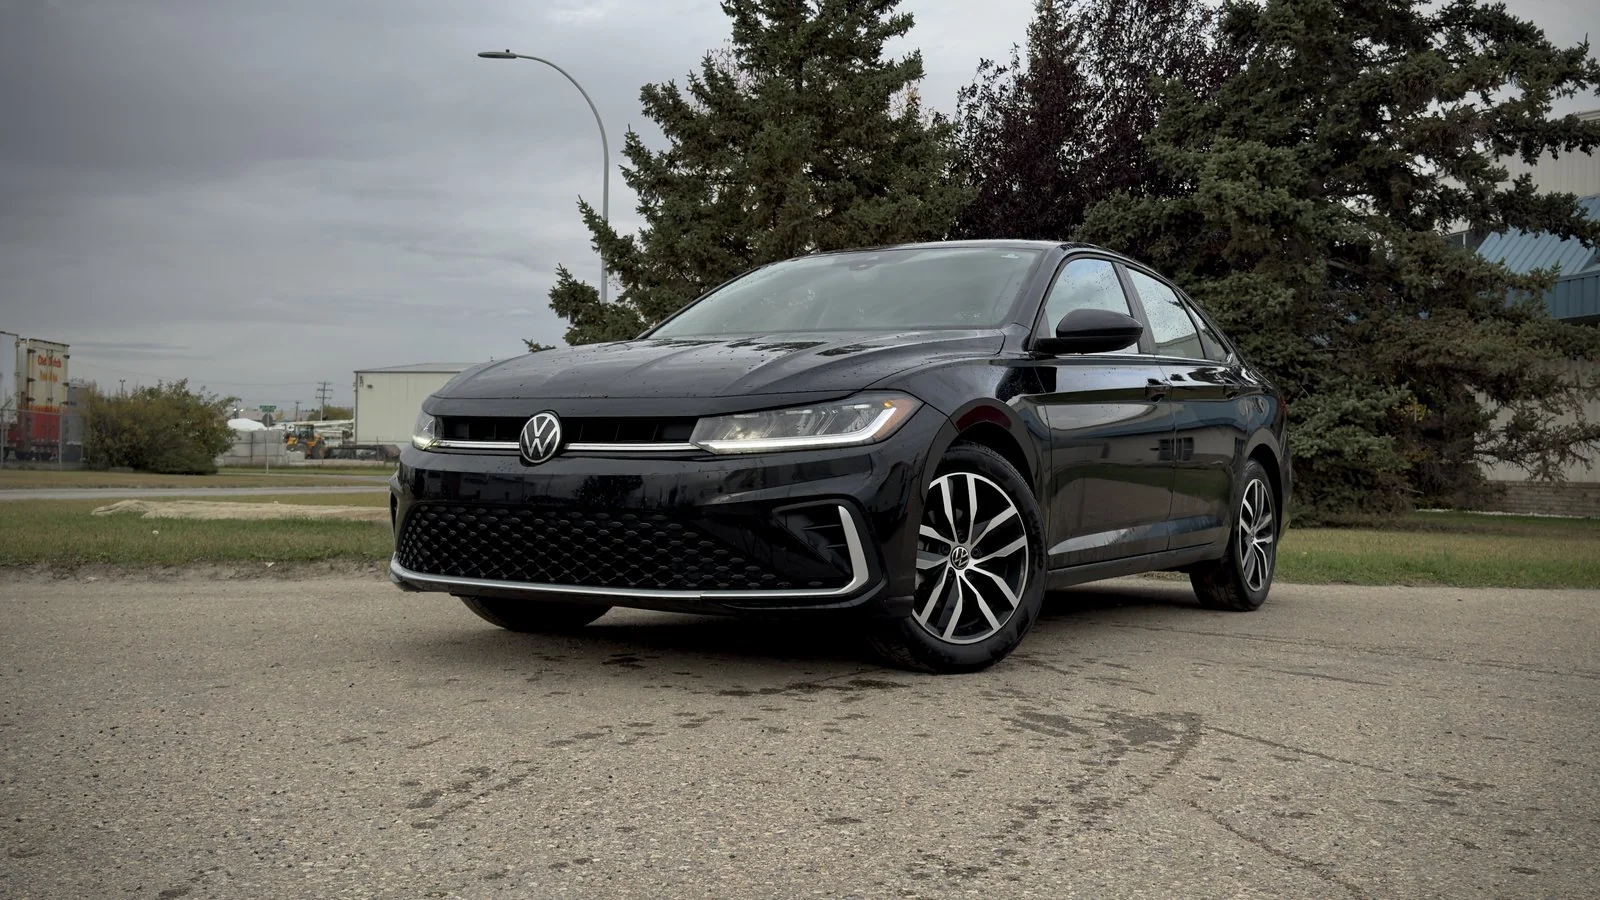
2026 Volkswagen Jetta Comfortline
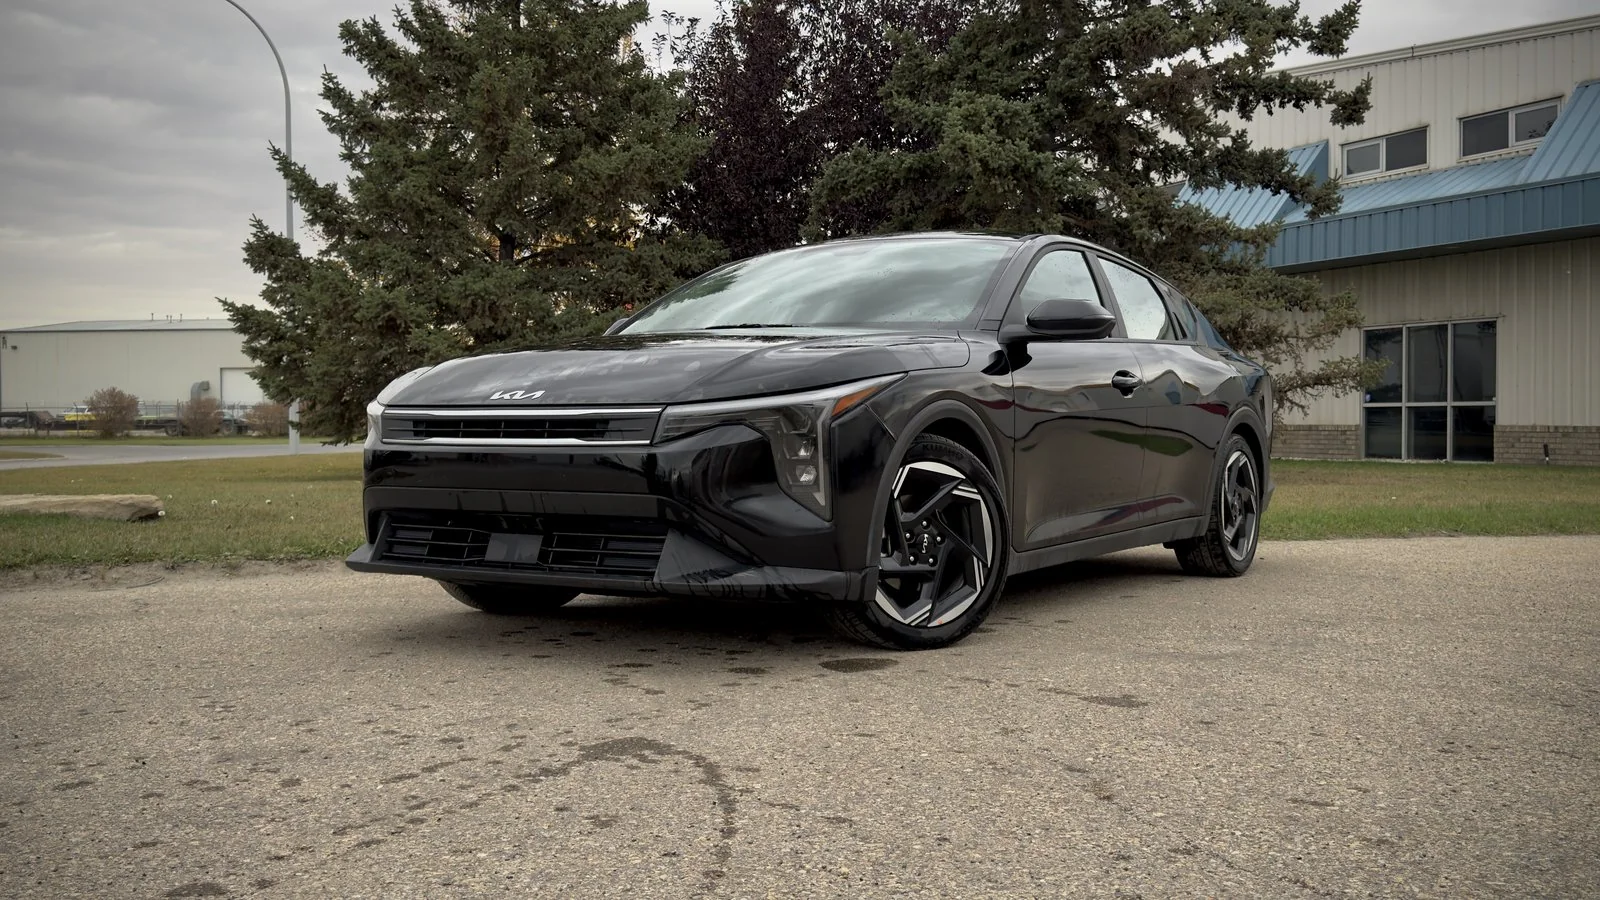
2025 Kia K4 EX
Not seeing it? We'll find it.
We source through our dealer partner network across Western Canada: 25,000+ vehicles to choose from. Tell us what you want and what works for your budget.
Find my car3 min · no credit impactOAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Once you know your pay, see car loan rates in Alberta to estimate the payment.
What Our Customers Say
“A huge thank you to Wes and Luke for making my vehicle purchase such a great experience. This has been the best experience I've had at a dealership. They were patient, kind, and attentive.”
“Thanks to Luke and his team. They were able to find me my dream car and have it delivered between cities. Easy to deal with and easy to work with.”
“Had an amazing experience at this dealership from start to finish. Huge thanks to Luke for being professional, knowledgeable, and genuinely making the whole process stress-free.”
Starting a New Job?
Tell us what you have. We review every application and call you back.
5.0121+ Google ReviewsAMVIC LicensedFree Delivery 300km
Other Financing Options
Ready to Apply?
Apply online, and have your first pay stub and your offer letter ready. We review every application and call you back, and every lender decides each file.
Not sure your offer letter has everything a lender needs? Call us and we will go over it with you before you submit your application.