Disability Car Financing in Alberta
AISH, ADAP, CPP Disability and other disability benefits are real, documented income and can count toward a car loan. Here is what lenders usually look at, and when to call us before you apply.
Last reviewed: October 2026
What lenders typically need
Disability income — AISH, ADAP, CPP Disability, WCB or a private plan — is steady and easy to document, and lenders do look at it. They also add up anything else you can prove.
In our experience, lenders typically look for about $2,800 a month in income you can prove, from all sources combined. Benefits like AISH, ADAP, CPP Disability, EI and the Canada Child Benefit can count toward that alongside work or support income. Every lender decides each file. If you're under that, talk to us first — a co-applicant, a larger down payment or a few months of income history can change the picture.
Can someone on disability get a car loan in Alberta?
Often, yes. AISH, ADAP, CPP Disability and other disability income can count as income when you can document it. Lenders add up every source and compare the total with the payment. In our experience, about $2,800 a month in total income is where files tend to work. Every lender decides each file.
Where to go from here
Key Facts
- AISH (2026)
- Up to $1,940/mo from July 2, 2026
- ADAP core benefit
- $1,740/mo
- CPP Disability (2026)
- Up to $1,741.20/mo
- Typical target
- About $2,800/mo total income
- Lender network
- 21+ lenders
Disability Income Is Steady — and It Is One Part of Your File
Can Disability Benefits Count as Income for a Car Loan?
Often, yes. AISH, ADAP and CPP Disability are government-issued, arrive on a fixed schedule and do not depend on an employer, which makes them easy for a lender to verify.
Lenders evaluate income based on three criteria: consistency, predictability, and verifiability. Government disability benefits score well on all three.
AISH: Alberta's Provincial Disability Benefit
AISH pays up to $1,940 a month as of July 2, 2026. Since then, most people who were on AISH have moved to ADAP, whose core benefit is $1,740 a month. Either way the income is government-issued and does not rise and fall with hours worked. Provide your most recent benefit letter or bank statements showing the deposits.
CPP Disability: Federal Monthly Benefits
CPP Disability pays up to $1,741.20 a month in 2026. The average new beneficiary receives less, so your own letter is the number lenders use. It is deposited on a fixed schedule and can be documented with a benefit letter or bank statements. If you receive CPP Disability plus a provincial benefit, lenders can add them together.
Steady Income: What Lenders Look At
Lenders look for income that arrives on schedule in a known amount, and AISH and CPP Disability do arrive every month. What decides most files is the total: lenders weigh all the income you can prove, together, against the payment and your other debts. Every lender decides each file.
Other Qualifying Disability Income Sources
Beyond AISH and CPP-D, several other income sources may qualify you for financing. Workers' Compensation Board (WCB) long-term disability payments, private long-term disability insurance benefits, and Veterans Affairs disability pensions are all recognized by various lenders in our network. If you receive disability income from any source, it is worth discussing — we can identify which lenders will accept it.
Combining Multiple Income Sources
Many Albertans on disability receive income from more than one program. AISH plus the Alberta Adult Health Benefit, CPP-D plus a private insurance top-up, or disability income combined with part-time employment — all of these combinations strengthen your total income picture. Lenders look at total monthly income from all verifiable sources, so every stream counts toward your qualifying amount.
Vehicle Features That Matter for Mobility and Accessibility
Transportation independence changes quality of life. The right vehicle is not just about getting from A to B — it is about maintaining the freedom to manage medical appointments, daily errands, and social connections on your own schedule.
Entry and Exit Height
Vehicle step-in height varies significantly between sedans, crossovers, SUVs, and trucks. If mobility is a factor, a crossover or mid-height SUV (like a Toyota RAV4, Hyundai Tucson, or Chevrolet Equinox) often provides the best balance — not so low that you have to drop into the seat, and not so high that climbing in is difficult. We can help you identify vehicles in our inventory that match your physical needs.
Cargo Space for Mobility Equipment
If you use a wheelchair, walker, mobility scooter, or other equipment, cargo dimensions matter more than total volume. A vehicle with a wide, low-loading cargo area makes stowing equipment practical without assistance. Minivans and certain SUVs with flat-folding rear seats offer the most flexible configurations for mobility equipment storage.
Adaptive Equipment Compatibility
Hand controls, left-foot accelerators, steering knobs, and other adaptive driving equipment can be installed in most modern vehicles, but some are better suited than others. Vehicles with electronic throttle control and power steering are generally the most compatible with aftermarket adaptive modifications. If you plan to install adaptive equipment, let us know before you choose a vehicle so we can steer you toward compatible options.
Financing Modified Vehicles
Vehicles with existing adaptive modifications can be financed through our lender network. The vehicle appraisal accounts for factory features and aftermarket modifications. If you need a vehicle modified after purchase, some lenders allow the modification cost to be included in the loan amount under certain conditions. We can walk you through what is possible based on your specific modification needs.
Reliability When You Depend on Your Vehicle
When your vehicle is essential for medical appointments, therapy sessions, and daily independence, reliability is not a luxury — it is a necessity. A breakdown is not just an inconvenience; it can disrupt treatment schedules and access to essential services. We prioritize well-maintained, reliable vehicles and every unit passes an AMVIC-compliant inspection before delivery. Toyota, Honda, and Hyundai consistently rank highest for long-term dependability.
Alberta Disability Benefits That Help You Qualify
Alberta has several disability-related income programs. Here is how each one is treated by lenders and what documentation you need to present a strong application.
AISH (Assured Income for the Severely Handicapped)
AISH recipients may also receive other benefits, such as health or child supplements. Lenders mainly look at the base monthly payment because it is the most consistent amount. Bring your benefit statement or three consecutive months of bank statements showing the deposits.
CPP Disability Benefits
CPP Disability is available to people who have contributed to CPP and meet the medical criteria. If you have dependent children, a CPP children's benefit may also be paid. Bring your CPP Disability benefit statement.
Workers' Compensation Board (WCB) Benefits
WCB long-term payments can count as income when you can document the amount and how long they will continue. Provide your WCB benefit letter or payment history.
Private Long-Term Disability Insurance
If you receive disability benefits through an employer's group insurance plan or a private policy, these payments are treated as income by lenders. The key factor is the expected duration — lenders want to see that the benefit will continue for the term of the loan or that it is permanent. Provide your benefit letter from the insurance company showing the monthly amount, payment schedule, and expected end date (if applicable).
Disability Tax Credit (DTC) and Related Supports
While the Disability Tax Credit itself is not income, it reduces your tax burden and may free up cash flow that strengthens your overall financial picture. The Registered Disability Savings Plan (RDSP) and related grants are not counted as income by lenders, but they demonstrate financial planning and stability. Being DTC-eligible also unlocks access to other provincial programs and may qualify you for vehicle modification grants through Alberta Health Services.
How the Financing Process Works for Disability Income
The process is identical to any other financing application — your income source does not slow anything down or require special handling. Apply in 3 minutes, receive a decision within 24 to 48 hours, choose your vehicle, and take delivery province-wide.
The process is straightforward and designed to be accessible. Whether you apply online, by phone, or in person, the steps are the same and your income source does not complicate anything. You can also explore all bad credit financing options on our main bad credit car loans page.
Apply Online, by Phone, or In Person (3 Minutes)
Fill out our secure online application — it takes about 3 minutes. You will provide basic personal information, your disability income details, and your vehicle preferences. There is no credit check at this stage. If you prefer, call us and we can complete the application together over the phone.
We Match You With the Right Lender
Your application goes to our network of 21+ lenders. We look for lenders that read disability income well and work with all credit situations. One application, several lender options, and no need to shop around.
Review Your Options and Choose Your Vehicle
We review every application and call you back. If a lender comes back with terms, we go through the interest rate, payment and loan term with you, then help you find a vehicle that fits your budget and your mobility needs.
Sign and Drive — Delivery Available Province-Wide
Complete the paperwork and take possession of your vehicle. We offer free delivery within 300km and delivery options across Alberta. If you cannot travel to our location, we bring the vehicle to you — including to accessible residences, care facilities, or any address that works for your situation.
What Documentation Do You Need?
You need four things: your disability benefit statement or three months of bank statements showing deposits, government-issued ID, proof of your Alberta address, and optionally two or three personal references. It is a short list — gather it before you apply and things move faster.
Having your documents ready saves time. Here is what lenders usually ask for.
Income Verification
Your most recent AISH benefit statement, CPP-D benefit letter, WCB payment summary, or private disability insurance letter. Alternatively, three consecutive months of bank statements showing the regular deposits work just as well. If you receive income from multiple sources, bring documentation for each one.
Identification
A valid Alberta driver's licence or government-issued photo ID. If you have a condition-restricted licence (for example, adaptive equipment required), that is not a barrier to financing — it simply helps us match you with the right vehicle.
Proof of Address
A recent utility bill, bank statement, or government correspondence showing your current Alberta address. If you live in a supported living arrangement, a letter from your facility confirming your residency is accepted.
References (If Required)
Some lenders request two or three personal references — names and phone numbers of people who can confirm your identity and character. These are not co-signers and are not financially responsible for anything. Having these ready avoids a delay after your application is submitted.
What Our Customers Say
“When I started canvassing for a vehicle Luke reached out and was very helpful with finding cars and financing options. Luke and Shadeen helped with financing a private sale quickly.”
“Luke was fantastic with helping us get into a mini van, we are MORE than happy. I highly recommend anyone looking for a vehicle to go check out Shift Happens!”
“The buying experience was handled very professionally. Wes was very attentive and presented everything in an open and honest manner that gave me the reassurance that I made a good purchase.”
Cars you could drive home
See all inventory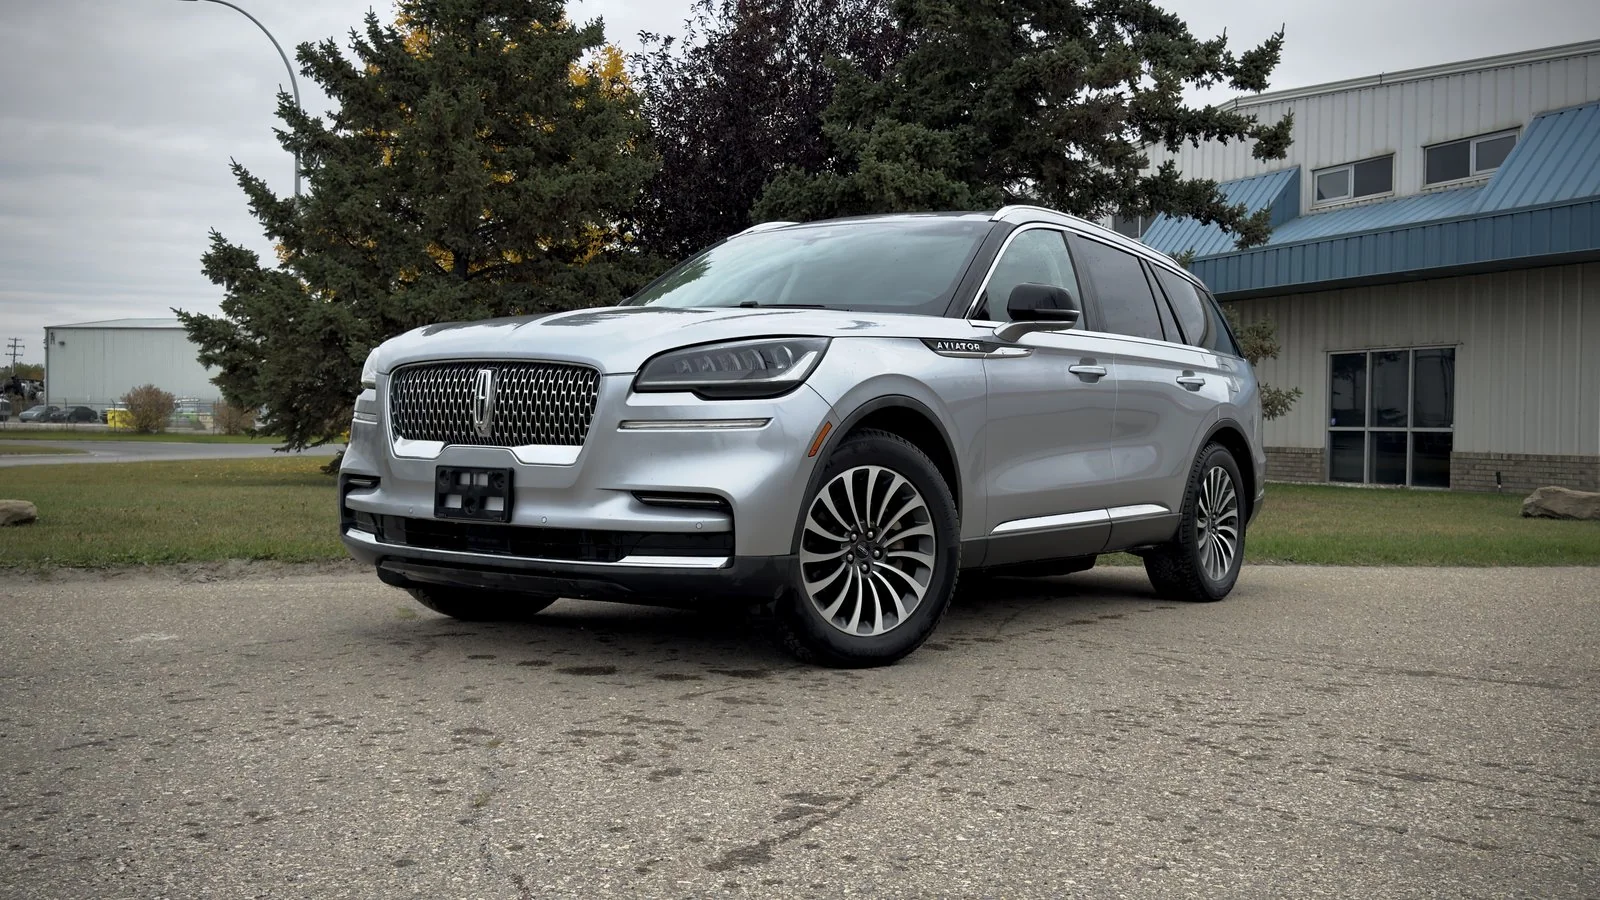
2022 Lincoln Aviator Reserve
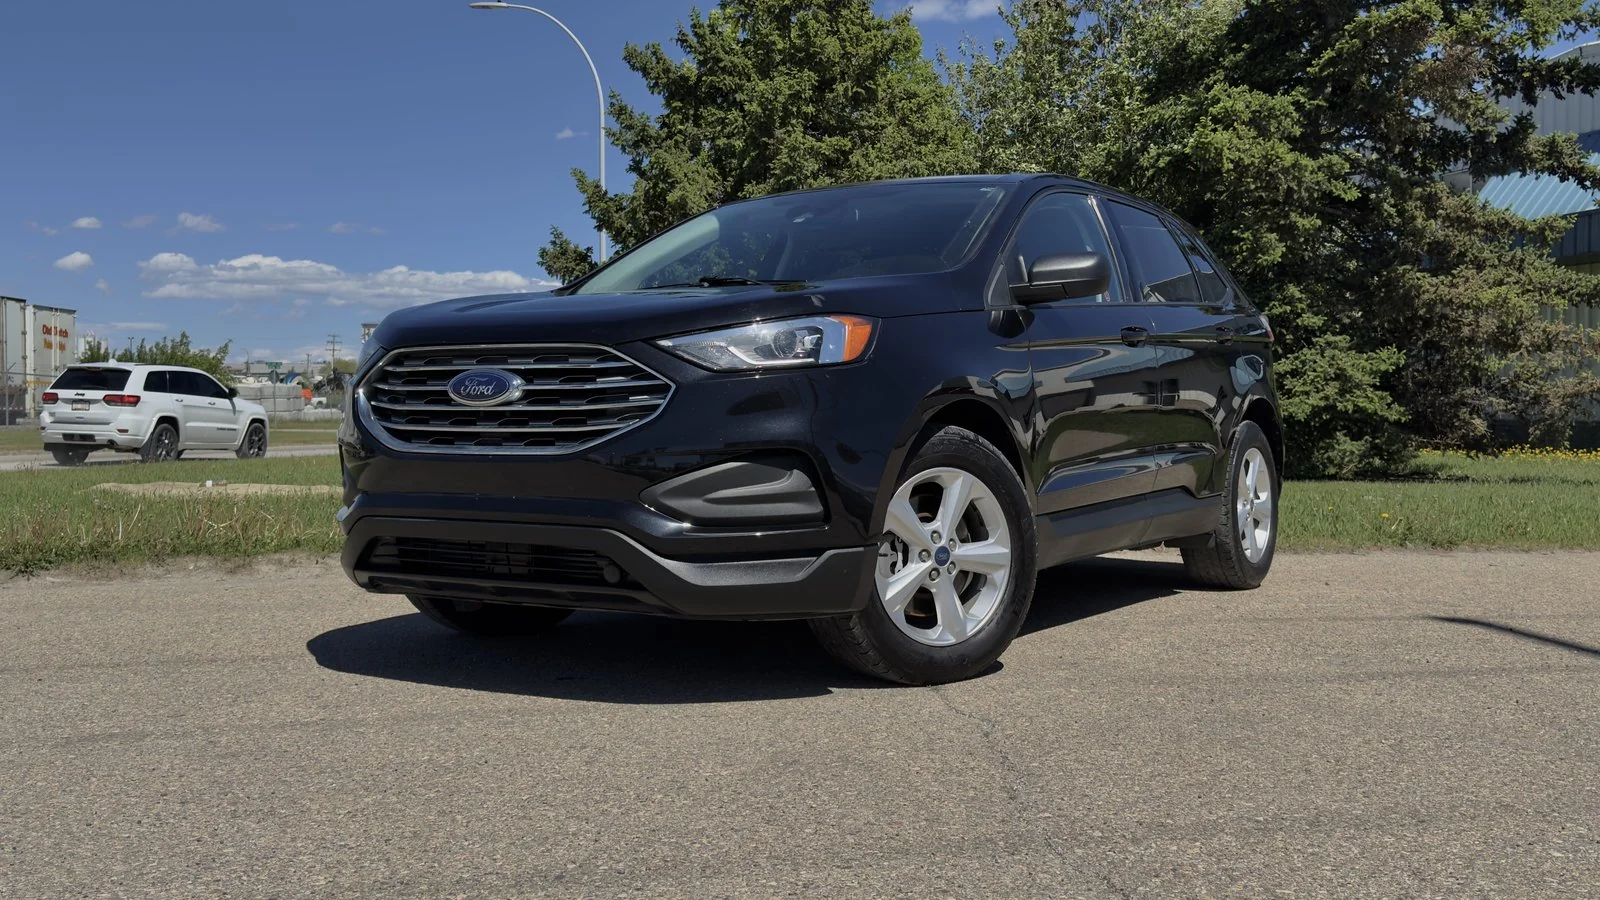
2020 Ford Edge SE
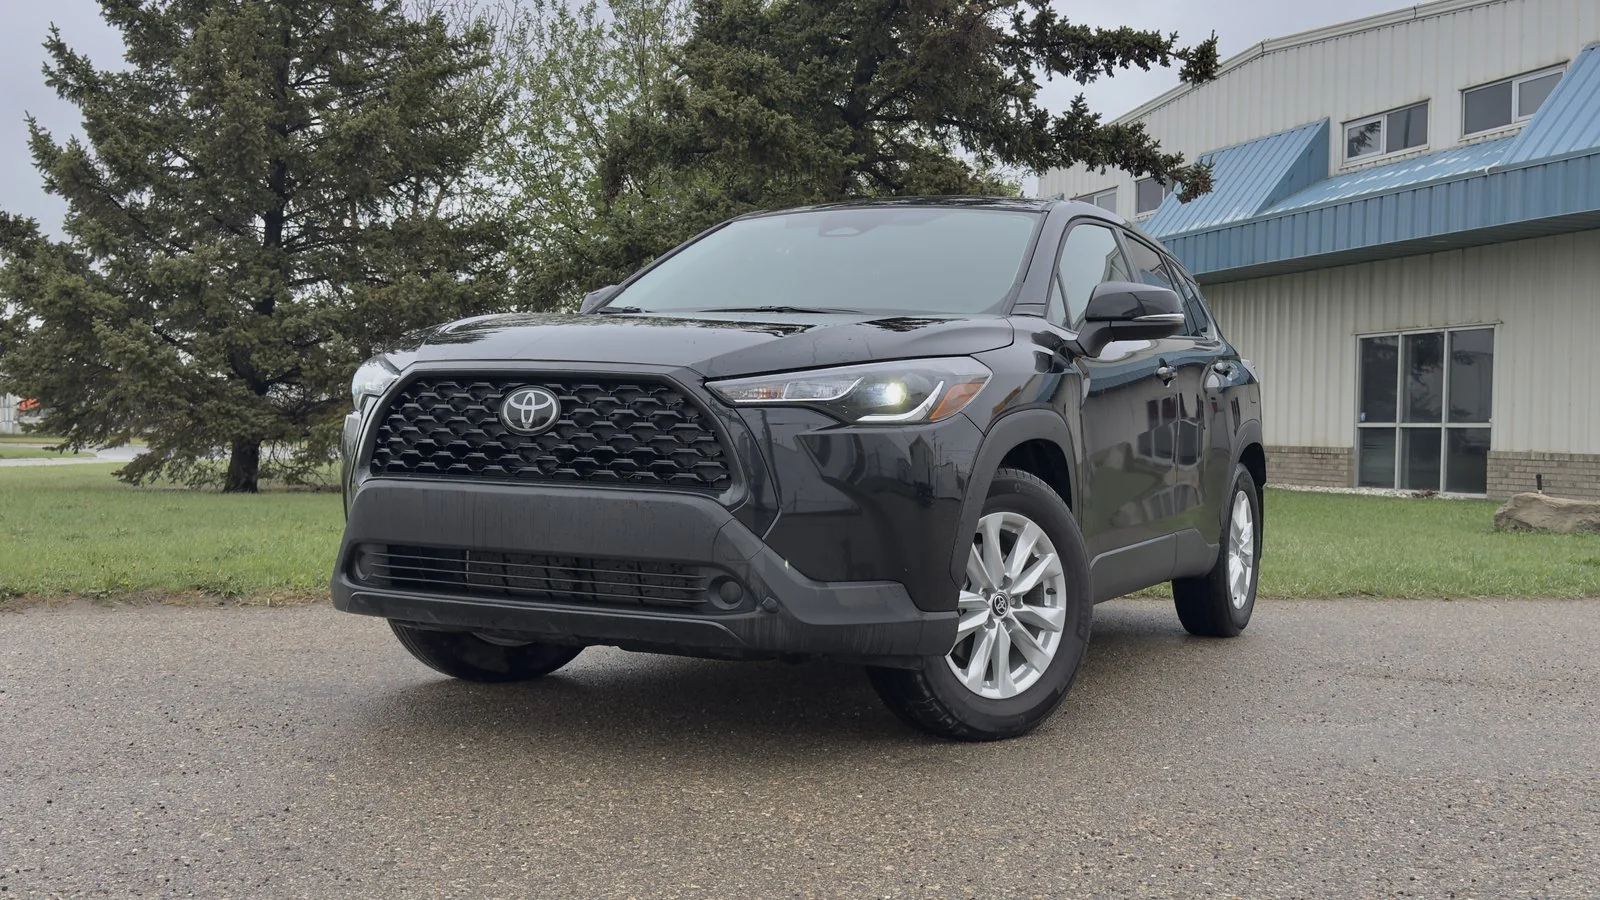
2024 Toyota Corolla Cross LE
2020 Mercedes-Benz GLA250 4Matic
Not seeing it? We'll find it.
We source through our dealer partner network across Western Canada: 25,000+ vehicles to choose from. Tell us what you want and what works for your budget.
Find my car3 min · no credit impactOAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Where to go from here
Disability Car Financing FAQs
What types of disability income can count when I apply for car financing?
AISH, ADAP, CPP Disability, WCB long-term payments, private long-term disability and Veterans Affairs benefits can all count when you can document them. Lenders add every source together. In our experience, about $2,800 a month is where files tend to work, and every lender decides each file.
How much do AISH, ADAP and CPP Disability pay in 2026?
As of July 2, 2026, AISH pays up to $1,940 a month and ADAP's core benefit is $1,740. CPP Disability pays up to $1,741.20 a month in 2026, though the average new beneficiary receives less. Your own letter shows your real amount, and that is the number lenders use.
How do lenders see disability income compared with a paycheque?
Steady benefits are easy to verify, and that helps. Lenders also look at how long the income will continue, what else you earn, your debts and your credit history. A letter from the payer plus three months of bank statements is the usual proof. We review every application and call you back.
What if my total income is under what you usually see work?
Talk to us before you apply. A co-applicant with steady income, a larger down payment or a few months of income history can change the picture. Waiting can help too. We would rather give you a straight answer by phone than have you apply and collect a credit inquiry for nothing.
Can the cost of hand controls or a wheelchair ramp go into the loan?
Sometimes, depending on the lender and how the cost compares with the vehicle's value. Ask us before you apply so we can plan for it. We can also look for vehicles that already have the features you need. Rules differ by lender and by the type of modification.
Do the Disability Tax Credit or an RDSP count as income?
The Disability Tax Credit is not income, and an RDSP balance is not income. Regular RDSP withdrawals you can document may be counted by some lenders. Mention both when you apply and we will explain how each lender treats them.
What if my disability income is temporary, like a short-term WCB claim?
Lenders want to see the income continue through the loan, or a plan if it ends sooner. A short-term claim with an end date is a harder file. Bring the end date and any return-to-work plan. A co-applicant or a larger down payment can help.
Sources (checked October 2026): Government of Alberta — AISH and ADAP financial benefits summary, Government of Alberta — Alberta Disability Assistance Program, Government of Canada — CPP disability benefit amount. Benefit amounts change; your own letter shows your real amount.
Related Resources
Related Buyer Guides
Explore how disability benefits, CPP-D, and AISH are evaluated for car loan approval — and the specific documents lenders require.
- How Non-Traditional Income Qualifies for Car Loans in Alberta
- Car Buying on a Fixed Income: Retirement Financing in Alberta
- How to Get a Car Loan with Only a Part-Time Job in Canada
- Multi-Generational Households: Combining Incomes to Qualify Together
- Military Members and Reservists: Car Financing Around Postings
- 5 Documents That Delay Every Alberta Car Loan
Other Financing Options
Ready to Get Started?
Check your options online, or call us if you are under about $2,800 a month or not sure. We will be straight with you about what could work.
AMVIC licensed. No obligation. No judgment. Just practical help getting you into a reliable vehicle.