Single Parent Car Financing in Alberta
Your family needs a reliable vehicle, and one income can still work. Child benefits and support payments can count alongside your pay. Here is what lenders usually look at, and when to call us first.
Last reviewed: October 2026
What lenders typically need
Most single parents who finance a car are working, and lenders start there. Child benefits and child support can count too, and lenders add up everything you can prove.
In our experience, lenders typically look for about $2,800 a month in income you can prove, from all sources combined. Benefits like AISH, ADAP, CPP Disability, EI and the Canada Child Benefit can count toward that alongside work or support income. Every lender decides each file. If you're under that, talk to us first — a co-applicant, a larger down payment or a few months of income history can change the picture.
Can a single parent get a car loan in Alberta?
Often, yes. Lenders add up everything you can prove, including work income, child benefits and support. In our experience, about $2,800 a month in total income is where files tend to work. A larger down payment or a co-applicant can help if you are under that. Every lender decides each file.
Where to go from here
Key Facts
- Child benefits
- Can count toward your total income
- Typical target
- About $2,800/mo total income
- Lender network
- 21+ lenders
- Down payment
- A larger one can help if income is lower
- Credit
- We work with all credit situations
The Canada Child Benefit Can Count Toward Your Income
How Does Single-Income Financing Work?
It works the same as dual-income financing — lenders look at your total monthly income from all sources and compare it to your monthly debt payments. For single parents, that means employment income plus Canada Child Benefit, support payments, and provincial benefits can all count toward your total, if you can document them.
Being a single parent changes what your financial picture looks like — but it does not close the door on vehicle financing. Here is what lenders actually look at, and why your situation is stronger than you might think.
One Income Does Not Mean One Option
Lenders assess affordability based on your total financial picture, not your household size. Being a single parent is a situation, not a disqualification. What matters is whether your total income supports the payment. Counting all your documented income often gives lenders a clearer picture.
Canada Child Benefit (CCB) Counts as Income
The CCB is government-issued, consistent, and directly tied to your family situation. Most subprime lenders recognize it as stable recurring income because it is — it does not depend on an employer or market conditions. Bring your most recent CCB notice or three months of bank statements showing the monthly deposits.
Alberta Child and Family Benefit Also Counts
This provincial benefit supplements federal CCB and strengthens your application further. It is additional government-backed income. Some lenders can count it as extra income when it is documented. It is smaller than the CCB, but it adds to the picture.
Spousal Support and Child Support Are Recognized Income
If you receive court-ordered support, most lenders treat it as stable income when it is documented. What you need is your separation agreement, divorce order, or written agreement showing the payment schedule and amounts. The longer the history of consistent payments, the stronger the case.
How Lenders Calculate Your Affordability
The math is straightforward: total monthly income from all sources (employment plus benefits plus support) minus your existing monthly debt payments. The vehicle payment should ideally stay near 15% of your gross monthly income (a rule of thumb, not a lender rule). We walk through this calculation with every client before submitting an application — so you know the number before a lender does.
How Do You Choose a Safe, Reliable Vehicle on a Single Income?
Prioritize reliability and safety ratings over features — a vehicle that does not break down is worth more to a single-income household than heated seats. Toyota, Honda, and Hyundai compact SUVs consistently earn top safety ratings and have the lowest long-term repair costs.
When you are the only driver and the only income, the vehicle decision carries more weight. A breakdown is not just an inconvenience — it disrupts school pickups, work, and everything else. These are the factors worth prioritizing.
IIHS Top Safety Pick Vehicles
The Insurance Institute for Highway Safety rates vehicles based on crash test performance and safety technology. Look for current and recent-year models that earned a Top Safety Pick or Top Safety Pick+ designation. Safety ratings remain with the vehicle regardless of age. Toyota RAV4, Honda CR-V, and Hyundai Tucson are frequently top-rated and available at used-car price points.
LATCH System for Car Seats
Before committing to any vehicle, check all lower anchor points and top tether anchors for your child seats. Older vehicles may have fewer LATCH positions, and some rear seats are better suited to car seats than others. Bring your car seat to any test drive and make sure it installs securely before you buy.
Reliability Over Luxury
A vehicle that runs for years without expensive repairs is worth more than one with heated seats that breaks down. Toyota, Honda, and Hyundai earn their reputations through long-term reliability data, not marketing. Choosing a well-maintained example from one of these brands is one of the best financial decisions you can make on a single income.
Fuel Efficiency on a Single Income
A sedan using 7 to 8 litres per 100 km costs noticeably less in fuel each year than an SUV using 10 to 12. That difference adds up over years of ownership and affects the payment you can carry.
Size That Makes Sense
You need room for kids, strollers, sports equipment, and groceries — but you do not need to pay for space you will never use. A compact SUV often hits the sweet spot between practicality and cost. The Toyota RAV4 and Hyundai Tucson are standout options in this category: enough room for a family, manageable running costs, and strong resale value.
Which Alberta Benefits Help You Qualify?
The Canada Child Benefit is usually the biggest benefit single parents can add — many lenders can count it because it is government-issued and does not depend on employment. The Alberta Child and Family Benefit, GST credit, and court-ordered support payments can all be added on top.
Alberta single parents may have access to several income streams beyond employment. Understanding how each one is treated by lenders helps you put your strongest application forward.
Canada Child Benefit (CCB)
Up to $8,157 a year per child under 6 and $6,883 a year per child aged 6 to 17 (July 2026 to June 2027), reduced as family income rises. Paid monthly to your bank account. Many lenders can count it as income because it is documented and recurring. Bring your CRA notice or three months of bank statements.
Alberta Child and Family Benefit
Extra provincial support on top of the CCB for lower-income families, paid quarterly. Some lenders can count it when it is documented. Check the current amount for your family with the Alberta government.
GST/HST Credit
Quarterly payments based on family size and income. The amounts are smaller than CCB, but they represent additional consistent government income that demonstrates your household is in the system and receiving regular payments. While lenders may not weight it heavily, it contributes to a pattern of stable government income.
Child Support and Spousal Support
Court-ordered or agreement-based support payments are recognized by lenders when properly documented. Provide your separation agreement, divorce order, or written agreement showing the payment schedule and amounts. A consistent history of receiving these payments — visible in your bank statements — strengthens the case that the income is reliable.
Alberta Works and Income Support
If applicable, employment support programs can factor into your overall financial picture. Each lender evaluates these differently — some count them directly as income, others treat them as supporting context. Being transparent about all income sources is always the right approach. We work with lenders across the spectrum to find the best fit for your situation.
How Do You Rebuild After Separation or Divorce?
Start by closing or refinancing joint accounts — joint debts stay on your credit report until they are paid off or transferred, even if your ex was ordered to pay them. Getting a vehicle loan in your own name is one of the fastest ways to build an independent credit profile after separation.
Separation and divorce change your financial life in ways that take time to sort out. If you are navigating this while also trying to get into a reliable vehicle, here is what you need to know.
Joint Debts From a Previous Relationship
Joint debts from a previous relationship still appear on your credit report until they are paid off or formally reassigned. Lenders see them and factor them into your debt-to-income ratio even if your ex is supposed to be paying. If you have joint accounts that are current, that is fine — the problem arises when they are delinquent or when the lender cannot separate your obligation from your ex's. Be upfront about this and we can navigate it together.
Removing an Ex-Partner From a Joint Auto Loan
Removing someone from a joint auto loan typically requires refinancing it in one person's name only. This consolidates ownership and credit responsibility. We can help you explore refinancing options for an existing joint vehicle, whether the goal is to take it over completely or to free yourself from the obligation.
Building Credit Independence
If your credit history was primarily under joint accounts or your partner's name, you may have a thin credit file on your own. A vehicle loan in your name is one of the most effective ways to build your own credit history. Making on-time payments establishes the independent credit profile you will need going forward.
When to Refinance vs When to Replace
If your current vehicle is unreliable or too expensive to maintain, replacing it with something affordable and dependable may be smarter than refinancing a problematic vehicle. The calculus is simple: if the ongoing repair costs exceed what a payment on a reliable replacement would cost, you are better off replacing. We can help you work through the numbers.
Protecting Your Credit During Separation
Make sure joint account payments stay current while separation terms are being finalized. Late payments on joint accounts affect both credit reports regardless of who was supposed to pay — this is one of the most common and damaging surprises people encounter during separation. If you are uncertain whether payments are being made, check your credit report directly.
Single Parent Financing FAQs
Does the Canada Child Benefit count as income for a car loan?
Lenders can count it, along with child support and the Alberta child benefit, when you can document them. The CCB pays up to $8,157 a year per child under 6 and $6,883 a year for ages 6 to 17 (July 2026 to June 2027), depending on family income. Bring your CRA notice or bank statements.
Can I get a car loan as a single parent with bad credit?
Often, if your total income is steady. Lenders add up work, child benefits and support you can document. In our experience, about $2,800 a month is where files tend to work. A bruised score can change the rate or the down payment. Every lender decides each file.
What if my total income is under that amount?
Talk to us before you apply. A co-applicant with steady income, a larger down payment or a few months of income history can change the picture. We would rather give you a straight answer by phone than have you apply and collect a credit inquiry for nothing.
What monthly payment can a single parent realistically afford?
That depends on your rent, childcare and other debts, not just your income. A good check is whether the payment leaves room for fuel, insurance and repairs. Use the payment calculator on this site for an example, or call us and we will go through your numbers with you.
Do I need a co-signer as a single parent?
Not always. A co-applicant with steady income can open more options, especially when your own income is under about $2,800 a month. A co-signer takes on the loan with you, so make sure they understand that. We will tell you honestly whether it would help your file.
Can child support help my application?
Court-ordered or documented child support you receive can count as income. Lenders usually want a maintenance enforcement statement, a court order or three months of bank statements showing it arrive. Support you pay is a debt that lenders subtract. Every lender decides each file.
What are safe, affordable vehicles for a single parent?
Look for a reliable used SUV, minivan or sedan with good safety ratings and service records. A lower-priced vehicle with a smaller payment often serves a family better than a stretch purchase. Tell us how many car seats you need and we will show you what fits your budget.
Sources (checked October 2026): Canada Revenue Agency — How we calculate your CCB. Benefit amounts change; your own letter shows your real amount.
Related Resources
What Our Customers Say
“Luke and Wes are a fantastic team! I purchased a Lincoln Corsair in pristine condition. They got me the best interest rate for my financing and even helped me find the best insurer.”
“Dealt with Luke and Wes. It was one of the best car buying experiences I have ever encountered. I went back to buy another vehicle from these guys as they are just so easy to deal with.”
“Excellent service, very happy with my ride, thank you Luke and Wes!”
Cars you could drive home
See all inventory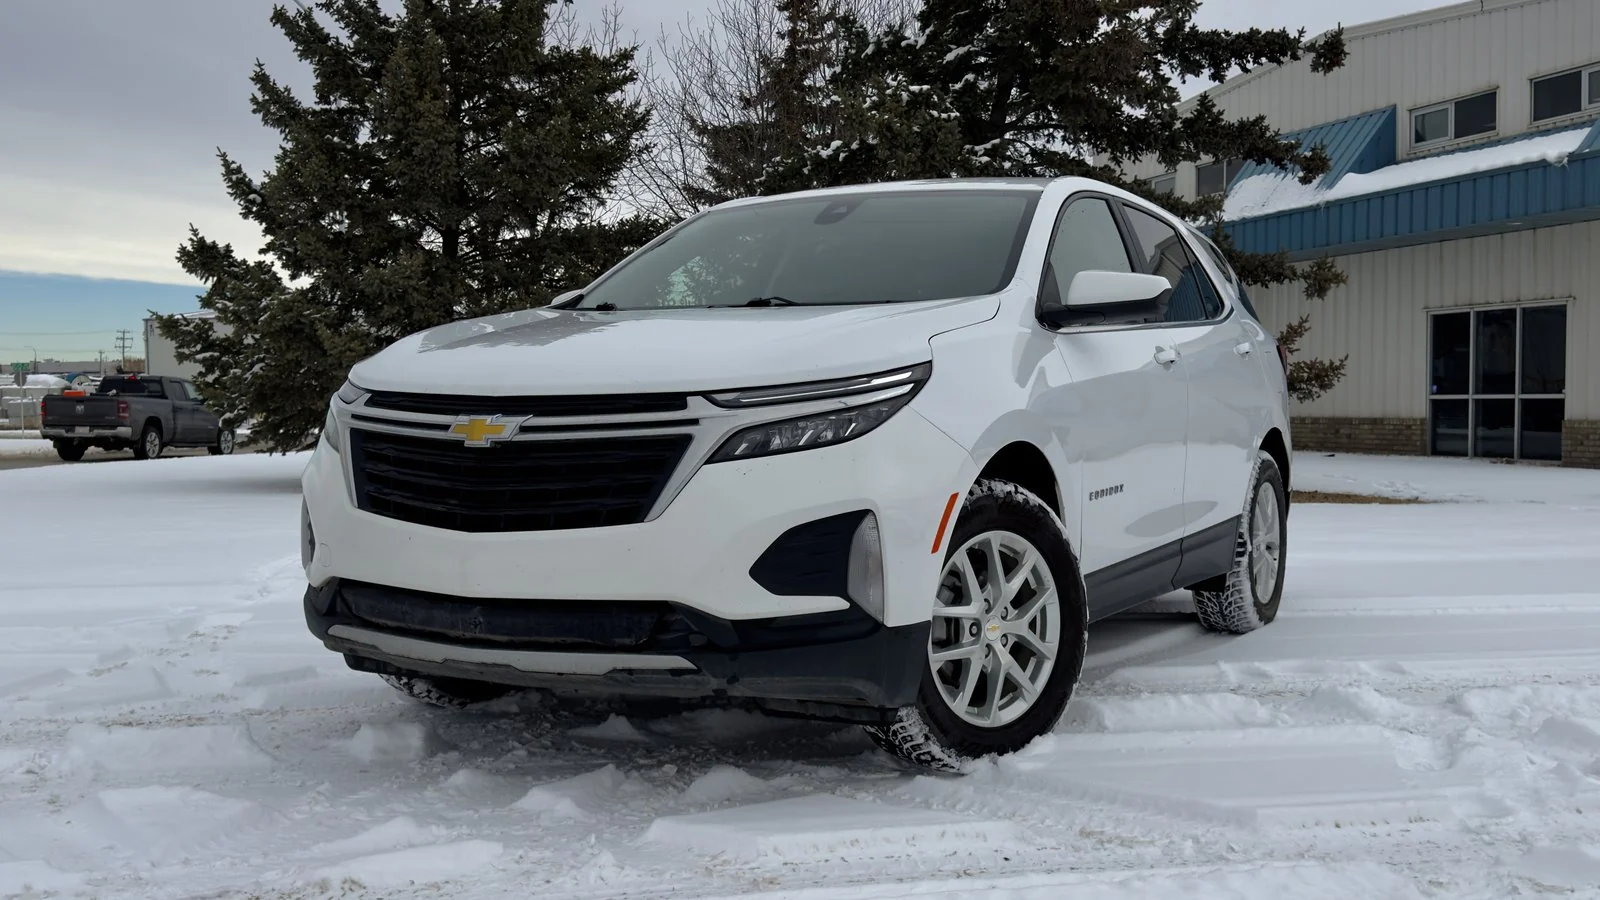
2022 Chevrolet Equinox LT
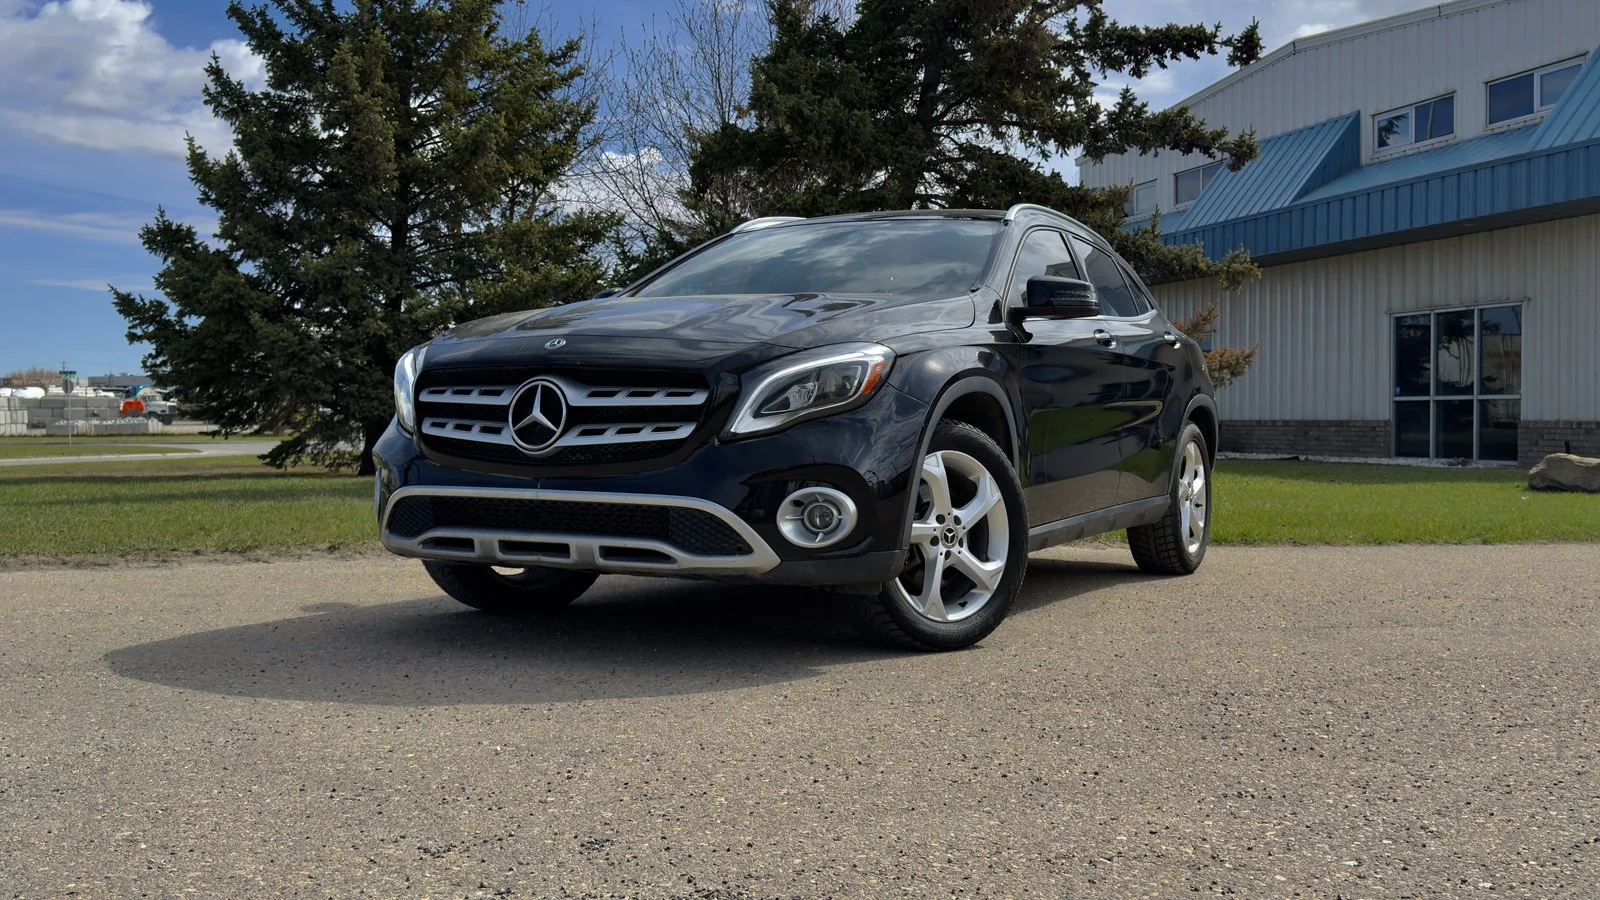
2020 Mercedes-Benz GLA250 4Matic
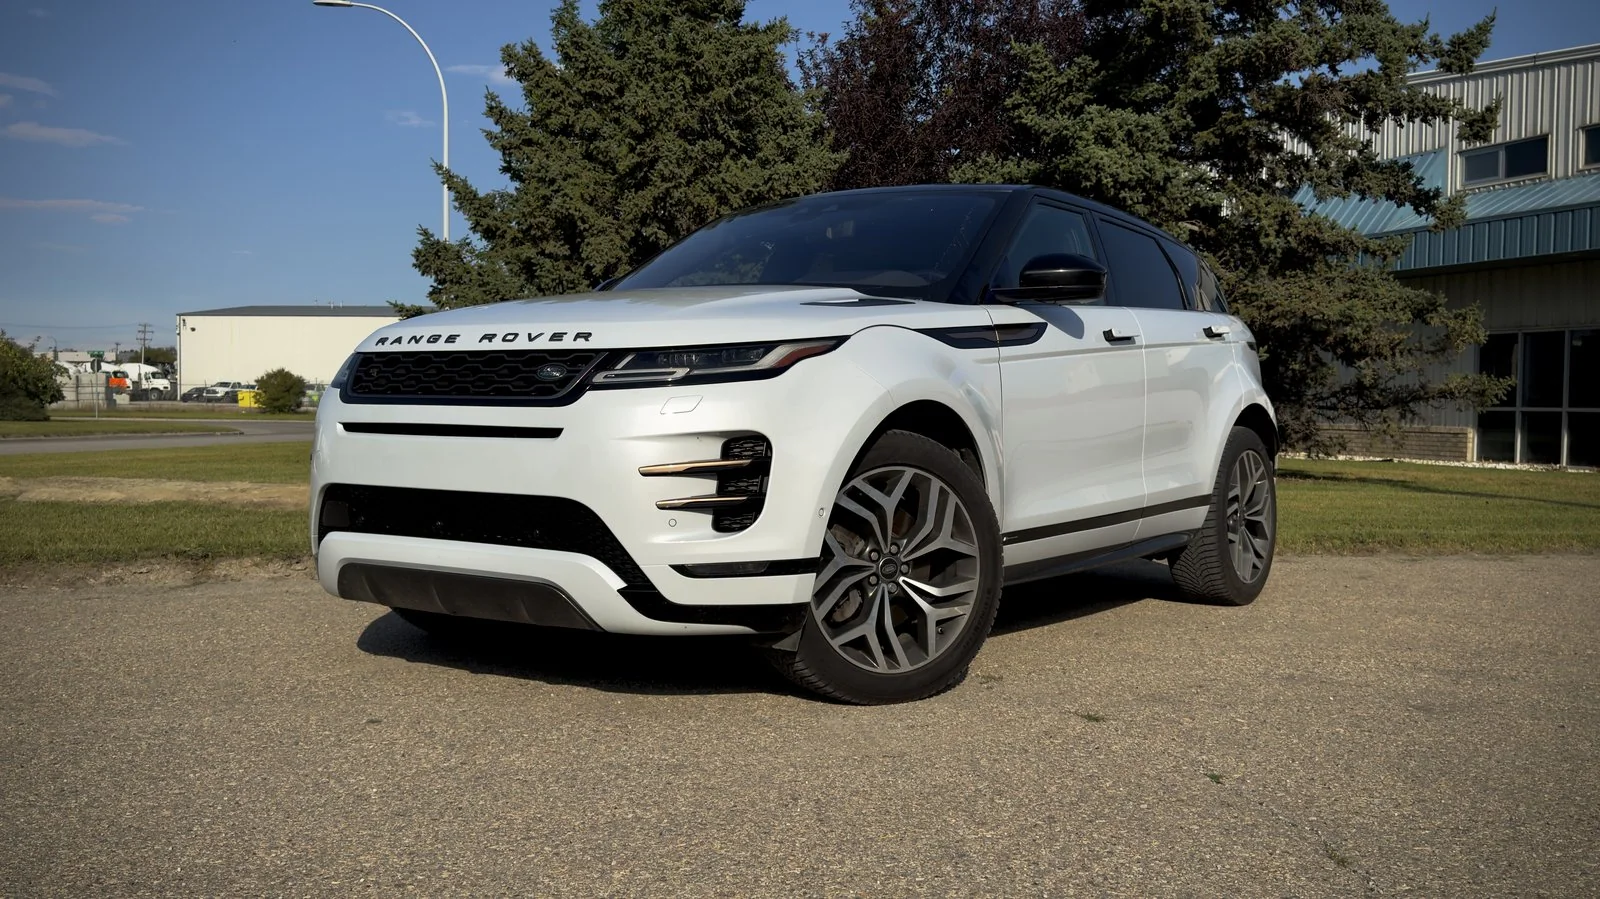
2020 Land Rover Range Rover Evoque P250 First Edition
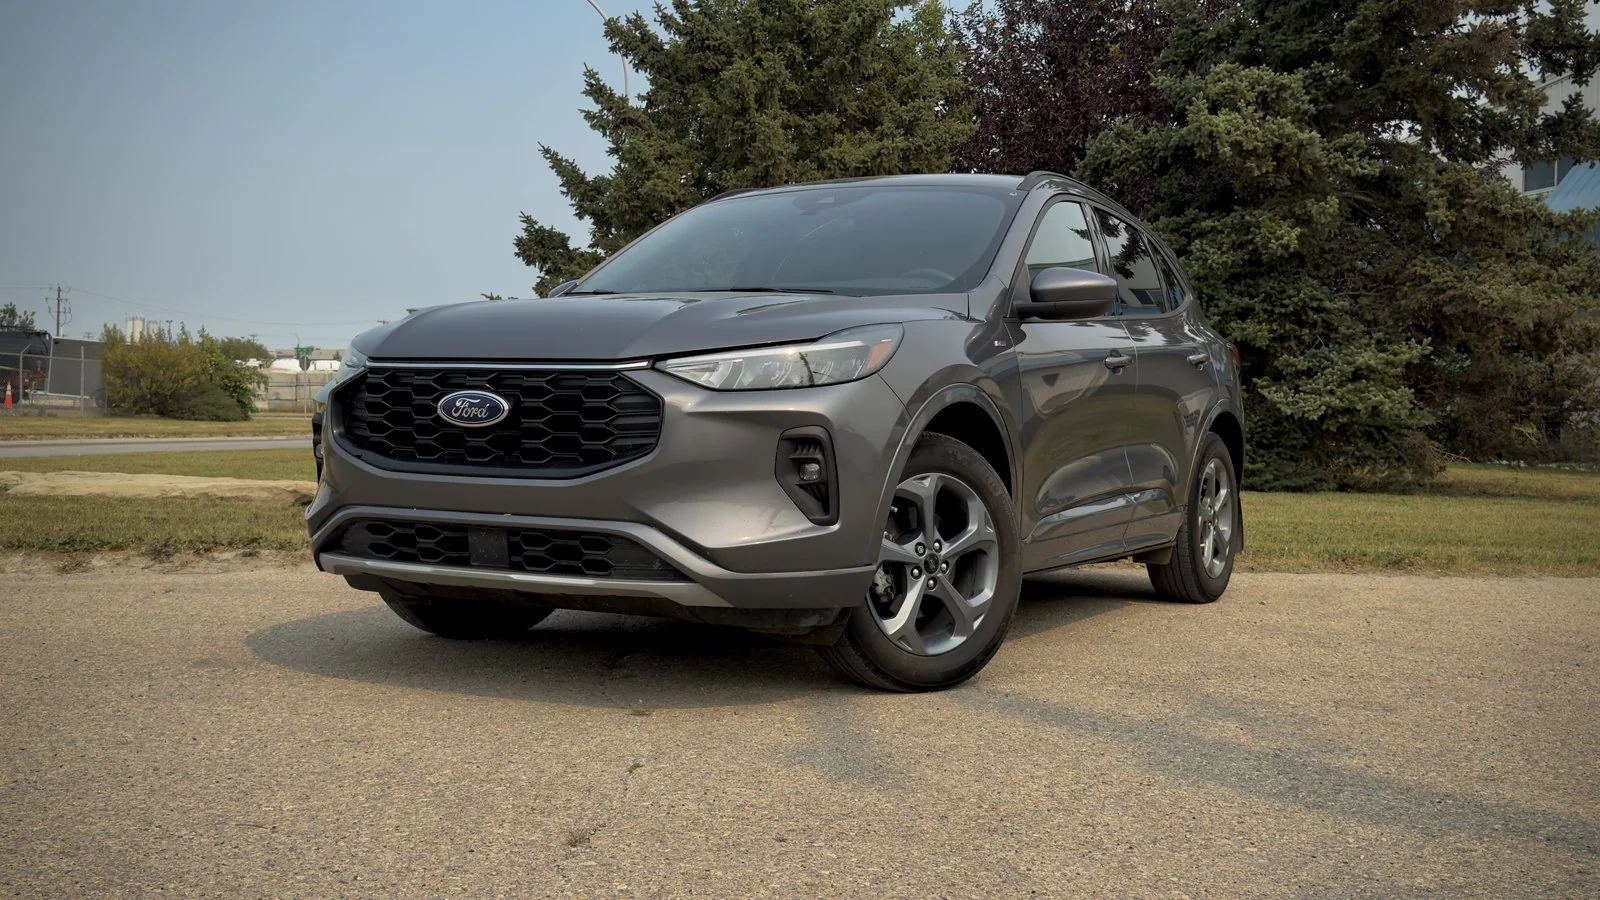
2024 Ford Escape Hybrid ST-Line
Not seeing it? We'll find it.
We source through our dealer partner network across Western Canada: 25,000+ vehicles to choose from. Tell us what you want and what works for your budget.
Find my car3 min · no credit impactOAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Where to go from here
Other Financing Options
Related Special-Situation Financing
Ready to Find the Right Vehicle for Your Family?
Apply online in 3 minutes or call us to talk through your situation. We understand single-parent financing and work with lenders who do too.
No judgment. No pressure. Just honest help finding a vehicle that works for your family.