AISH Car Loan Alberta — Vehicle Financing on Disability Income
AISH (Assured Income for the Severely Handicapped) pays up to $1,940 a month as of July 2, 2026. Lenders can count it as income, together with anything else you can prove. Here is what they usually look at, and when to call us before you apply.
Last reviewed: October 2026
What lenders typically need
AISH is steady monthly income, and lenders do look at it. Since July 2026 many people who were on AISH are on ADAP instead, so bring whichever award letter you have now. Lenders also look at everything else coming in.
In our experience, lenders typically look for about $2,800 a month in income you can prove, from all sources combined. Benefits like AISH, ADAP, CPP Disability, EI and the Canada Child Benefit can count toward that alongside work or support income. Every lender decides each file. If you're under that, talk to us first — a co-applicant, a larger down payment or a few months of income history can change the picture.
Where to go from here
Key Facts
- AISH benefit (2026)
- Up to $1,940/mo from July 2, 2026
- ADAP core benefit
- $1,740/mo
- What lenders add up
- All income you can prove
- Typical target
- About $2,800/mo total
- Credit
- We work with all credit situations
AISH Is Steady Income — Lenders Look at the Whole Picture
Can You Get a Car Loan on AISH in Alberta?
Often, yes. AISH can count as income. What matters is your total income from every source you can prove, along with your credit and the vehicle.
Banks often turn away benefit income because their systems are built around pay stubs. Specialist lenders can read a benefit letter. We work with all credit situations, and every lender decides each file.
AISH Can Count as Income
Lenders can count AISH because it is documented and arrives on a schedule. They still look at your total income, your debts and your credit. Every lender decides each file.
When AISH Is Your Only Income
In our experience, files with about $2,800 a month in total income have the most options. If AISH is all you have, a co-applicant with steady income, a larger down payment or a few months of income history can change the picture. Call us first and we will tell you plainly where you stand.
Banks and Specialist Lenders Read Benefit Income Differently
Banks often use automatic systems built around pay stubs. Specialist lenders can read a benefit letter and bank statements. We review every application and call you back; we cannot promise a result.
We work with all credit situations. AISH income combined with any credit history is a workable application — the lender options vary by credit tier, but options exist at every level.
What Documents Do AISH Recipients Need for a Car Loan?
The AISH documentation package is simpler than employment-based applications — no pay stubs, no employer letters, no NOAs required. Your benefit statement and bank statements are the core of your file.
Gathering your documents before you apply eliminates delays. Most AISH applications are processed within a few hours when the file is complete. Missing documents are the primary source of delays.
AISH Benefit Statement
Your current AISH benefit confirmation letter or statement from Alberta Seniors, Community and Social Services. This is the primary income document and confirms both the amount and the ongoing nature of your benefit. If your benefit amount has recently changed, provide the most recent statement showing the current amount. Lenders want to see the current active benefit — older statements from prior years carry less weight.
Bank Statements (3 Months)
Three months of bank statements showing regular AISH deposits. This corroborates your benefit statement and shows your spending pattern. Lenders are looking for: consistent AISH deposits matching your stated benefit amount, and overall account management that does not suggest financial chaos (e.g., persistent overdrafts, NSF fees). Clean, consistent deposits over three months build confidence significantly.
Government-Issued Photo ID
A valid Alberta driver's license, provincial ID card, or Canadian passport. Your ID must match your current address — if you have moved recently and your ID has an old address, bring a utility bill or bank statement confirming your current address as well. This is standard for any financing application.
If You Also Work, Bring Pay Stubs
Your benefit letter and three months of bank statements are the core documents. If you have part-time work or a partner with income, add pay stubs or their documents. More proof of income gives lenders more to work with.
What Vehicles Are Realistic on AISH Income?
Fuel economy and reliability matter more on a fixed income, because running costs are a fixed part of your budget.
Choosing the right vehicle at the right payment matters as much as the application. A vehicle that stretches your payment creates financial stress every month. A reliable vehicle in the right price range frees up income for everything else.
Pick the Payment First, Then the Vehicle
Decide what monthly payment fits your budget before you look at cars. A reliable, lower-priced vehicle leaves room for insurance and fuel. Do not let anyone stretch you into a payment you cannot keep up with.
Fuel Economy and Operating Cost Matter on Fixed Income
A fuel-efficient vehicle costs less every month. On a fixed income, that adds up.
Reliability Over Newness
On fixed income, a breakdown is not just an inconvenience — it is a financial crisis if the repair cost exceeds your budget. Prioritize reliability over newness. A well-maintained 2018 Toyota Corolla at $14,000 with service records is a far better choice than a newer vehicle with unknown history at the same price. Japanese brands with strong long-term reliability track records (Toyota, Honda) reduce the probability of an unexpected repair hitting your fixed income.
Insurance Budget on Fixed Income
Insurance depends on your driving history, where you live and the vehicle. Get a quote before you commit, and count it in your budget.
Can You Combine AISH with Other Income Sources?
Yes, and it helps. Work income, a partner's income, CPP Disability and the Canada Child Benefit can all count toward your total, as long as you can document them. Part-time work up to $350 a month does not reduce AISH for a single client.
The AISH work income exemption is underutilized. Many AISH recipients do not realize that part-time work income below the exemption threshold both adds to their monthly income AND strengthens their car loan application — without reducing their AISH benefit by a single dollar.
AISH Part-Time Work Exemption
AISH lets a single client earn up to $350 a month from work before benefits are reduced. ADAP lets a single client earn up to $700 a month. Pay stubs for that work add to the income a lender can see. Rules differ if you live with a partner or have dependants, so confirm your own limit with your caseworker.
Spousal or Common-Law Partner Income
If you have a spouse or common-law partner with income, their income can be considered on a joint application. A joint application with AISH as one income source and employment income as another is a stronger file than AISH alone. Both applicants must consent to a credit check. The joint income gives lenders more flexibility on vehicle price, term, and rate — and the partner with stronger credit improves the overall application profile.
CPP Disability and Other Benefits
Some AISH recipients also receive CPP Disability benefits. CPP Disability is a federally administered program and is also recognized as stable income by lenders. If you receive both AISH and CPP Disability, both can count toward your total income. Provide documentation for each income source — benefit confirmation letters and bank statements showing deposits for both programs.
Child Tax Benefit and Other Non-Employment Income
Canada Child Benefit (CCB) payments can sometimes be included as supplemental income, particularly for single parents receiving AISH. CCB is a federal benefit and is generally recognized as stable, predictable income. The amount must be documented via CRA My Account or a benefit statement. Whether a given lender includes CCB as qualifying income varies — some do, some do not. We ask about all income sources during the application to maximize what we can present.
Tell us about all your income sources when you apply — even small amounts add up and can be the difference between an approval at one vehicle price versus a higher one.
AISH Car Loan FAQs
Can I get a car loan on AISH or ADAP in Alberta?
Often, yes. Lenders can count AISH and ADAP as income, and they look at your total income from every source you can prove. In our experience, about $2,800 a month is where files tend to work. Every lender decides each file. If you are under that, call us first and we will tell you plainly what could change it.
How much does AISH pay in 2026, and how do lenders use it?
AISH pays up to $1,940 a month as of July 2, 2026. ADAP's core benefit is $1,740 a month. Lenders add your benefit to other income you can prove, like work, a partner's income or a pension, and compare the total with the payment. Your award letter and three months of bank statements show it clearly.
Who is on AISH and who moved to ADAP in July 2026?
Since July 2026, most people who were on AISH moved to ADAP. People with a severe developmental disability, a palliative or terminal condition, people in continuing-care homes and people 60 or older stayed on AISH unless they chose to move. Bring whichever award letter you receive now.
Can I work part-time and still have my AISH count?
Yes. A single AISH client can earn up to $350 a month from work before benefits are reduced, and a single ADAP client can earn up to $700. Pay stubs for that work add to the income a lender can see. The limits are different with a partner or dependants, so check yours with your caseworker.
What if my total income is under what you mention?
Talk to us before you apply. A co-applicant with steady income, a larger down payment or a few months of income history can change the picture. Waiting can help too. We would rather give you a straight answer by phone than have you apply and collect a credit inquiry for nothing.
Does bad credit change how AISH income counts?
Benefit income can still count. Lenders look at income, credit and the vehicle together, so a bruised score can mean a higher rate or a larger down payment. We work with all credit situations, including past collections, consumer proposals and thin files. Every lender decides each file.
Does financing a vehicle affect AISH or ADAP?
We cannot speak for Alberta's benefit rules. How a vehicle is treated for AISH or ADAP is decided by your caseworker, so ask them before you buy. If you get an answer, bring it with you and we will build the payment around it.
What documents do lenders usually ask for?
Usually your AISH or ADAP benefit letter, three months of bank statements showing the deposits, government photo ID and proof of address. Add pay stubs or a partner's documents if you have them. We review every application and call you back; we do not promise a timeline or a result.
Sources (checked October 2026): Government of Alberta — AISH and ADAP financial benefits summary, Government of Alberta — Alberta Disability Assistance Program. Benefit amounts change; your own letter shows your real amount.
Related Resources
Related Buyer Guides
Learn how AISH and other benefit incomes are treated by lenders — and the approval strategy that works for government income recipients.
What Our Customers Say
“Thanks to Luke and his team. They were able to find me my dream car and have it delivered between cities. Easy to deal with and easy to work with.”
“A huge thank you to Wes and Luke for making my vehicle purchase such a great experience. This has been the best experience I've had at a dealership. They were patient, kind, and attentive.”
“Working with Shift Happens was a great experience. Dima and Luke were both professional, friendly, and always quick to respond. They made the process simple and stress-free.”
Cars you could drive home
See all inventory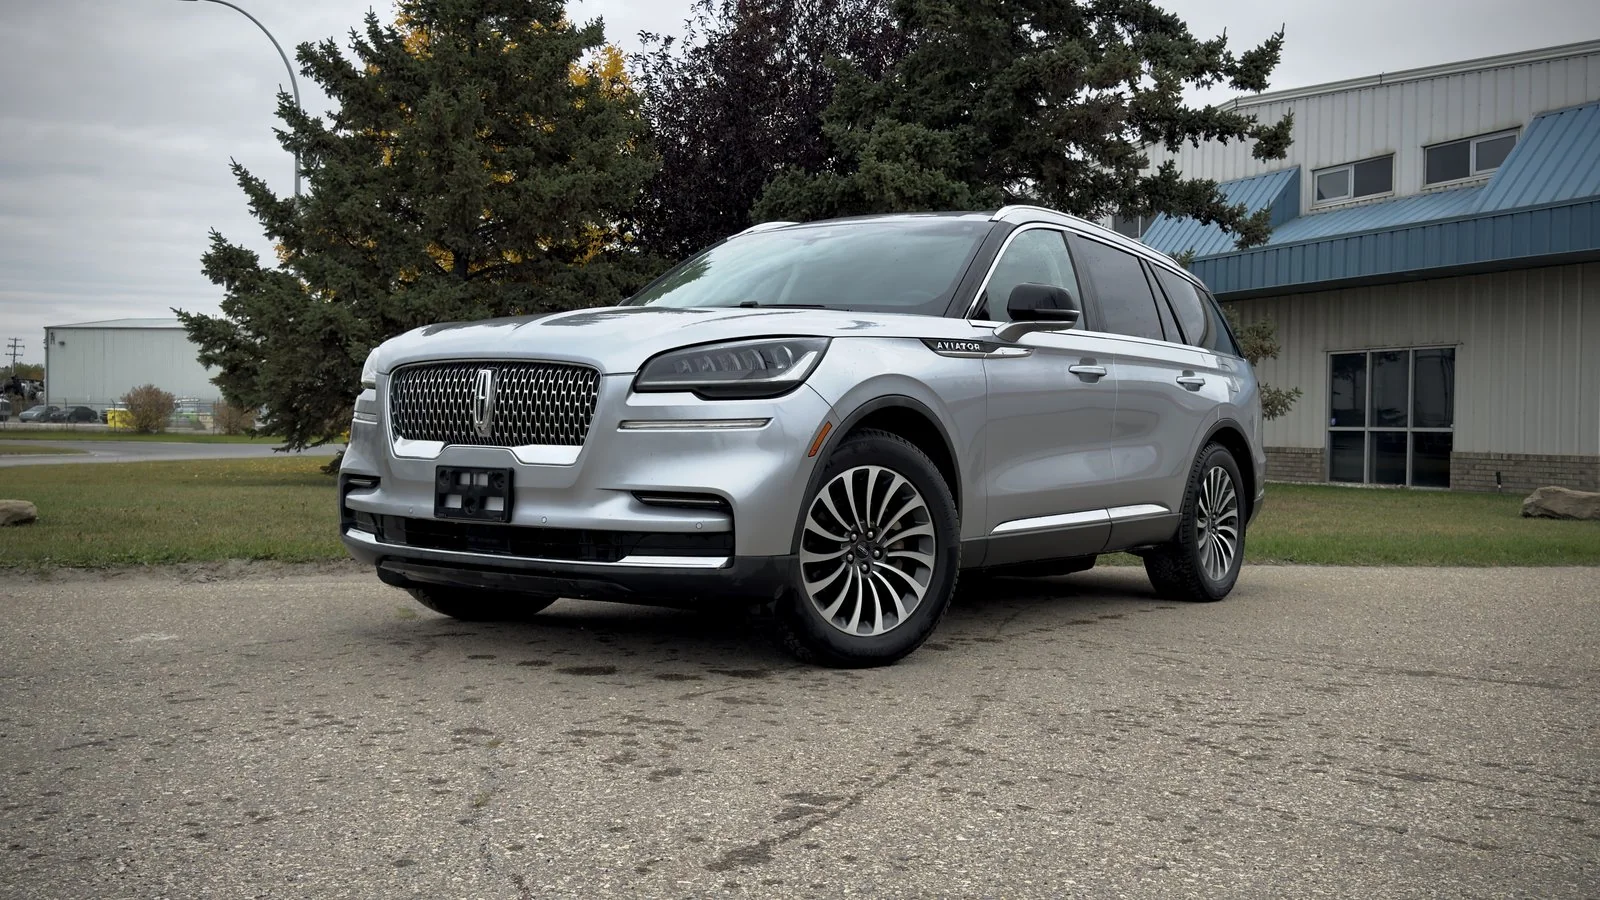
2022 Lincoln Aviator Reserve
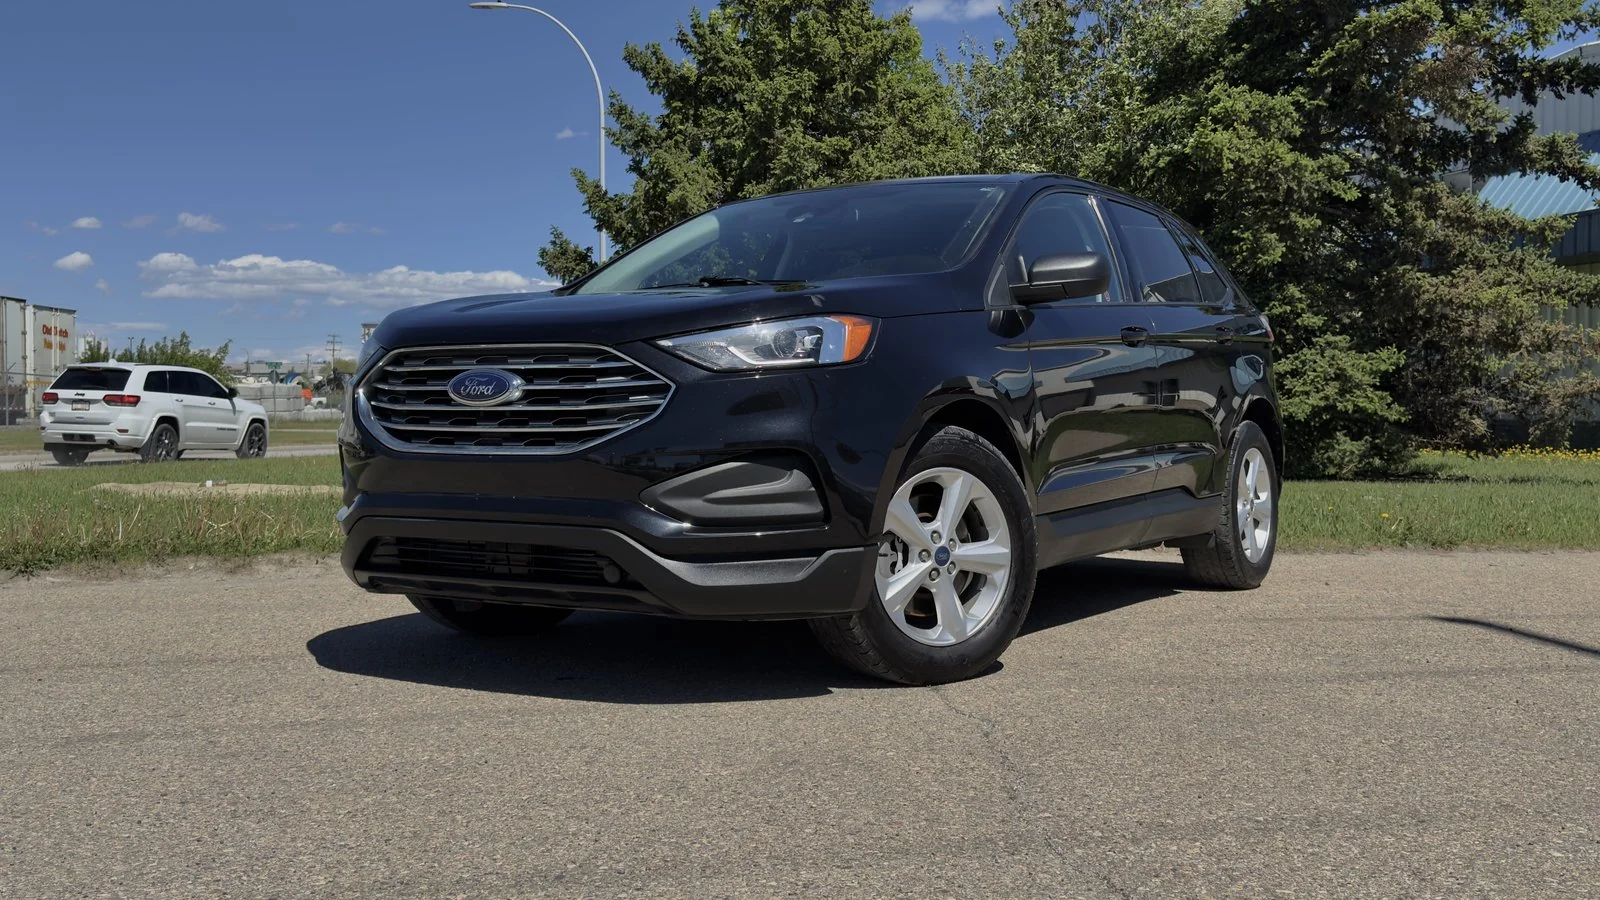
2020 Ford Edge SE
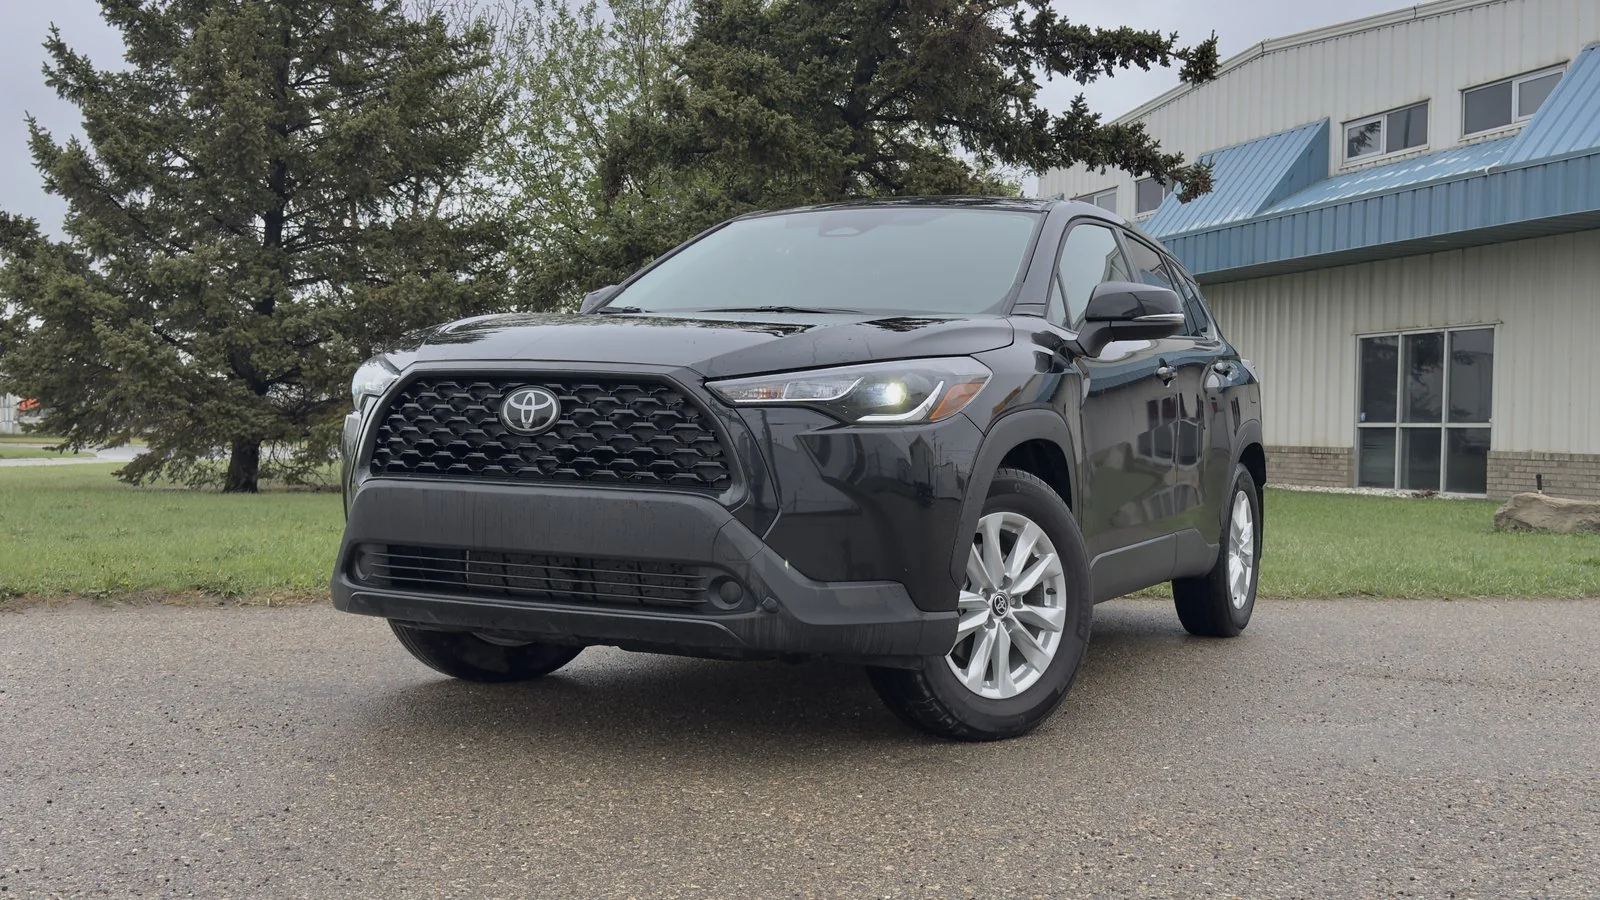
2024 Toyota Corolla Cross LE
2020 Mercedes-Benz GLA250 4Matic
Not seeing it? We'll find it.
We source through our dealer partner network across Western Canada: 25,000+ vehicles to choose from. Tell us what you want and what works for your budget.
Find my car3 min · no credit impactOAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Where to go from here
Other Financing Options
Ready to Apply on AISH Income?
Gather your AISH benefit statement and 3 months of bank statements, then apply in 3 minutes. We understand government benefit income and work with lenders who do too. We work with all credit situations.
Not sure what vehicle is realistic on your income? Call us — we will tell you exactly what payment and price range to expect before you apply.