Car Financing for Seniors in Alberta
CPP, OAS, GIS and pension income can count as income for vehicle financing. Retirement does not rule you out, and many retirees have long, clean credit histories. Here is what lenders usually look at.
Last reviewed: October 2026
What lenders typically need
CPP, OAS, GIS, a workplace pension and RRIF withdrawals can all count as income. Lenders add them together, along with any work income, and compare the total with the payment.
In our experience, lenders typically look for about $2,800 a month in income you can prove, from all sources combined. Benefits like AISH, ADAP, CPP Disability, EI and the Canada Child Benefit can count toward that alongside work or support income. Every lender decides each file. If you're under that, talk to us first — a co-applicant, a larger down payment or a few months of income history can change the picture.
Where to go from here
Key Facts
- CPP retirement benefit
- Can count as income — your statement shows your amount
- OAS
- Can count as income
- GIS
- Can count as income when documented
- Typical target
- About $2,800/mo total income
- Interest rate range
- 4.99%–29.9% APR
Can Seniors Get a Car Loan in Alberta?
Absolutely — and there is no age limit on vehicle financing in Canada. The Canadian Human Rights Act explicitly prohibits age discrimination in financial services. Lenders are legally required to evaluate your application on income, credit history, and ability to repay. Your age is not a factor in the decision.
What lenders actually evaluate is whether you have stable, verifiable income and a reasonable history of repaying debts. Retirement income — CPP, OAS, GIS, employer pensions, RRIF withdrawals — satisfies the income requirement. And many retirees carry decades of credit history that younger borrowers simply cannot match.
The Misconception Worth Correcting
Many seniors assume lenders will say no because they are no longer employed. Lenders look at repayment ability, not employment status. Retirement income arrives on a fixed schedule with no risk of layoff or seasonal gaps, which makes it easy to document. It is still one part of your file, along with your debts and credit.
Canadian Human Rights Act Protections
Age is a prohibited ground of discrimination under the Canadian Human Rights Act, and this applies to financial services including lending. A lender cannot deny a loan application because of the applicant's age. If you have qualifying income and a reasonable credit history, you are entitled to the same consideration as any other applicant. We work with lenders who understand this and evaluate applications on merit.
What Lenders Actually Look At
Vehicle loan approvals come down to three things: income (amount and consistency), credit history (payment behaviour over time), and debt-to-income ratio (monthly obligations vs. monthly income). Seniors often score well on all three. Your CPP and OAS income is consistent and verifiable. Your credit history may span 30 to 40 years of responsible use. And without a mortgage or employment-related debt, your debt-to-income ratio may be lower than most applicants your lender sees.
We Work with All Credit Situations
Whether your credit is excellent, challenged, or somewhere in between — we work with all credit situations. Our lender network of 21+ institutions includes specialists in subprime financing who understand how to evaluate fixed-income applications. One application goes to multiple lenders so you get the best available rate without repeated credit inquiries.
Fixed Income Sources That Qualify for Car Financing
CPP, OAS, GIS, employer pensions, and RRIF withdrawals all count as income. Lenders need to verify that income is stable, recurring, and verifiable — government retirement benefits satisfy all three requirements.
Most Albertan retirees receive income from multiple sources. The total combined monthly income from all sources is what lenders use to assess your application — every stream you have strengthens the picture.
Canada Pension Plan (CPP)
CPP retirement benefits are federally administered and deposited monthly for life. Most recipients receive less than the maximum, depending on their contributions, so your own statement is the number that matters. CPP is indexed to inflation. If you deferred CPP past 65, your monthly amount is higher. Provide your most recent CPP benefit statement or bank statements showing the monthly deposit from the Government of Canada.
Old Age Security (OAS)
OAS is available to most Canadians at age 65. It is indexed to the cost of living and deposited directly from the federal government. At age 75, OAS increases by 10%. Like CPP, OAS arrives on a predictable schedule. Lenders can count it as income; bring your T4A(OAS) slip or bank statements.
Guaranteed Income Supplement (GIS)
GIS is a monthly non-taxable benefit for OAS recipients with low income. Because GIS is means-tested, some worry lenders will not count it. Many lenders can count it as regular government income when it is documented through Service Canada. If GIS is a large part of your income, bring your current GIS notice or bank statements.
Employer Pension and Defined Benefit Plans
If you worked for an employer with a defined benefit pension — including government, military, RCMP, or major private employers — your monthly pension income is highly attractive to lenders. Defined benefit pensions pay a guaranteed amount for life, often indexed to inflation, and do not depend on market performance. A pension statement from your former employer's pension administrator, showing the monthly payment amount, is all the documentation you need.
RRIF Withdrawals and Investment Income
Registered Retirement Income Fund (RRIF) withdrawals are treated as income by most lenders, provided the withdrawals are regular and verifiable. Many retirees set up annual or monthly withdrawal schedules that function exactly like a pension payment. A statement from your financial institution confirming your RRIF balance and annual withdrawal schedule is typically sufficient. Consistent annuity payments and regular investment income distributions are treated similarly.
Combining Multiple Income Sources
The majority of Alberta retirees draw from several sources: CPP plus OAS, plus a workplace pension, plus RRIF withdrawals. Lenders add these together to get your total monthly income, then compare it with your payment and debts. Document each stream and present them together. In our experience, about $2,800 a month in total income is where files tend to work.
Why Seniors Often Have Strong Borrower Profiles
Retirement does not weaken your financial profile — in many ways it strengthens it. Here is what lenders see when they review a senior's application.
Long, Established Credit History
Credit scores reward length of credit history. A 70-year-old with a mortgage paid off 15 years ago, two credit cards used responsibly for decades, and a car loan closed without issue has a credit profile that simply cannot be replicated by a younger borrower. Length of history — the age of your oldest account, average account age — is a meaningful component of credit scoring. Years of responsible management are an asset, not a footnote.
Stable, Predictable Income
Employment income fluctuates — hours change, layoffs happen, businesses close. Government retirement income does not. CPP, OAS, and GIS arrive on the same day every month in a known amount, indexed to inflation. From an underwriting standpoint, that predictability reduces default risk. Lenders who work with seniors regularly note that retirement income is often more reliable than employment income for the purpose of loan qualification.
Lower Debt-to-Income Ratios
Many retirees have eliminated their largest debts — mortgage paid off, children through school, no business debt. This means your monthly obligations relative to your income may be very low. Lenders calculate the debt-to-income ratio to assess how much room you have to take on a new payment. A retiree with no mortgage and no other loans has more room for a new payment than most. Lenders still look at income, debts and credit together, and every lender decides each file.
Payment History Built Over Decades
Payment history is the most heavily weighted factor in Canadian credit scoring — typically around 35% of the total score. If you have consistently paid bills on time for 30 or 40 years, that history speaks for itself. A single missed payment from decades ago has far less impact than it would for a younger borrower with a shorter record. Recent on-time payments carry the most weight, but a long positive pattern is a genuine advantage.
Choosing the Right Vehicle for Your Needs
The right vehicle for a retiree in Alberta is not the same as the right vehicle for a 28-year-old commuter. Here is what to prioritize, and what to avoid, when selecting a vehicle on a fixed income.
Entry and Exit Comfort: SUVs vs. Sedans vs. Trucks
Step-in height makes a real difference in daily comfort. Compact and mid-size crossovers — Toyota RAV4, Honda CR-V, Hyundai Tucson, Ford Escape — provide a seat height that avoids the low drop of a sedan and the high climb of a full-size truck or SUV. You sit at roughly hip height and swing your legs in, which is easier on knees, hips, and backs. Many come with power seats that adjust forward and back automatically, further reducing the effort required.
Safety Features That Matter for Alberta Driving
Modern safety technology adds genuine protection and reduces driver workload. Automatic emergency braking responds faster than human reaction time. Blind-spot monitoring covers the zones that are hardest to see when turning your head is difficult. Lane-keeping assist prevents drift during highway driving. Rearview cameras eliminate the contortions required by mirrors alone. These are not luxury features — they are practical tools that many newer vehicles include as standard equipment. We can help you identify inventory with the specific safety tech you want.
Comfort Features for Alberta Winters
Alberta winters are not optional. Heated front seats make the first minutes of a cold-weather drive far more comfortable, particularly if joint stiffness is a factor. A heated steering wheel, remote start, and heated mirrors are low-cost upgrades that compound comfort over a long Alberta winter. All-wheel drive provides confidence on icy roads and unplowed parking lots. We look for these features specifically when helping customers who prioritize year-round comfort and safety.
Reliability and Total Cost of Ownership
On a fixed income, an unexpected $2,000 repair bill is not an inconvenience — it is a serious disruption. Reliability matters more than it might at other life stages. Toyota, Honda, and Mazda consistently rank at the top of long-term reliability studies. A three-to-five-year-old vehicle with moderate mileage from a high-reliability brand often represents better value than a newer, higher-trim vehicle from a brand with a weaker reliability record. Every vehicle we sell passes an AMVIC-compliant inspection before delivery.
Fuel Efficiency on a Fixed Income
Fuel costs are an ongoing fixed expense that compounds over the life of a vehicle. A vehicle averaging 9 L/100km versus 7 L/100km at $1.50/litre costs roughly $300 more per year at 10,000 km of annual driving — and more at higher mileage. Compact and mid-size crossovers generally hit the balance point between usability and fuel economy. Hybrids, if in budget, reduce fuel costs further and have proven long-term reliability records in the Toyota and Honda lineups.
Loan Term Strategy for Fixed Income Borrowers
For most retirees on fixed income, shorter loan terms are the better choice — less total interest, predictable end date, and the vehicle is paid off while it is still reliable.
The financing market offers terms from 12 to 96 months. Longer terms lower the monthly payment but increase total interest paid significantly. Here is how to think through the decision.
The Interest Cost of a Longer Term
A longer term lowers the monthly payment but raises the total interest you pay. On a fixed income, the cheapest total cost is often better than the smallest payment.
- Gross pay
- $3,200 a month
- Credit score
- 650–749
- Vehicle
- Used sedan, $20,000
- Down payment
- $0
- Amount financed
- $20,000 over 48 months
- Example rate
- 9.9% APR (Near-Prime example)
Payment:~$233/bi-weekly(or ~$506/mo)
That is about 16% of gross monthly pay. A common rule of thumb is to keep a car payment under 15% of gross pay.
Example, not an offer. Your rate depends on your file; rates run from 4.99% APR (prime) to 29.9% APR (deep subprime).
- Gross pay
- $3,200 a month
- Credit score
- 650–749
- Vehicle
- Used sedan, $20,000
- Down payment
- $0
- Amount financed
- $20,000 over 84 months
- Example rate
- 9.9% APR (Near-Prime example)
Payment:~$153/bi-weekly(or ~$331/mo)
That is about 10% of gross monthly pay. A common rule of thumb is to keep a car payment under 15% of gross pay.
Example, not an offer. Your rate depends on your file; rates run from 4.99% APR (prime) to 29.9% APR (deep subprime).
Matching Term Length to Vehicle Reliability
A 96-month loan on a used vehicle means you will be making payments on an 8-to-10-year-old car at the end of the term. If the vehicle requires significant repairs in years 6 through 8, you may be managing both a loan payment and repair costs simultaneously. A 48-to-60-month term on a reliable 3-to-4-year-old vehicle usually means the loan is paid off before the vehicle reaches the age where major repairs become common.
Down Payment: Reducing the Monthly Obligation
A larger down payment reduces the amount you borrow and therefore the monthly payment. Using some savings to borrow less often makes more financial sense than stretching the term.
What We Will Show You at the Dealership
When we present financing options, we show you the total cost across multiple term lengths — not just the monthly payment. You will see exactly what you pay in interest at 36, 48, 60, and 72 months so you can make an informed decision based on your budget and priorities. There is no pressure toward longer terms — we want you in a payment that works for your life.
Senior Car Financing in Alberta
Alberta has specific context worth understanding — from provincial resources to the practical realities of driving in this province as a retiree.
Alberta's Senior Population and Transportation Access
Alberta's population of adults 65 and older is growing faster than the national average, driven by interprovincial migration and longer life expectancy. Outside Calgary and Edmonton, public transit options are limited — a personal vehicle remains essential for medical appointments, grocery runs, and maintaining social connections. Vehicle independence is not a luxury for most Alberta seniors; it is a practical necessity.
AMVIC Licensing and Consumer Protections
Shift Happens Auto Sales is a licensed dealer under the Alberta Motor Vehicle Industry Council (AMVIC). AMVIC licensing means every vehicle we sell is represented accurately, every transaction is disclosed, and you have access to the AMVIC Compensation Fund as a buyer protection. This matters when you are making a significant purchase on a fixed income — you want a dealer who operates under regulated standards, not a private seller with no accountability.
Delivery Service Across Alberta
We offer free vehicle delivery within 300km and delivery options province-wide. If getting to our lot is difficult — whether you live in a rural area, a care community, or a city where driving long distances is not practical — we bring the vehicle to you. The financing, paperwork, and handover can all be completed at your address or a location that works for your situation.
Alberta Seniors Benefit and Other Provincial Programs
The Alberta Seniors Benefit provides monthly payments to lower-income Alberta seniors, in addition to federal benefits. For financing purposes, this is additional provincial government income that lenders can count toward your total monthly income. Other provincial programs — the Alberta Seniors Property Tax Deferral, prescription drug coverage under the Alberta Seniors Drug Benefit Program — reduce expenses that may otherwise compete with a loan payment. Knowing the full picture of your income and expenses gives you the clearest view of what payment is manageable.
How CPP and OAS Income Qualifies for a Car Loan
Government retirement benefits are among the most lender-friendly income sources available — they are guaranteed, stable, and arrive on a fixed monthly schedule. Here is how each source is documented and how they combine to meet lender thresholds.
Canada Pension Plan (CPP) — T4A(P)
CPP retirement income is documented via a T4A(P) slip issued by Service Canada each February for the prior year. Your monthly CPP amount is also shown on your My Service Canada Account. Bring your most recent T4A(P) or a printout of your current benefit amount. CPP is guaranteed for life and rises with inflation via cost-of-living adjustments.
Old Age Security (OAS) — T4A(OAS)
OAS is documented via a T4A(OAS) slip and your My Service Canada Account. Most Canadians become eligible at age 65. OAS is also guaranteed for life and indexed quarterly to inflation. Lenders add CPP and OAS together with any other income you can prove.
Guaranteed Income Supplement (GIS)
GIS is paid to lower-income OAS recipients and can add to your total income. Like OAS, it is government-guaranteed and documented through Service Canada. Bring your current GIS benefit notice or bank statements showing consistent monthly deposits.
RRSP/RRIF Withdrawals — T4RSP
Regular RRSP or RRIF withdrawals are recognized as income and documented via T4RSP slips or RRIF statements from your financial institution. If you take consistent annual or monthly withdrawals, a letter from your financial institution confirming the withdrawal schedule strengthens your application. RRIF withdrawals are mandatory starting the year after you turn 71, making them a predictable income stream lenders can plan around.
Why Pension Income Is Lender-Friendly
Government pension income is stable, arrives on a fixed schedule and is easy to document, which lenders value. Lenders still look at the whole file, and every lender decides each file.
Senior Car Financing FAQs
Can seniors on CPP and OAS get a car loan in Alberta?
Often, yes. CPP and OAS can count as income, and lenders add them to any pension, RRIF or work income you can prove. In our experience, about $2,800 a month in total income is where files tend to work. Every lender decides each file. If you are under that, call us first.
Is there an age limit for getting a car loan in Canada?
There is no upper age limit on vehicle financing, and the Canadian Human Rights Act prohibits age discrimination in financial services. Lenders look at income, credit history and ability to repay. A long, clean credit history often helps. We review every application and call you back.
Does the Guaranteed Income Supplement count as income?
Many lenders can count GIS as regular government income when it is documented. It is paid monthly and confirmed through Service Canada. Bring your current GIS notice or bank statements showing the deposits. It is added to your CPP, OAS and any other income to give your total.
Do seniors with a long credit history get better rates?
A long history of on-time payments usually helps, because payment history is the biggest part of a credit score. Your rate still depends on your whole file, including income, debts and the vehicle. Every lender decides each file. Call us if you want a straight read before you apply.
What loan term should a senior choose?
A longer term lowers the monthly payment but raises the total interest. On a fixed income, many people choose the shortest term that keeps the payment comfortable. A larger down payment also lowers the loan. Tell us your budget and we will show you the trade-offs before you commit.
Can I use RRIF withdrawals to help with a car loan?
Yes, regular RRIF withdrawals can count as income when you can document them, usually with statements showing the amount and schedule. Lenders add them to CPP, OAS and any pension. Bring recent statements so the total is clear. Every lender decides each file.
Does being retired affect my ability to get a car loan?
Retirement does not rule you out. Lenders look at repayment ability, not employment status. Retirement income arrives on a fixed schedule, which makes it easy to document. They also look at your debts and credit, and every lender decides each file.
What if my retirement income is under that amount?
Talk to us before you apply. A co-applicant with steady income, a larger down payment or a few months of income history can change the picture. We would rather give you a straight answer by phone than have you apply and collect a credit inquiry for nothing.
Sources (checked October 2026): Government of Canada — Old Age Security payments. Benefit amounts change; your own letter shows your real amount.
Related Resources
What Our Customers Say
“Luke was awesome to deal with and made the car buying experience enjoyable again for me and my wife after a few very unpleasant interactions in the past. I would highly recommend.”
“The buying experience was handled very professionally. Wes was very attentive and presented everything in an open and honest manner that gave me the reassurance that I made a good purchase.”
“Luke was fantastic with helping us get into a mini van, we are MORE than happy. I highly recommend anyone looking for a vehicle to go check out Shift Happens!”
Cars you could drive home
See all inventory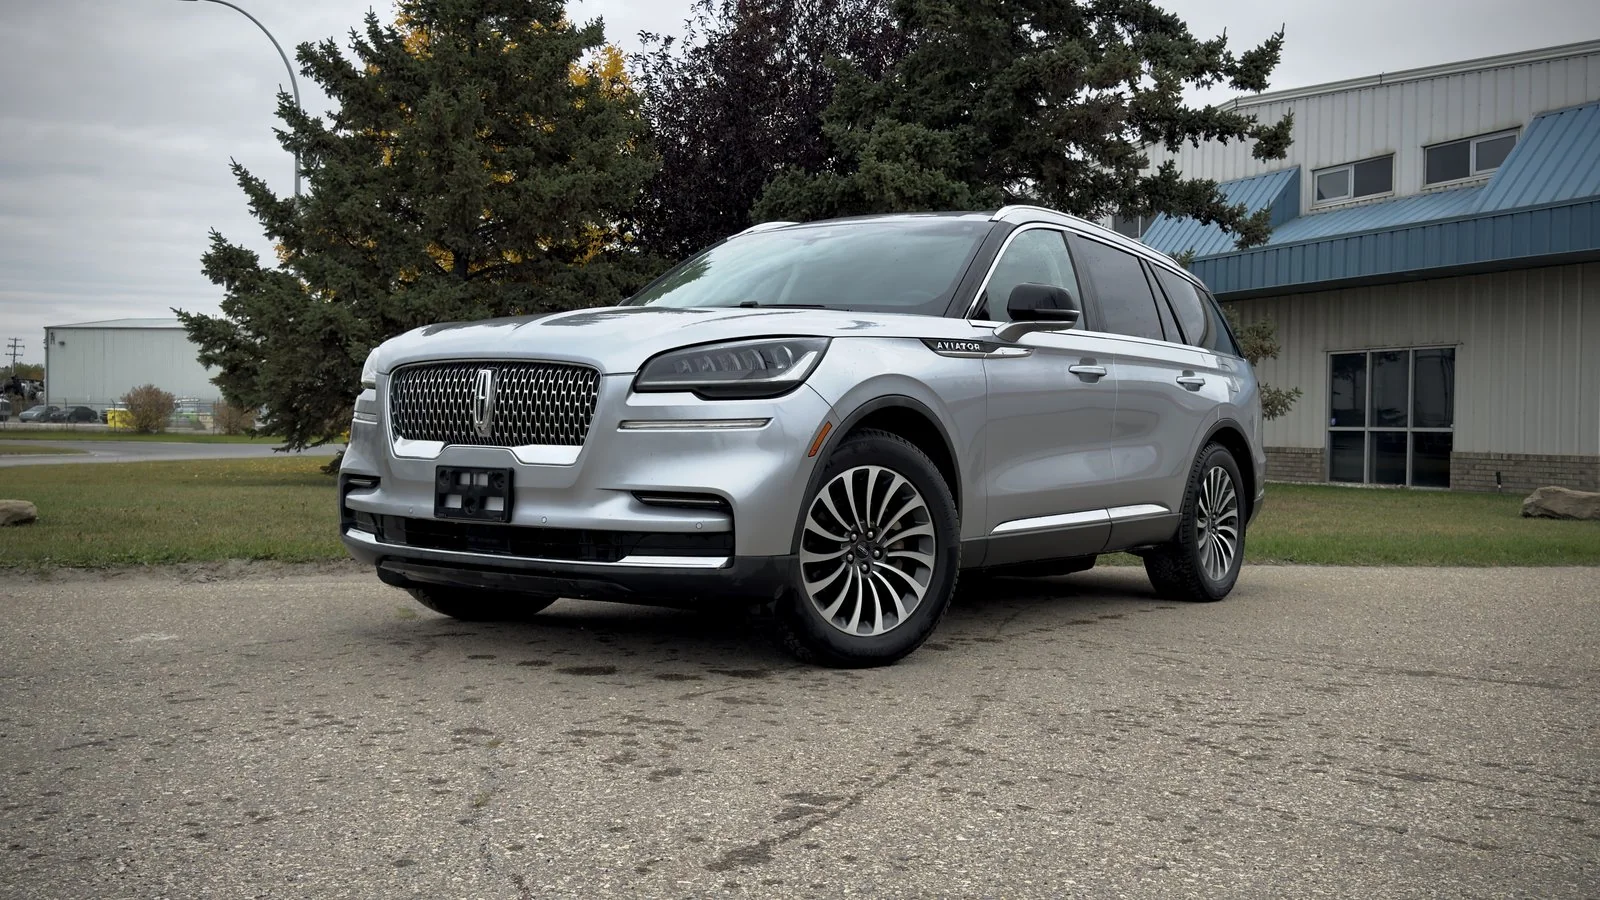
2022 Lincoln Aviator Reserve
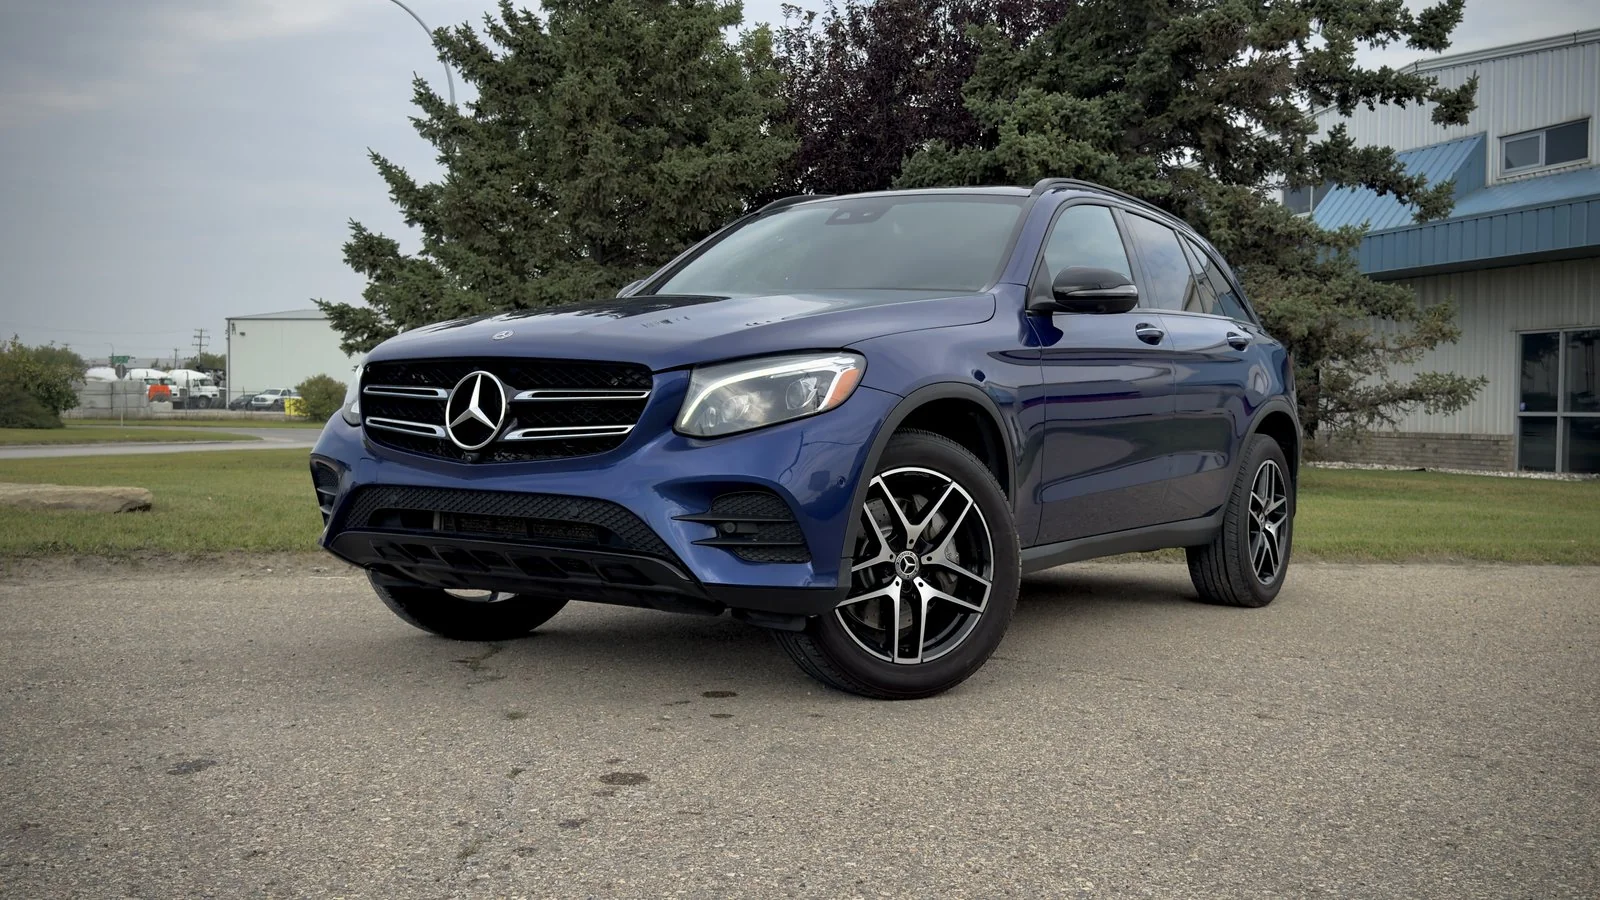
2019 Mercedes-Benz GLC-Class GLC300
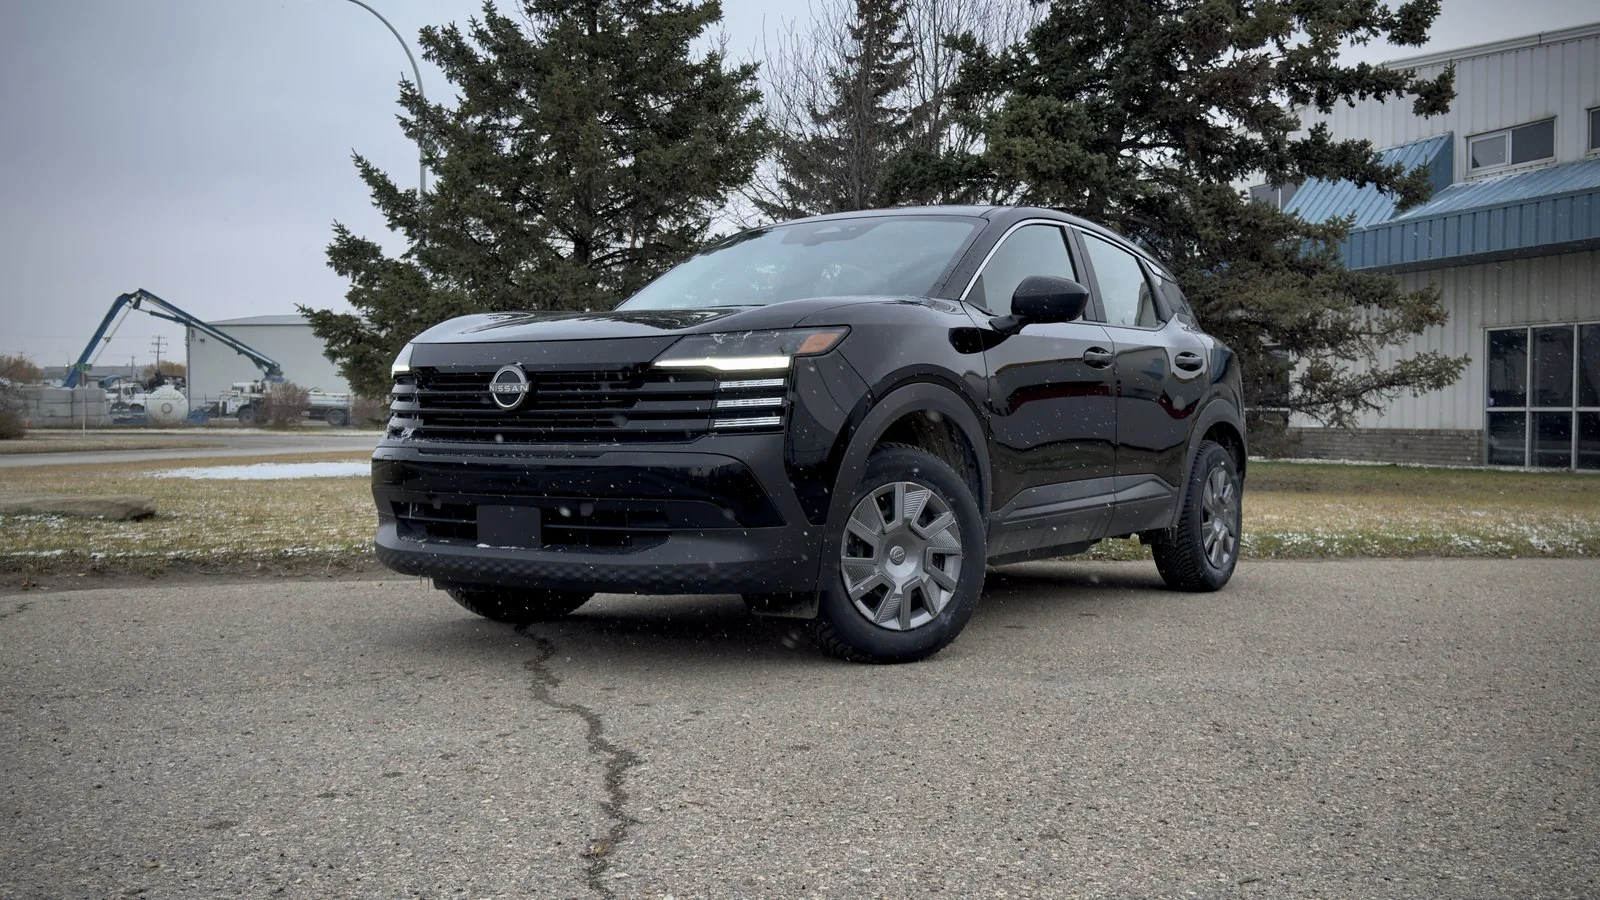
2026 Nissan Kicks S
2020 Ford Edge SE
Not seeing it? We'll find it.
We source through our dealer partner network across Western Canada: 25,000+ vehicles to choose from. Tell us what you want and what works for your budget.
Find my car3 min · no credit impactOAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Where to go from here
Related Special-Situation Financing
Ready to Get Started?
Apply online in about three minutes or call us to talk through your situation. CPP, OAS, GIS and pension income can all count toward what lenders look for, together with anything else you can prove. We work with all credit situations and deliver across Alberta.
AMVIC licensed. No obligation. Respectful, straightforward help getting you into a reliable vehicle.