Car Loan Rates in Alberta
Typical car loan interest rates by credit tier, what a loan costs per payment, and the income those payments usually need.
Rates reviewed Oct 2026 by the Shift Happens finance team
What's a typical car loan interest rate in Alberta right now?
Alberta car loan rates run 4.99%–29.9% APR. Prime credit sits at the low end and deep subprime at the high end. Your rate depends on your score, income, down payment and the vehicle, and every lender decides each file. The tables below show each tier and what a loan costs.
Rates move with your credit tier. Not sure where you stand? Start with our guide to bad credit car loans in Alberta.
See What Rate You Qualify For
Rates from 4.99% to 29.9% APR by credit tier. Check yours in 3 minutes.
5.0118+ Google ReviewsAMVIC LicensedFree Delivery 300km
Who this page is for
- You work, or run a business, and your credit took a hit.
- You want to see the rate and the payment before you apply, so nothing surprises you.
- You want a rough idea of what pay a loan like this takes.
Key Facts
- 21+ lenders
- Prime, subprime and deep subprime programs
- Rate range
- 4.99%–29.9% APR
- Loan length
- Up to 96 months (84 for deep subprime)
- What sets your rate
- Credit tier, income, down payment, vehicle
Rates by credit score
Find your score band. The range shows what borrowers in that band typically see across our lender programs, and your own rate can land anywhere inside it. Each tier also has a longest loan length.
| Credit Tier | Score Range | Typical Rate | Typical Term |
|---|---|---|---|
| Prime | 750+ | 4.99–8.9% | 60–96 months |
| Near-Prime | 650–749 | 6.9–12.9% | 60–96 months |
| Subprime | 600–649 | 7.9–14.9% | 60–96 months |
| Subprime | 550–599 | 9.9–19.9% | 60–96 months |
| Subprime | 500–549 | 14.9–24.9% | 60–96 months |
| Deep Subprime | 450–499 | 19.9–29.9% | 60–84 months |
| Deep Subprime | 300–449 | 24.9–29.9% | 60–84 months |
Rates are typical ranges only. Your actual rate depends on your full credit profile, income, vehicle selection, and lender approval criteria. OAC.
If your pay is steady, read how a good income helps a bad credit car loan.
If you already have a car loan, you can compare refinancing with trading in before you decide.
What a $20k / $30k / $40k loan costs by credit tier
Each row uses that tier's example rate on a 72-month loan with no down payment, before GST and fees. You can pay bi-weekly or monthly. Example, not an offer. Your rate depends on your file; rates run 4.99%–29.9% APR.
| Tier | Example rate | $20k | $30k | $40k |
|---|---|---|---|---|
| Prime | 6.9% | ~$157/bi-weekly~$340/mo | ~$235/bi-weekly~$510/mo | ~$313/bi-weekly~$680/mo |
| Near-Prime | 9.9% | ~$170/bi-weekly~$370/mo | ~$255/bi-weekly~$554/mo | ~$341/bi-weekly~$739/mo |
| Subprime | 16.9% | ~$204/bi-weekly~$444/mo | ~$307/bi-weekly~$666/mo | ~$409/bi-weekly~$888/mo |
| Deep Subprime | 24.9% | ~$247/bi-weekly~$538/mo | ~$371/bi-weekly~$806/mo | ~$495/bi-weekly~$1,075/mo |
All figures are computed from the tier's example rate. Actual payments depend on the amount a lender offers, your down payment, rate and term. OAC.
Income these payments usually need
A common rule of thumb is a payment near 15% of your gross (before-tax) monthly pay. Working backwards, each cell shows the monthly pay that fits the payment in the table above. This is an estimate, not a lender rule. Lenders also look at your other debts.
| Tier | $20k loangross pay | $30k loangross pay | $40k loangross pay |
|---|---|---|---|
| Prime | ~$2,300/mo | ~$3,500/mo | ~$4,600/mo |
| Near-Prime | ~$2,500/mo | ~$3,700/mo | ~$5,000/mo |
| Subprime | ~$3,000/mo | ~$4,500/mo | ~$6,000/mo |
| Deep Subprime | ~$3,600/mo | ~$5,400/mo | ~$7,200/mo |
If your pay is below the figure in your row, a smaller loan, a bigger down payment or a co-applicant can close the gap. Want to try your own numbers? Use the payment calculator. Buying a family SUV or minivan? See the income a 3-row SUV or minivan loan needs at every score band. Planning to buy a home later? See how a car payment counts in mortgage debt ratios.
To go further, see a grid of what each income and score band can usually afford, or read about a 600 score on a steady income. And to see who the loans actually went to, read real car loan approvals in Alberta, shown by credit score and income. Coming off a lease? Compare the buyout price with a used car's payment.
Here is one real-looking file. A buyer earning steady pay, with a score in the 550–599 band, picks a used compact SUV.
- Gross pay
- $4,200 a month
- Credit score
- 550–599
- Vehicle
- used compact SUV, $24,000
- Down payment
- $2,000
- Amount financed
- $22,000 over 72 months
- Example rate
- 16.9% APR (Subprime example)
Payment:~$225/bi-weekly(or ~$488/mo)
That is about 12% of gross monthly pay. A common rule of thumb is to keep a car payment under 15% of gross pay.
Example, not an offer. Your rate depends on your file; rates run from 4.99% APR (prime) to 29.9% APR (deep subprime).
Opens at the Subprime example rate, 16.9%. Change any number below.
Payment Calculator
Estimate your biweekly car payment. Adjust the inputs below — results update instantly.
Loan Details
Est. Biweekly Payment
$188
every 2 weeks
Estimates only. Actual rates depend on your credit profile and lender terms. All financing on approved credit (OAC). Payment examples are for illustration purposes only and do not constitute a loan offer.
How loan length changes the payment on a $25,000 vehicle
What would monthly payments look like across different credit tiers? Here are examples based on a $25,000 vehicle with no down payment. Actual payments will vary based on your approved amount, down payment, and exact rate.
| Tier | Typical Rate | 84 Months | 96 Months |
|---|---|---|---|
| Prime | 6.9% | ~$376/mo | ~$340/mo |
| Near-Prime | 9.9% | ~$414/mo | ~$378/mo |
| Subprime | 16.9% | ~$509/mo | ~$477/mo |
Deep Subprime — 24.9% (max term: 84 months)
| Tier | Typical Rate | 72 Months | 84 Months |
|---|---|---|---|
| Deep Subprime | 24.9% | ~$672/mo | ~$631/mo |
Deep subprime lenders typically cap loan terms at 84 months. 96-month terms are not available at this credit tier.
All examples assume a $25,000 vehicle with no down payment. Payments are approximate and for illustration only. OAC.
Why your rate is what it is
Lenders price five things: your credit history, your income and job stability, your down payment, the vehicle and loan length, and your other debts. Your score gets the attention, but it is one of five. Two people with the same score can get different rates.
- Credit history. Your score and what is on your file (late payments, a proposal, a bankruptcy, collections) place you in a tier.
- Income and job stability. A steady job with a clear pay history lowers the lender's risk.
- Down payment. Putting more down means you borrow less, which lenders see as lower risk.
- The vehicle and the loan length. Newer, lower-kilometre vehicles and shorter terms usually price better.
- Your other debts. Card balances, loans and a proposal payment all count against the payment you can carry.
How to lower your rate in 12 months
The steps that move a rate most are paying down card balances, saving a bigger down payment, and making every payment on time. After 12 to 24 months of on-time payments, some borrowers qualify to refinance at a lower rate. Ask any lender about fees before you refinance.
You have more control over your rate than you might think. These steps can meaningfully improve what lenders offer you — before you apply or over time. Vehicle selection also affects your total monthly cost — choosing a model that is inexpensive to insure in Alberta can offset a higher interest rate by reducing other fixed costs. For the full picture on how subprime lending works, read our guide to subprime auto financing explained.
Pay down card balances first
Lower card balances mean lower monthly debts, which leaves more room in your budget for the car payment. Lenders look at that room.
Save for a bigger down payment
A bigger down payment means you borrow less and the lender carries less risk. It does not promise a lower rate, but it often helps the file.
Show steady pay
Recent pay stubs or an NOA and a few months of bank statements show your income is steady. That is the strongest thing in a credit file that took a hit.
Choose a smaller loan
A smaller loan next to your income is easier for lenders to work with. A vehicle that costs less can change both your rate and your payment.
Bring a co-applicant, if you have one
A co-applicant with stronger credit can help you qualify in a better tier. They are legally responsible for the loan, so it is a big ask for both of you.
Bank vs dealer financing rates
If your credit is strong, start with your own bank or credit union. A bank usually offers its lowest rates to people with strong credit, so it is worth asking.
If a bank turned you down, or your file has a consumer proposal, a bankruptcy, collections or a repossession on it, a dealer that works with many lenders can reach lenders that banks do not offer. Those programs charge more, because the lender takes on more risk. That is why the table above shows a range, not one number.
Whoever you borrow from, ask for the rate, the loan length and the total cost in writing before you sign. Our dealership financing vs bank loan guide walks through the differences, and subprime vs prime financing explains the tiers.
Car loan rate questions
What is a typical car loan interest rate in Alberta?
Across our lender programs, rates run 4.99%–29.9% APR. Prime credit sits near the low end and deep subprime near the high end. The rate tables above show every score band. Your own rate depends on your income, down payment and the vehicle, and each lender decides each file.
What interest rate can I get with bad credit in Alberta?
With bad credit you will usually be priced in the subprime tier (7.9–24.9%) or the deep subprime tier (19.9–29.9%), depending on your score and what is on your file. Steady income, a bigger down payment and a smaller loan can move you toward the lower end of your tier.
Is a dealer car loan rate higher than a bank rate?
A bank often has the lowest rate if your credit is strong. A dealer that works with many lenders can reach programs for people whose credit took a hit, and those programs price higher because the lender takes on more risk. Ask for the rate, loan length and total cost in writing, whoever you borrow from.
Does a longer loan term raise my rate?
Longer terms can carry a slightly higher rate because the lender's money is at risk for longer. They also cost more in total interest even at the same rate, although the payment is lower. Each tier has a longest loan length, shown in the rate table above.
Can I refinance later to get a lower rate?
Many borrowers can. After 12 to 24 months of on-time payments your credit profile often looks stronger, and some qualify for a lower rate. Check for fees on the loan you have now, and compare the total cost, not only the payment, before you refinance.
Does a co-applicant or bigger down payment lower my rate?
A co-applicant with stronger credit can help you qualify in a better tier, but they are legally responsible for the loan too. A bigger down payment means you borrow less, which lenders see as lower risk. Neither is a promise of a lower rate. Each lender decides each file.
Last reviewed October 2026 by the Shift Happens finance team
Cars in stock you could finance
See all inventory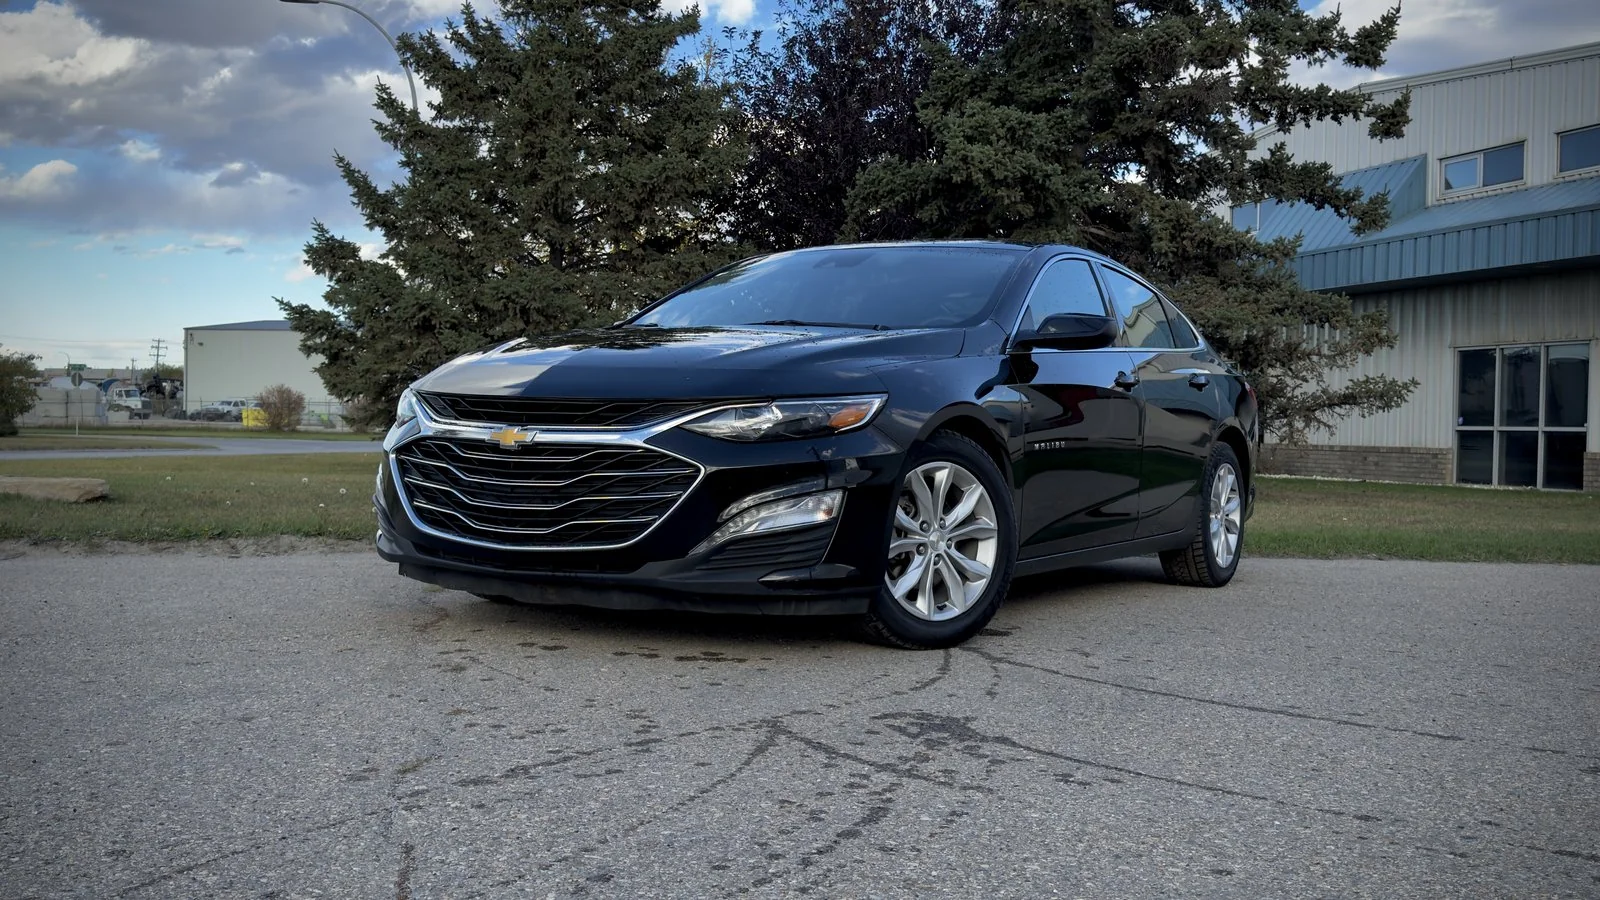
2025 Chevrolet Malibu 1LT
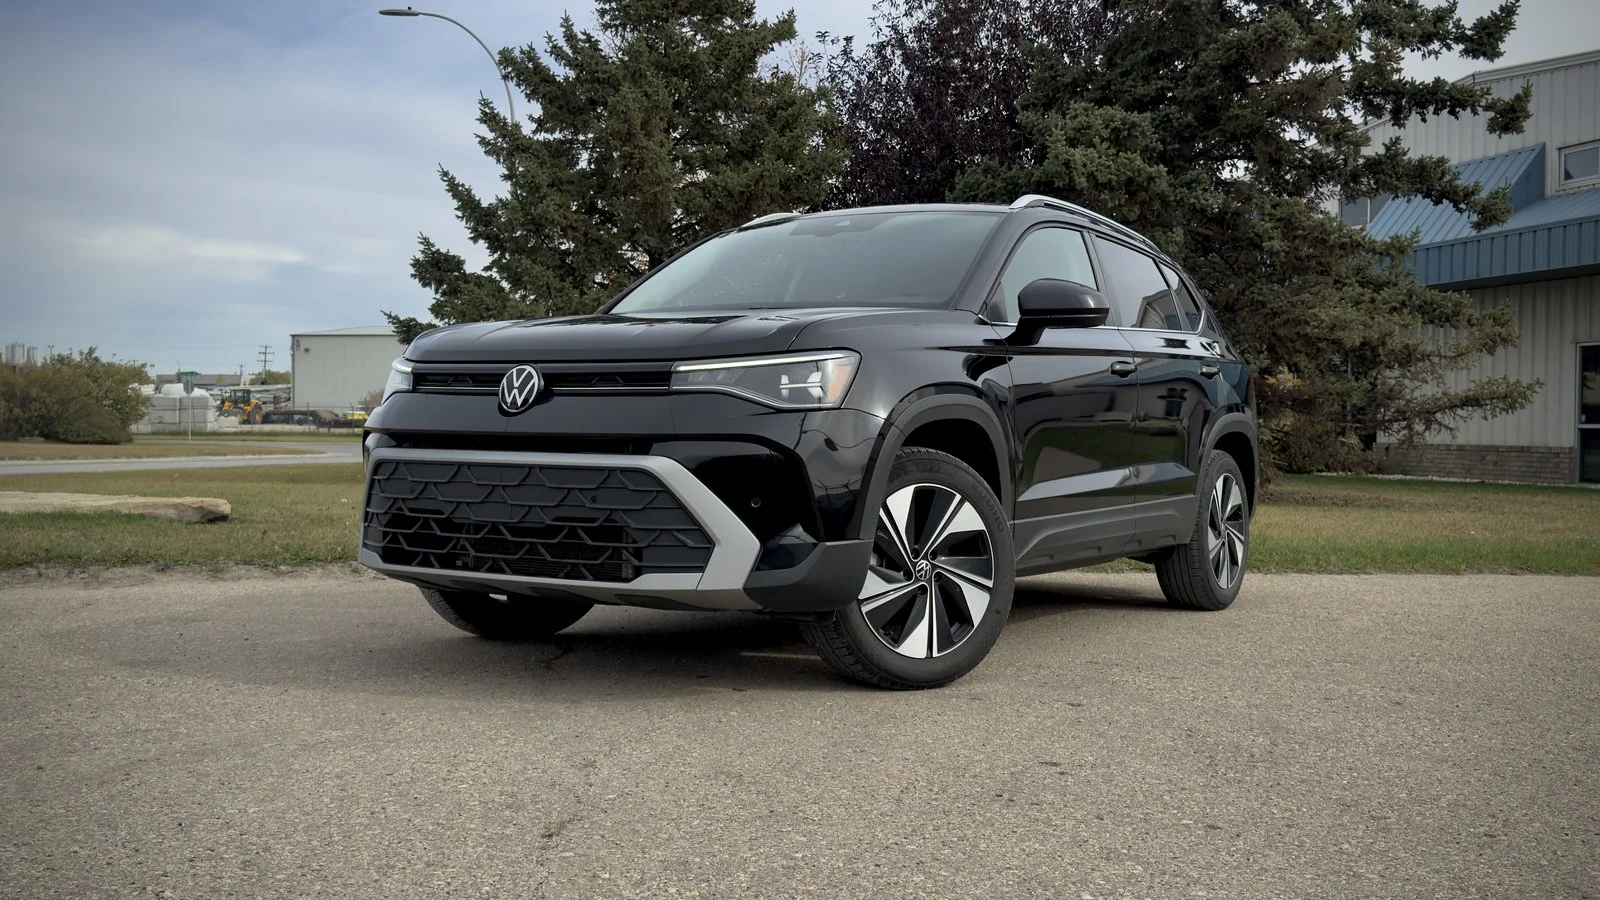
2025 Volkswagen Taos Comfortline
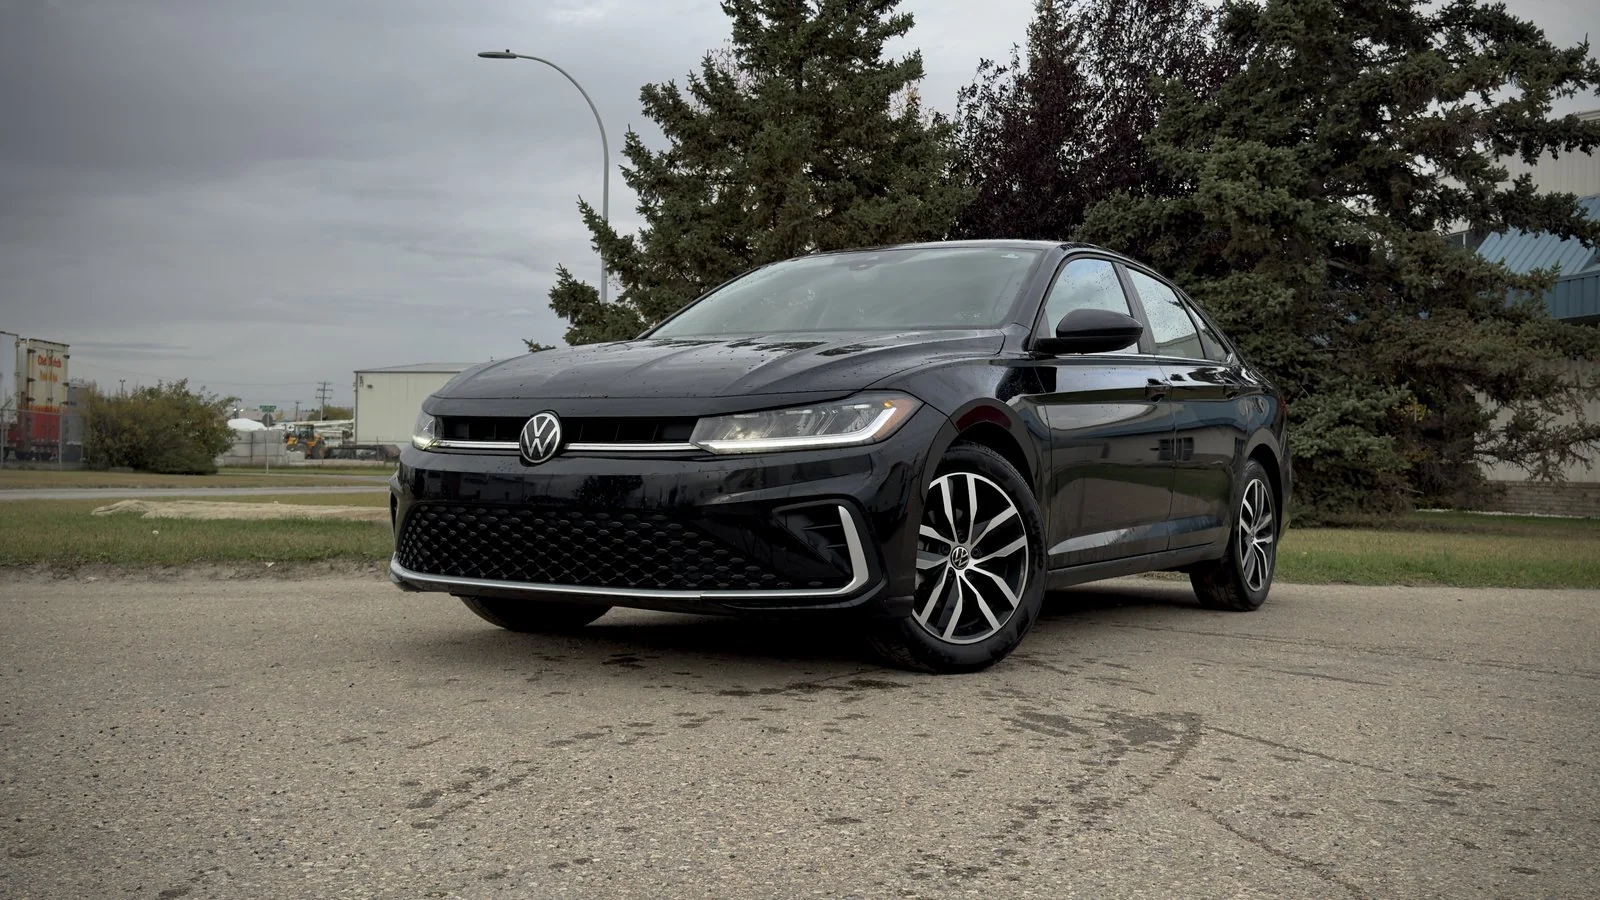
2026 Volkswagen Jetta Comfortline
Not seeing it? We'll find it.
We source through our dealer partner network across Western Canada: 25,000+ vehicles to choose from. Tell us what you want and what works for your budget.
Find my car3 min · no credit impactOAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Related Resources
What Our Customers Say
“Luke and Wes are a fantastic team! I purchased a Lincoln Corsair in pristine condition. They got me the best interest rate for my financing and even helped me find the best insurer.”
“Simply amazing! Finding an affordable car these days is almost impossible, but Shahdeen and Luke made the entire process so smooth and stress-free. Knowledgeable, honest, and no pressure.”
“The buying experience was handled very professionally. Wes was very attentive and presented everything in an open and honest manner that gave me the reassurance that I made a good purchase.”
Deeper on This Topic
Pick the angle that fits your exact situation.
See What Rate You Qualify For
Rates from 4.99% to 29.9% APR by credit tier. Check yours in 3 minutes.
5.0118+ Google ReviewsAMVIC LicensedFree Delivery 300km
Other Financing Options
Find Out What Rate You Would Qualify For
Every situation is unique. We specialize in tailored debt management solutions — reach out for a no-obligation consultation to find out what rate you would qualify for.
No obligation. No pressure. Just honest answers about your options.
Rates shown are typical ranges based on current lender programs and are not guaranteed. Your actual rate depends on individual circumstances including credit history, income, vehicle selection, loan term, and lender approval criteria. All financing is on approved credit (OAC). Shift Happens Auto Sales does not guarantee credit approval. Rate ranges are approximate and may change without notice.