Car Loan on Maternity Leave — Alberta
A new baby changes everything — including what you need in a vehicle. Whether you are still pregnant, fresh home from the hospital, or halfway through an 18-month extended leave, we work with all credit situations. EI benefits can count as income, and we will tell you honestly what could work.
Last reviewed: October 2026
What lenders typically need
EI maternity and parental benefits can count as income, and so can any employer top-up you can document. Lenders also look at how long your leave runs, your return-to-work date and your partner's income.
In our experience, lenders typically look for about $2,800 a month in income you can prove, from all sources combined. Benefits like AISH, ADAP, CPP Disability, EI and the Canada Child Benefit can count toward that alongside work or support income. Every lender decides each file. If you're under that, talk to us first — a co-applicant, a larger down payment or a few months of income history can change the picture.
Where to go from here
Key Facts
- EI benefits
- Can count as income
- Employer top-up
- Can count too, with documentation
- Joint applications
- Partner can co-apply
- Typical target
- About $2,800/mo total income
- APR range
- 4.99%–29.9% APR
Timing tip: apply before leave if you can
Yes — You Can Get a Car Loan on Maternity Leave
The short answer is yes. Maternity and parental leave is a temporary, government-supported life stage — not a sign of financial instability. Lenders who understand this can finance strong applications from parents on leave.
The key is documentation and lender selection. Not every bank or credit union handles leave-income files well. The chartered banks tend to be rigid — they want to see regular payroll, and EI deposits can confuse their automated systems. But our network of 21+ lender partners includes B-lenders and alternative lenders who are experienced with exactly this situation.
We see new and expectant parents regularly. A file that is put together carefully, with the right income documents and lender match, gives you the best chance.
The vehicle purchase does not have to wait until you are back at the desk. If the timing is right now — because you are pregnant and your current car is too small, or because your newborn just arrived and you realized the sedan does not fit a stroller and groceries at the same time — we can help you move forward today.
How Lenders View Maternity Leave Income
When a lender looks at a file from someone on maternity or parental leave, they are assessing two things: your ability to make payments during the leave period, and your expected income when you return. Understanding this lens helps you present your file most effectively.
EI Maternity & Parental Benefits
Employment Insurance pays 55% of your average insurable weekly earnings, up to a maximum of $729 a week in 2026. This income is deposited regularly and is verifiable through your EI records. Many lenders can count it as income when it is supported by bank statements showing consistent deposits.
Employer Top-Up Programs
Many Alberta employers — particularly in government, healthcare, education, and large corporations — offer Supplemental Unemployment Benefit (SUB) plans that top up EI to 70%, 80%, or even 100% of your regular salary for a portion of your leave. If your employer has this program, document it in writing. A letter from HR stating your top-up amount and duration can increase the income a lender can count.
Canada Child Benefit (CCB)
The CCB is a tax-free monthly payment to eligible families with children under 18. After a birth, families with lower net household income often receive meaningful CCB amounts. Some lenders will include CCB as supplemental income — ask your finance specialist whether your CCB amount is worth including in the file.
Return-to-Work Confirmation
A letter from your employer confirming your job title, current salary, and expected return date is one of the most powerful documents you can add to a leave-income application. It tells the lender: this is a temporary situation, and this person has a stable career to return to. Lenders treat confirmed return-to-work files very differently from open-ended income uncertainty.
The combination of EI benefits + employer top-up + CCB + return-to-work letter creates a compelling income picture — often stronger than you might expect. Bring all of it and let our finance team decide what to include.
Canadian Maternity & Parental Leave: What You Are Entitled To
Canada has one of the most generous parental leave systems in the world. Understanding your entitlements helps you plan your vehicle purchase timing and income documentation.
Maternity Leave
- Up to 15 weeks of EI maternity benefits
- Available only to the birth parent
- Begins up to 12 weeks before the due date
- 55% of insurable earnings, max $729/week (2026)
Standard Parental Leave
- Up to 40 weeks (shared between parents)
- 55% of insurable earnings, max $729/week (2026)
- Must be taken within 52 weeks of birth or placement
- One parent can take up to 35 weeks
Extended Parental Leave
- Up to 69 weeks (shared between parents)
- 33% of insurable earnings, over a longer period
- Lower weekly benefit but stretched over more time
- Maximum combined leave: 18 months
Alberta Employment Standards
- 16 weeks of maternity job protection
- 62 weeks of parental job protection
- Your position is protected throughout
- Return-to-work rights are legally guaranteed
The length and structure of your leave matters to lenders. A parent 14 weeks into a 15-week maternity leave is in a very different position than a parent just starting an 18-month extended parental leave. Our finance team will discuss your specific timeline and tailor the application accordingly.
Joint Applications: Your Strongest Option
When one parent is on leave and the other is working full-time, a joint application is almost always the optimal approach. Here is why:
Combined Income Gives Lenders More to Work With
Lenders assess debt-to-income ratio. Adding a working partner's salary to your EI benefits can double or triple the qualifying income, which directly translates to a higher loan ceiling and more vehicle choices.
Best Credit Profile Gets Used
If your partner has a higher credit score, the lender may anchor the rate primarily to their profile. A joint application can move you from a higher-rate B-lender tier down to a more competitive rate — potentially saving thousands over the loan term.
Reduces Income Gap Risk
Lenders feel more comfortable knowing two people are responsible for the loan. If your EI runs out earlier than expected, or if return-to-work is delayed slightly, the working partner's income still covers the payment. This shared responsibility reduces perceived risk.
Both Names on the Asset
A joint loan puts both names on title — which is often the practical reality anyway for a family vehicle. It also means both partners benefit from on-time payments boosting their credit history simultaneously.
If your partner is not able or willing to co-apply, we can still work with your individual application. A solo application with strong EI documentation, a return-to-work letter, and a reasonable vehicle price can still work. We will tell you honestly what to expect.
What New Parents Actually Need in a Vehicle
The family vehicle suddenly means a lot more when there is a baby involved. These are the features our new-parent customers most consistently prioritize — and why we make sure our inventory includes vehicles that check these boxes.
Safety Ratings
Look for vehicles with five-star NHTSA or Top Safety Pick+ from IIHS. Side curtain airbags, electronic stability control, and automatic emergency braking are non-negotiable for many parents. Ask us about the safety ratings for any vehicle on our lot.
Car Seat Compatibility
Not all rear seats are created equal. Rear-facing infant seats need meaningful legroom in front; convertible seats need clearance to the roof. Larger crossovers and SUVs typically offer more flexibility. We can help you test-fit a seat before you buy.
Cargo Space
A stroller, diaper bag, groceries, and a gear bag for an activity add up fast. You will want at least 25–30 cubic feet of cargo space with the rear seats in use. Minivans and mid-size SUVs lead this category.
Reliability
An unexpected breakdown with an infant in -30°C Alberta weather is a situation no one wants. Japanese brands like Toyota and Honda consistently top reliability surveys. Our inventory is vetted — no rust buckets, no hidden problems.
Easy Entry & Exit
Loading a sleeping baby into a car seat without waking them is a skill. Wider door openings, lower step-in heights (for postpartum recovery), and powered sliding doors on minivans make the daily routine much easier.
Backup Camera & Sensors
All 2018 and newer vehicles sold in Canada require backup cameras. Rear parking sensors and cross-traffic alerts add an extra layer of confidence when backing out with a distracted or tired mind — a common state for new parents.
Popular choices we see our new-parent customers driving away in: Toyota RAV4, Honda CR-V, Dodge Grand Caravan, Chrysler Pacifica, Kia Telluride, Hyundai Tucson, Ford Explorer, and Toyota Sienna. Browse our current inventory and tell us what you are looking for — we will point you to the right options.
Tips for Applying While on Leave
Here is what usually separates the files that go smoothly from the ones that stall.
Get a Return-to-Work Letter
Ask your employer for a short letter on company letterhead confirming: your position, your current salary, and your expected return date. This single document changes how lenders frame your file. It converts “temporary income reduction” into “confirmed career continuity.”
Print Your MyEI Benefit Statement
Log into My Service Canada Account and print your current EI benefit details — weekly amount, weeks remaining, and projected end date. This is cleaner evidence than explaining the benefit verbally.
Collect 3 Months of Bank Statements
Lenders want to see the EI deposits landing consistently. Three months of statements showing regular government deposits establish a reliable payment pattern. If your employer top-up also deposits separately, include those statements too.
Keep the Vehicle Price Reasonable for Your Current Income
Lenders look at the payment against your current leave income, not your expected return income. A smaller payment you can keep up with beats a stretch. We will help you find a vehicle where the numbers work comfortably right now.
Consider a Down Payment
A larger down payment reduces the lender's risk and your monthly payment. It can help a borderline file, and we will tell you what amount might make a difference.
Include Your Partner on the Application
If your partner is employed, a joint application almost always produces a better outcome than applying solo during leave. The combined income, better debt ratios, and shared credit history typically unlock a lower rate and higher loan amount.
Frequently Asked Questions
Can I get a car loan while on maternity or parental leave in Canada?
Often, yes. EI maternity and parental benefits can count as income, along with any employer top-up you can document. Lenders also look at your return-to-work date and your partner's income. In our experience, about $2,800 a month in total proven income is where files tend to work. Every lender decides each file.
Does EI maternity pay count as income for a car loan?
It can. Standard EI pays 55% of insurable earnings, up to $729 a week in 2026. Extended parental benefits pay a lower percentage over a longer time. Your award letter shows your weekly amount and end date. Lenders add it to any top-up, and to your partner's income on a joint application.
What if my income on leave is under that amount?
Talk to us before you apply. A co-applicant with steady income, a larger down payment or a few months of income history can change the picture. We would rather give you a straight answer by phone than have you apply and collect a credit inquiry for nothing.
What documents do I need on maternity leave?
Usually your EI award letter showing the weekly amount and end date, three months of bank statements, your most recent Notice of Assessment, government ID and proof of address. Add an employer top-up letter and a return-to-work letter if you have them. We review every application and call you back.
Should I apply before leave starts or during it?
If your leave has not started, your regular pay is still on file, which can give you more options. If you are already on leave, you can still apply with your award letter, any top-up and your return-to-work letter. Timing is your call, and we will not push you either way.
Can my partner be a joint applicant on the car loan?
Yes. A joint application with a partner who has steady income gives lenders more to work with, and your leave income adds to it. Both of you will have your credit checked. We will tell you honestly whether applying jointly looks stronger than applying alone.
What vehicles work best for new parents?
Think safety ratings, room for a car seat and low running costs. A reliable used SUV or sedan with service records is a common fit. On leave income, a smaller payment you can keep up with matters more than the biggest vehicle. Tell us your budget and we will show what fits.
Sources (checked October 2026): Government of Canada — EI regular benefits: how much you could receive. Benefit amounts change; your own letter shows your real amount.
Related Resources
What Our Customers Say
“The truck is gorgeous and it's exactly what they said it was. I recommend to anyone.”
“Great experience with the team at Shift. The whole experience was easy from start to finish. Wes was quick to respond and answer all my questions. Luke was a dream with the paperwork.”
“Working with Shift Happens was a great experience. Dima and Luke were both professional, friendly, and always quick to respond. They made the process simple and stress-free.”
Cars you could drive home
See all inventory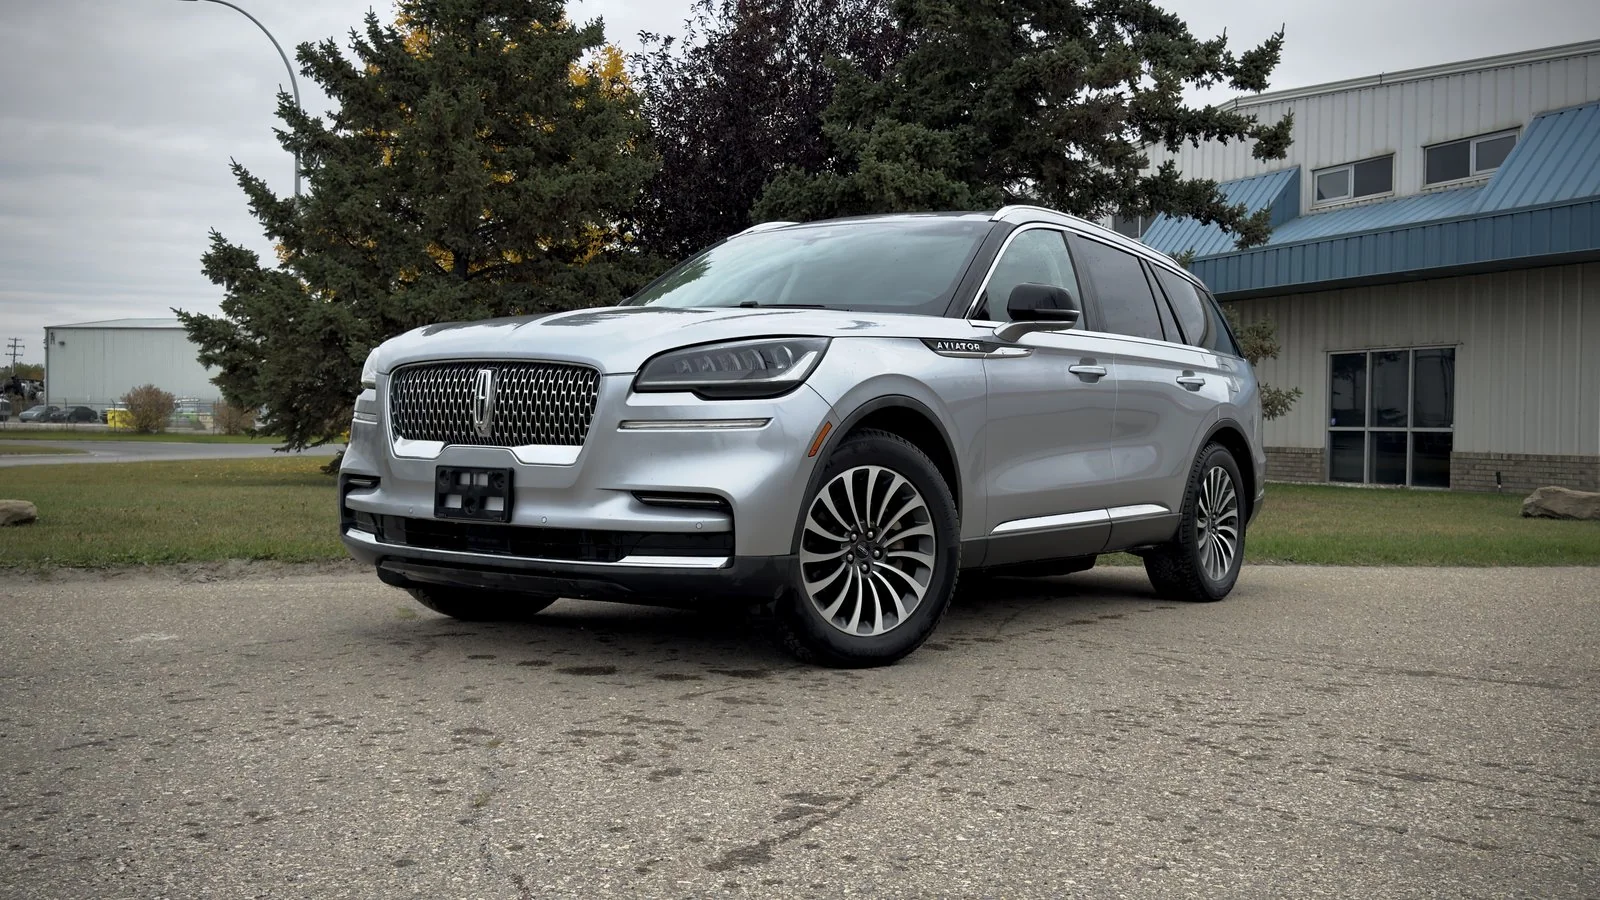
2022 Lincoln Aviator Reserve
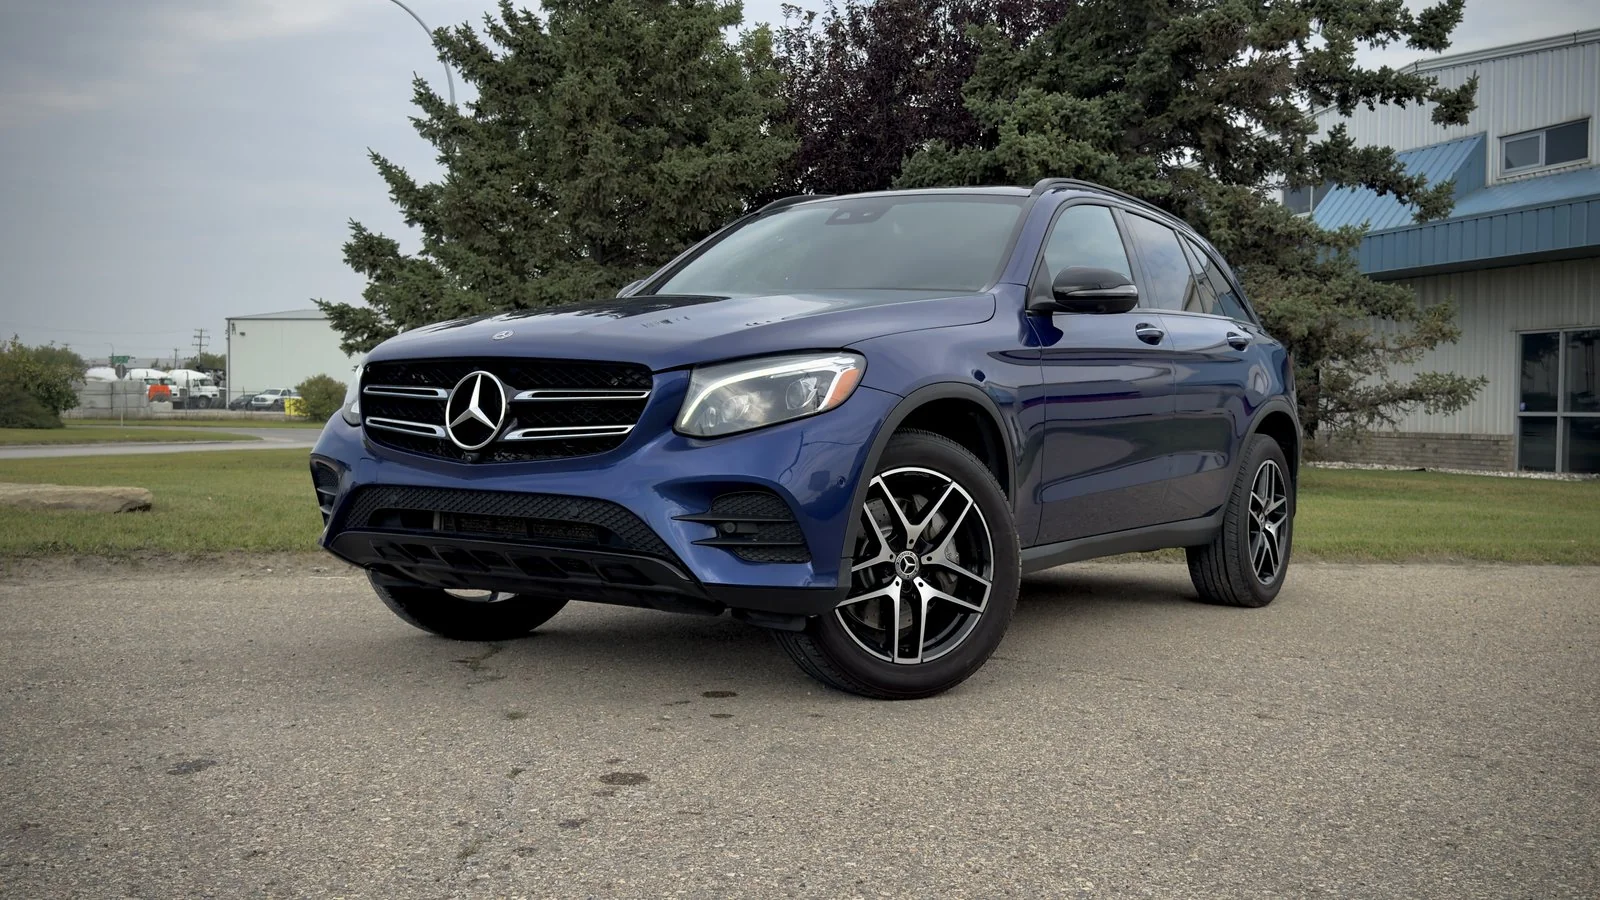
2019 Mercedes-Benz GLC-Class GLC300
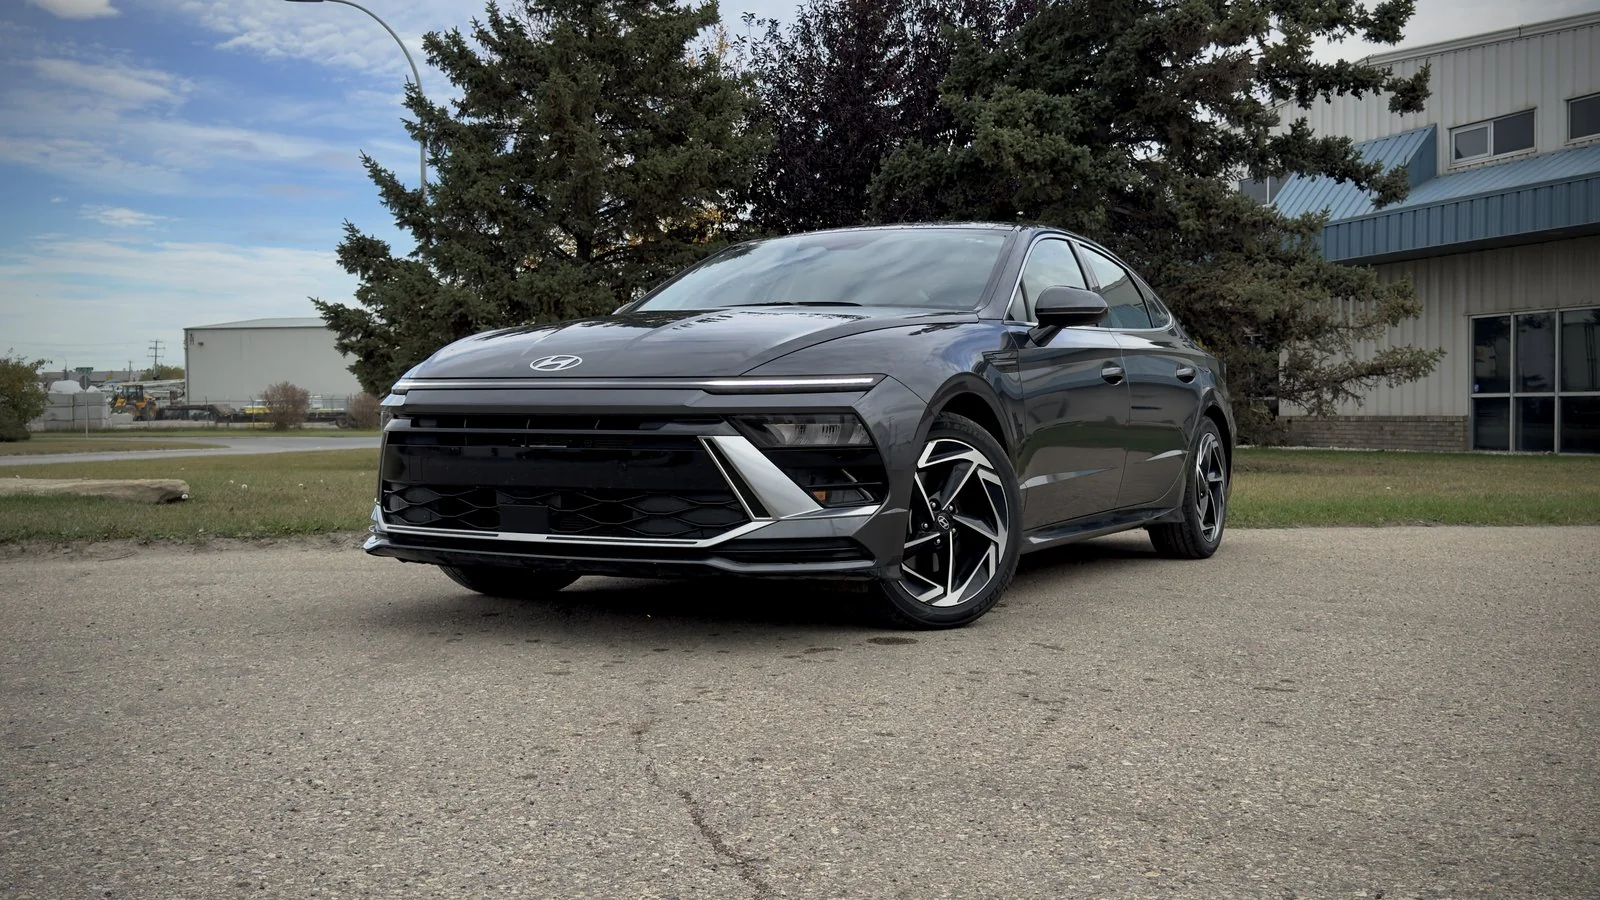
2025 Hyundai Sonata Preferred w/ Trend
2026 Nissan Kicks S
Not seeing it? We'll find it.
We source through our dealer partner network across Western Canada: 25,000+ vehicles to choose from. Tell us what you want and what works for your budget.
Find my car3 min · no credit impactOAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Where to go from here
Other Financing Options
Ready to Find the Right Family Vehicle?
New babies bring new needs. Whether you need more room for a stroller, better safety ratings, or just a reliable vehicle that starts every morning in Alberta winter — we are here to help. Apply online in 3 minutes or give us a call.