Car Loan on Employment Insurance
Between jobs and need a vehicle to get back to work? You are not alone. EI is real income — and with the right approach, real options exist. We work with all credit situations, including Albertans currently on EI, and we will tell you honestly whether applying now makes sense.
Last reviewed: October 2026
What lenders typically need
EI can count as income, but it ends, so lenders look hard at how many weeks you have left. In our experience EI alone is the hardest case; EI plus a working partner, a return-to-work date or other income is a much stronger file.
In our experience, lenders typically look for about $2,800 a month in income you can prove, from all sources combined. Benefits like AISH, ADAP, CPP Disability, EI and the Canada Child Benefit can count toward that alongside work or support income. Every lender decides each file. If you're under that, talk to us first — a co-applicant, a larger down payment or a few months of income history can change the picture.
Where to go from here
Honest Expectations for EI Car Loan Applicants
We will not oversell what is possible on EI-only income — but we will not undersell it either. Here is the honest picture so you can make an informed decision about whether to apply now or wait.
EI-Only Income: Harder, but Not Impossible
If EI is your only income source and your credit is challenged, it is difficult but not impossible — it depends heavily on the amount of your EI benefit and the vehicle you are trying to finance. A modest vehicle with a low monthly payment financed through a lender comfortable with EI income is more achievable than a high-value vehicle with a large payment. We will tell you honestly what is realistic for your specific income number.
Expect Higher Rates Than Employed Borrowers
EI applicants — even those with good credit — will typically see higher interest rates than borrowers with stable employment income. This reflects the perceived risk of a temporary income source. Our rates run 4.99%–29.9% APR — EI applicants generally land in the middle to upper part of that range, depending on their overall profile. The silver lining: after 12 to 24 months of consistent payments and a return to employment, refinancing to a lower rate is a realistic path forward.
Waiting May Be Worth It in Some Cases
If your EI benefit is low, your credit is challenged, and you have no supplemental income or joint applicant, it is possible that no lender will finance the file — and applying creates credit inquiries without benefit. In that case, the honest advice is to wait until you return to work and then apply. We would rather tell you that upfront than have you submit an application that goes nowhere. Call us before applying and we can give you a realistic read on your odds.
When Applying Now Is Clearly the Right Move
If you have a joint applicant with employment income, a decent credit history, and a reasonable vehicle budget — apply now. The case is straightforward and the upside (getting back to work faster) is real. Similarly, if your EI benefit is close to the maximum, you have supplemental income from the CCB or part-time work, and your credit is clean, your chances are meaningfully better than you might think. Do not wait when the application is genuinely strong.
Key Facts
- EI maximum benefit (2026)
- $729/week — some lenders count it as income
- Strongest strategy
- Joint application with a working partner
- Typical target
- About $2,800/mo total income
- APR range
- 4.99%–29.9% APR, depending on your profile
- Credit
- We work with all credit situations
The EI catch-22 — and how to break it
The EI Catch-22: You Need a Car to Get Back to Work
The frustrating reality of job searching in Alberta is that most well-paying positions require reliable transportation — and most lenders want employment income before approving a loan. You are not wrong to feel stuck. But that loop is not unbreakable, and thousands of Albertans navigate it every year.
Think about what having a vehicle actually changes when you are on EI: the radius of jobs you can realistically interview for expands from a walkable transit corridor to all of Calgary, Airdrie, or wherever the work is. Shift workers in construction, oil and gas, healthcare, and trades almost universally need their own transportation. Without a vehicle, the pool of available positions is dramatically smaller — and it stays smaller until you have wheels. This is not a small detail. It is often the single biggest practical barrier between EI and employment.
Why Lenders Hesitate with EI Income
EI is temporary by definition. A lender approving a 60-month loan wants to see income that will last 60 months. EI typically runs 14 to 45 weeks depending on your region, previous hours worked, and the unemployment rate in your area. That gap between loan term and income duration is the core concern. It does not mean EI disqualifies you — it means lenders need to see a credible path forward, which is where supplemental income and joint applications become so important.
What "Credible Path Forward" Actually Means
Lenders think in probabilities. If your EI application is accompanied by a spouse's full-time income, a clean credit history, and a reasonable vehicle choice, the probability that you will meet your payments is high enough to approve. If your application is EI income only, thin credit, and a request for the maximum loan amount, the math does not work regardless of how confident you are in your job prospects. The goal is to present the strongest honest picture of your situation — not to hide the EI, but to show it in full context.
The Faster You Get to Work, the Easier Payments Become
Here is the practical argument for acting now rather than waiting: every week you remain on EI without a vehicle narrows your job options and extends the EI period. Getting into a reliable vehicle — even if the rate is higher than you'd like — can shorten your unemployment period significantly, making the loan more than pay for itself in recovered income. We have seen this play out repeatedly. Clients who stretched for a practical vehicle early got back to full-time work faster and refinanced to a better rate within 12 to 18 months.
Choosing the Right Vehicle for Your EI Situation
When income is tight, vehicle choice matters more than usual. Reliable over impressive. Lower payments over newer. The vehicles that make the most sense when you are on EI are the ones with the lowest total cost of ownership: strong reliability records, low fuel consumption, and payments that remain comfortable at EI income levels. A Toyota Corolla, Honda Civic, Hyundai Elantra, or similar compact with a clean maintenance history is worth far more to you right now than a premium vehicle with a payment that only works if everything goes perfectly. We will help you find the vehicle that makes financial sense for where you are right now — not where you were.
Does EI Count as Income for a Car Loan in Alberta?
Some lenders in our network can count Employment Insurance as income, but not all of them, and not automatically. The key variables are how much EI you receive, how much supplemental income you have, your credit history, and how long your claim is expected to run.
EI is government-issued and arrives on a predictable schedule, which are two things lenders value. The complication is its temporary nature. Here is how lenders actually think about it — and what you can do to strengthen your position.
Alberta EI Rates and How They Are Calculated
EI pays 55% of your average insurable weekly earnings, up to a maximum insurable amount of $68,900 a year in 2026. That works out to a maximum of $729 a week. Most people receive less than the maximum, depending on their earlier wages. Your rate is calculated from your last 14 to 52 weeks of work, depending on the regional unemployment rate where you live. Your EI claim confirmation shows your real weekly amount and end date, and that is what lenders look at.
How Long Does EI Last in Alberta?
EI duration in Alberta typically ranges from 14 to 45 weeks depending on your region's unemployment rate and your insurable hours. Calgary and Airdrie fall under the Calgary economic region, which has historically had unemployment rates around 6 to 8 percent — placing most claimants in the 14 to 28 week range at standard benefit durations. If your claim will run longer than expected, that documentation helps with a lender application. Bring your EI benefit statement from My Service Canada Account, which shows your weekly amount and estimated end date.
Which Lenders Count EI Income?
Not all 21+ lenders in our network count EI as income on its own. Subprime and alternative lenders are more likely to consider it than prime lenders. The subset who do accept EI typically require it to be supplemented by at least one other recurring income source — a spouse's employment income being the most common. We match your application to lenders based on your specific profile, so you are not applying blind and accumulating unnecessary credit inquiries. One application, we do the matching.
Verifying EI Income for a Lender
Lenders need to see the income in your bank statements, not just your word for it. Three consecutive months of bank statements showing regular Service Canada deposits are the standard documentation. You will also want your EI Benefit Statement from My Service Canada Account, which shows the weekly amount and estimated end date of your claim. Your Record of Employment (ROE) from your previous employer confirms your employment history and is often requested alongside the EI documentation.
Supplemental Income That Helps You Qualify
EI combined with one or more supplemental income sources can improve your options a lot. Lenders who would decline an EI-only application will often finance one where EI is a component of a larger, verifiable household income picture.
Here are the supplemental sources most relevant to Albertans on EI, and how each one is treated by lenders.
Spouse or Partner's Employment Income
This is the most impactful supplemental source and the most common path for EI applicants. A joint application uses both incomes and both credit histories. If your partner is working full-time, their income is stable and verifiable — exactly what the lender needs to offset the temporary nature of EI. The combined household income changes the entire underwriting picture. If this option is available to you, it should be your first strategy.
Canada Child Benefit (CCB)
If you have children, the CCB provides up to $8,157 a year per child under 6 and $6,883 a year per child aged 6 to 17 (July 2026 to June 2027), reduced as family income rises. Paid monthly and government-issued, the CCB can count as income with many lenders. Combined with EI, it can meaningfully improve your total monthly income figure. Bring your most recent CCB notice or three months of bank statements showing the monthly deposits.
Alberta Child and Family Benefit
This provincial supplement adds to the CCB for lower-income Alberta families, paid quarterly. Check the current amount with the Alberta government. While smaller than CCB, it contributes to the overall pattern of government income and can be included in your total income calculation when applying with a lender who accepts it.
Rental Income
If you own a property and receive rental income, this can be counted toward your qualifying income even while on EI. Lenders typically want to see a signed lease agreement and three months of rental deposits in your bank statements. Net rental income (after mortgage, taxes, and insurance) is what lenders count, not gross rental. If you rent out a basement suite or secondary unit, document it fully — it can shift a file from marginal to workable.
Part-Time or Contract Work While on EI
Many Albertans on EI do some part-time or contract work while looking for full-time employment. If you are earning income from part-time work alongside EI, you may be required to report it to Service Canada (EI rules allow you to earn up to a threshold before benefits are reduced). Verifiable part-time income strengthens your application — bring recent pay stubs or invoices. This is particularly relevant for trades workers, drivers, and skilled contractors who pick up side work between main-gig positions.
Canada Workers Benefit and Other Credits
The Canada Workers Benefit (CWB) helps eligible low-income workers. If you qualified for advance CWB payments during your working period, this shows in your bank history and supports your income picture. The GST/HST credit, while smaller, also represents consistent government deposits that lenders may include in a full income assessment. Every verified, recurring deposit strengthens your application.
Joint Applications: The Strongest Strategy on EI
A joint application with a working spouse or partner is the single most effective approach for someone on EI who needs a vehicle now. It is not a workaround — it is how household income is supposed to work, and lenders treat it exactly that way.
Understanding how joint applications work helps you set realistic expectations and present the strongest possible application to our lender network.
How a Joint Application Works
Both applicants are equally responsible for the loan. The lender combines both income sources and evaluates both credit histories. The vehicle is registered to both names. Both applicants share the legal obligation to make payments — this is not the same as a co-signer arrangement, where one person is primary and one is backup. A joint application is a full partnership on the loan. On-time payments build both credit profiles simultaneously.
When a Co-Signer Makes More Sense
A co-signer arrangement is different from a joint application. In a co-signer setup, you are the primary borrower and the co-signer guarantees the loan if you default. The vehicle is typically in your name only. This works when you have some income and reasonable credit, but need additional backing from someone with stronger credit or income. Co-signers take on real financial risk — if you miss payments, it damages their credit too. Choose this path carefully and have a frank conversation with the co-signer about what they are agreeing to.
What Happens to the Loan When You Return to Work
When your employment resumes, the loan does not change on its own — but your financial position improves significantly. After 12 to 24 months of on-time payments and with a stronger employment income on record, refinancing to a lower rate is a realistic option. Many clients who start with higher-rate financing during difficult periods refinance within one to two years and meaningfully reduce their total interest cost. This is the plan-ahead strategy worth knowing before you sign.
Protecting Both Credit Files
A joint application means both credit profiles are on the line. If you are on EI but have a clean credit history, and your partner has strong employment income, the combination is genuinely strong. If either profile has significant delinquencies, that affects the overall application. Be honest with us about both credit situations upfront — we can identify which lenders are the right fit rather than having you discover the mismatch after submitting.
Documentation You Need to Apply on EI
Have your EI statement, ROE, three months of bank statements, photo ID, and proof of address ready before you apply — it shortens the process significantly. If you have supplemental income, bring documentation for that too.
EI applications require a bit more documentation than standard employment income applications, because lenders need to verify the benefit amount and understand the claim timeline. Here is exactly what to gather.
EI Claim Documentation
Your EI Benefit Statement from My Service Canada Account (available at canada.ca/my-service-canada-account). This document shows your weekly benefit amount, claim start date, and estimated end date. Download and print or screenshot it before your application. This is the primary income verification document for EI income.
Record of Employment (ROE)
Your ROE from your previous employer shows your employment history, reason for separation, and insurable hours and earnings. Your employer is required to issue it within five days of your last day of work, and it goes directly to Service Canada electronically. You can access a copy through My Service Canada Account. Lenders use it to understand your work history and the circumstances that led to the EI claim.
Bank Statements (3 Months)
Three consecutive months of complete bank statements showing the EI deposits from Service Canada. These confirm that the income is actually landing in your account and allow lenders to see your overall cash flow pattern. If you have multiple income sources, the bank statements also verify those deposits alongside the EI.
Identification and Proof of Address
A valid government-issued photo ID (Alberta driver's licence or provincial ID card) and proof of your current Alberta address. A utility bill, bank statement, or government correspondence with your name and address from the last 60 days works for address verification.
Supplemental Income Documentation
If you have any of the following, bring documentation: a spouse's recent pay stubs (last two pay periods), your most recent Canada Child Benefit notice, a signed lease agreement for rental income, recent invoices or pay stubs for part-time work. Each additional verifiable income source strengthens your application and increases the pool of lenders who can work with your situation.
EI and Seasonal Work in Alberta's Economy
Alberta's economy is built on industries with predictable seasonal cycles. EI periods tied to these cycles are not a sign of financial instability — they are the normal rhythm of work in this province. Alberta-based subprime lenders who specialize in this market understand the difference between structural unemployment and seasonal layoff.
Oil Field Spring Breakup Shutdowns
Road bans during spring breakup temporarily halt heavy equipment access to well sites across northern and central Alberta. Oil field workers — drillers, service hands, equipment operators — often collect EI during this window knowing work resumes when roads firm up. Lenders familiar with the Alberta oil patch recognize this as seasonal income, not chronic unemployment.
Construction Winter Slowdowns
Outdoor construction in Alberta slows dramatically between November and March. Framing, site work, and civil construction often pause entirely in extreme cold. Many tradespeople in carpentry, concrete, and heavy civil have predictable EI periods every winter followed by strong spring re-employment. This cycle is well understood by Alberta's subprime lending community.
Hospitality Shoulder Seasons
Alberta's tourism and hospitality sector — particularly in Banff, Jasper, and Canmore — operates on distinct high and shoulder seasons. Staff hired for ski season or summer tourism may collect EI between seasons before returning to full employment. These are known patterns with predictable endpoints.
Agriculture Harvest-to-Winter Transition
Alberta's agricultural sector — grain, canola, livestock — generates intense seasonal employment during harvest and planting, followed by reduced winter hours. EI bridges the gap for many workers in rural Alberta between active seasons.
Alberta EI Rates for 2026
EI pays 55% of insurable earnings up to a maximum of $68,900 for 2026. The maximum weekly EI benefit for 2026 is $729. For seasonal workers, EI is often a large part of the yearly income picture, and some lenders will count it when it is documented.
Car Loan on EI: Frequently Asked Questions
Can I get a car loan while on Employment Insurance in Alberta?
Sometimes. EI can count as income, but it ends, so lenders look hard at how many weeks you have left. EI alone is the hardest case. EI plus a working partner, a return-to-work date or other income is a stronger file. Call us before you apply so we can give you a straight read.
How much does EI pay in Alberta in 2026?
EI pays 55% of your insurable earnings, up to a maximum of $729 a week in 2026. The maximum insurable earnings are $68,900 a year. Most people get less than the maximum. Your EI claim confirmation shows your actual weekly amount and end date, and that is what lenders look at.
What if my total income on EI is under what you usually see work?
Talk to us before you apply. In our experience, about $2,800 a month in total income is where files tend to work. A co-applicant with steady income, a larger down payment or a return-to-work date can change the picture. Every lender decides each file.
What other income helps me on EI?
Part-time work, a partner's income, rental income, the Canada Child Benefit and child support can all count when documented. Lenders add them together. A working co-applicant is often the strongest addition. Bring proof for each source so the total is clear.
Will a joint application with a working spouse help?
Often, yes. A partner with steady employment income gives lenders a stable base, and your EI adds to it. Both of you will have your credit checked. We will tell you honestly whether a joint application looks stronger than applying alone.
What documents do I need to apply on EI?
Usually your EI claim confirmation showing the weekly amount and end date, three months of bank statements, government photo ID and proof of address. Add pay stubs or a partner's documents if you have them. We review every application and call you back; we do not promise a result.
Should I wait until I'm back at work to apply?
Sometimes waiting is the honest answer. If EI is your only income, your credit is bruised and you have no co-applicant, applying can add a credit inquiry without getting you a loan. If you have a working co-applicant or a return-to-work date, applying now can make sense. Call us for a straight read.
Does being on EI affect my credit score?
No. Receiving EI does not change your credit score. Missed payments and high balances do. Each application creates a credit inquiry, so call us first if your income is thin. We work with all credit situations, and every lender decides each file.
Sources (checked October 2026): Government of Canada — EI regular benefits: how much you could receive, Canada Revenue Agency — How we calculate your CCB. Benefit amounts change; your own letter shows your real amount.
Related Resources
What Our Customers Say
“Thanks to Luke and his team. They were able to find me my dream car and have it delivered between cities. Easy to deal with and easy to work with.”
“Working with Shift Happens was a great experience. Dima and Luke were both professional, friendly, and always quick to respond. They made the process simple and stress-free.”
“Luke was fantastic with helping us get into a mini van, we are MORE than happy. I highly recommend anyone looking for a vehicle to go check out Shift Happens!”
Cars you could drive home
See all inventory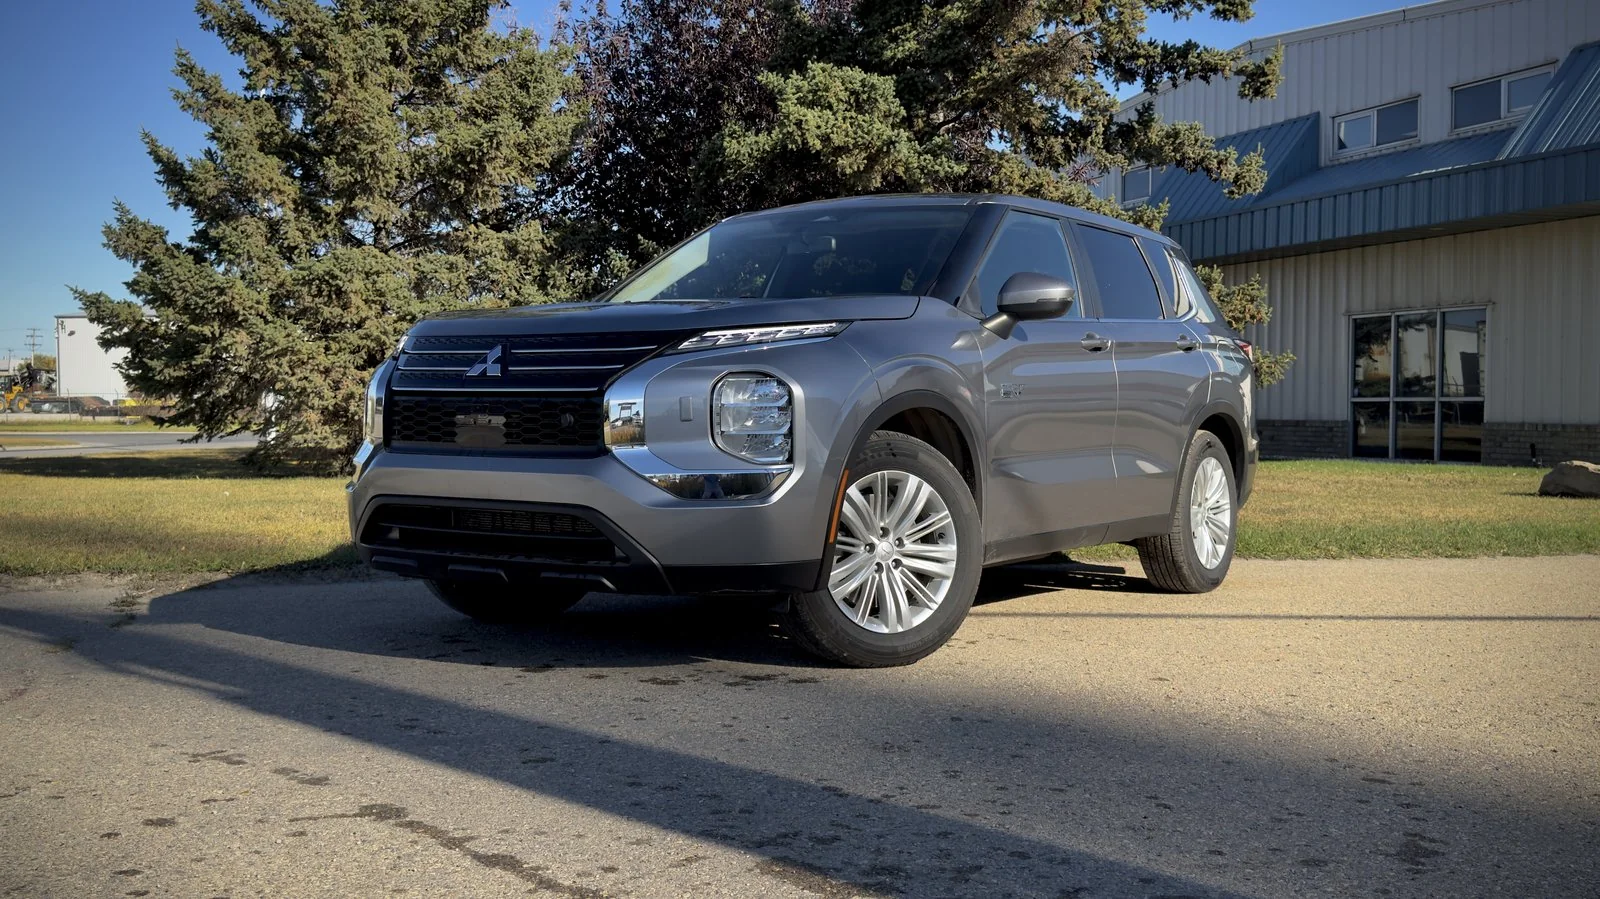
2023 Mitsubishi Outlander ES PHEV
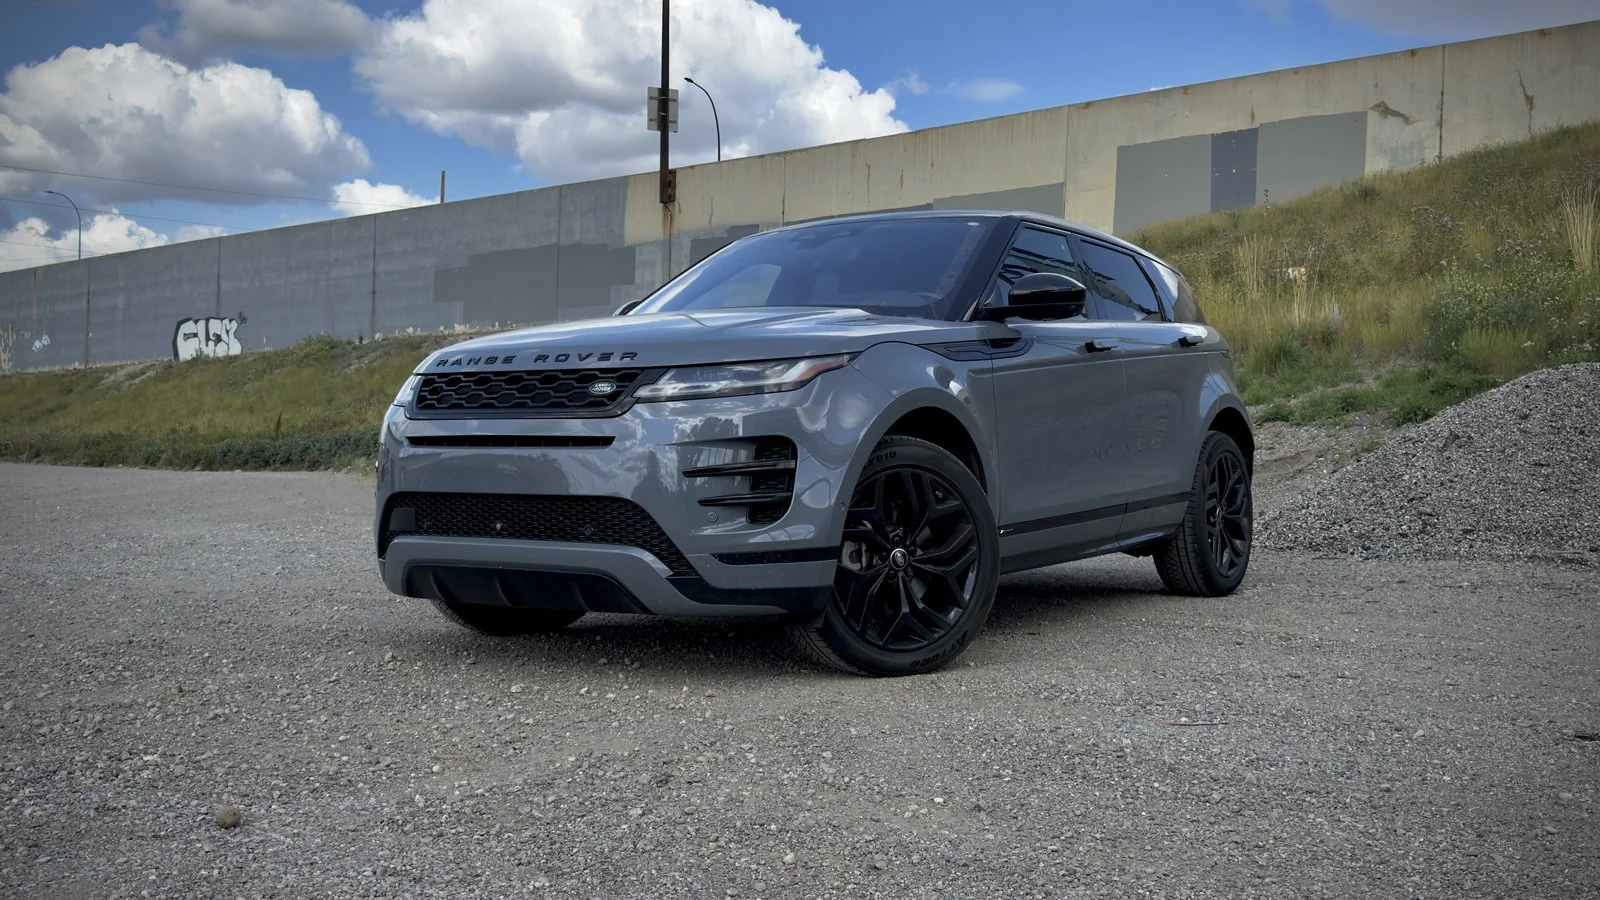
2021 Land Rover Range Rover Evoque R-Dynamic HSE
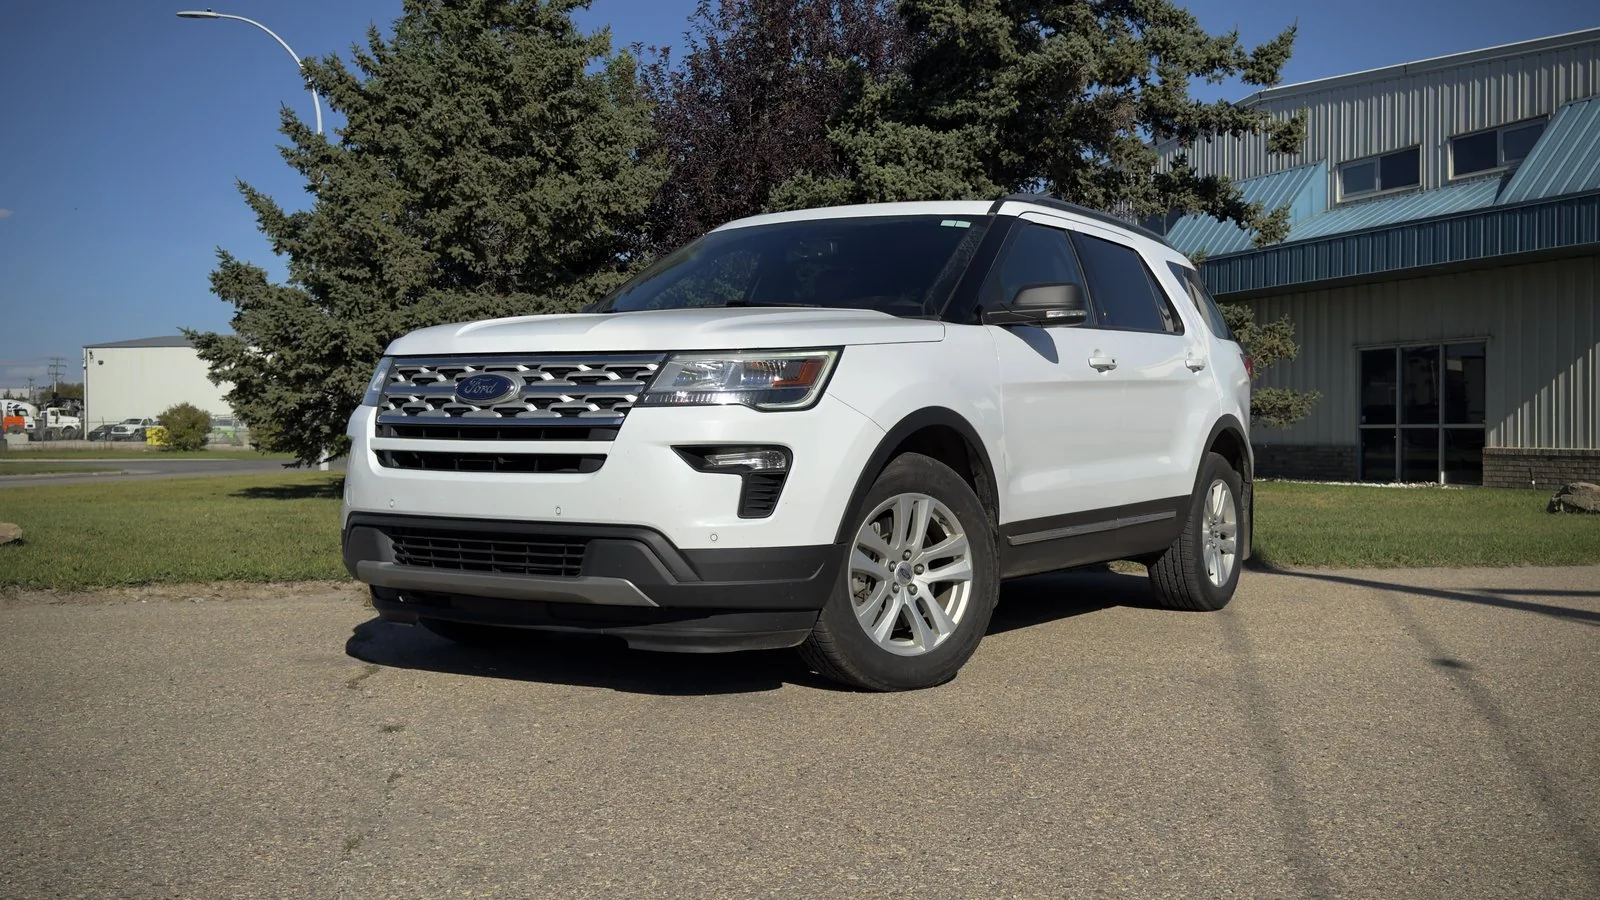
2019 Ford Explorer XLT
2020 GMC Terrain Denali
Not seeing it? We'll find it.
We source through our dealer partner network across Western Canada: 25,000+ vehicles to choose from. Tell us what you want and what works for your budget.
Find my car3 min · no credit impactOAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Where to go from here
Other Financing Options
Ready to Talk Through Your Options?
Apply online in 3 minutes or call us first if you want an honest read on your situation before submitting. We work with all credit situations and we will tell you the truth about what is possible on EI — no pressure, no false promises.
AMVIC licensed. No obligation. We work with all credit situations — including Albertans currently on EI.