How Much Car Can I Afford?
A practical guide to car affordability — from monthly payment math to total cost of ownership, built for real Alberta budgets.
Last reviewed: October 2026
Find out what you qualify for
Get matched with lenders based on your income and credit. 3-minute application.
5.0121+ Google ReviewsAMVIC LicensedFree Delivery 300km
Key Facts
- Payment rule of thumb
- 15% of gross monthly pay (pay before tax)
- Not a lender rule
- Every lender decides each file
- Loan terms
- 12–96 months available
- Down payment
- $0–$2,000+ typical range
The 15% Rule of Thumb: A Payment Near 15% of Gross Pay
Find Your Price Range
Your Budget Details
Example rate: 9.9% APR. Rates run from 4.99% APR (prime) to 29.9% APR (deep subprime).
Example Vehicle Price
$34,500
at 9.9% APR over 72 months with $2,000 down
Example, not an offer. Based on a payment of 15% of gross monthly pay, a rule of thumb and not a lender rule. Insurance, fuel and maintenance are extra. Every lender decides each file.
Ready to see what you qualify for?
Get a real answer — no obligation, no pressure.
Apply for FinancingThe 15% Rule of Thumb for Car Payments
A common rule of thumb: keep your monthly car payment near 15% of your gross monthly pay, which is your pay before tax. It is a guide, not a lender rule, and it applies whether you are buying a commuter or a truck. The logic is simple: a payment much above that can leave too little budget for emergencies, savings, and the rest of life. Every lender decides each file and looks at your other debts too.
Gross pay means before tax and deductions: the number on your contract or pay stub, not the deposit that lands in your bank account. If you are paid bi-weekly, multiply one before-tax paycheque by 26, then divide by 12, to get your monthly figure. The 15% is the loan payment alone; insurance, fuel and maintenance are extra costs on top (see total cost of ownership below).
| Monthly Gross Pay | Payment Near 15% | Example Loan, Prime Rate | Example Loan, Subprime Rate |
|---|---|---|---|
| $3,000/mo | $450 | $26,000 | $20,000 |
| $4,000/mo | $600 | $35,000 | $27,000 |
| $5,000/mo | $750 | $44,000 | $33,500 |
| $6,000/mo | $900 | $52,500 | $40,500 |
Example loans repay the payment shown over 72 months with $0 down, at the Prime example rate (6.9% APR) and the Subprime example rate (16.9% APR). Example, not an offer. Rates run from 4.99% APR (prime) to 29.9% APR (deep subprime); your rate depends on your file, and every lender decides each file.
Why your rate matters here
A $25,000 vehicle at the Prime example rate (6.9% APR) over 72 months costs ~$425/mo. The same vehicle at the Subprime example rate (16.9% APR) costs ~$555/mo, a $130/month difference. That gap is real, and it affects which price point you should target. On $3,000 a month of gross pay, a payment near 15% is $450 (a rule of thumb): that repays a loan of about $26,000 at the Prime example rate, but about $20,000 at the Subprime example rate, with $0 down. To see the loan size at your own pay and score, check how much car loan you can get approved for, by income and credit.
Example, not an offer. Payment examples assume 72 months with $0 down at the example rate named for each tier; actual payments depend on approved rate, term, and vehicle price. OAC.
Debt-to-Income Ratio: What Lenders Check
Lenders can also look at two ratios to judge your capacity to carry a new car payment: GDS and TDS. Your 15% rule of thumb is about the car payment alone. These ratios add up everything you owe each month against your gross pay, so they go beyond the car payment.
What counts as debt in the TDS calculation?
Everything with a monthly payment: car loan, credit cards (minimum payment), student loans, personal loans, mortgage or rent. Lenders add these up to calculate your total monthly debt obligations before evaluating your application.
How does a car payment fit into your ratio?
Say you earn $5,000/month gross, your rent is $1,500 and your existing debt payments total $300. That is a TDS of 36%. A new $450 car payment is 9% of gross pay, inside the 15% rule of thumb, but it lifts your TDS to 45%. That is why the rule of thumb is a starting point and each lender still decides each file. (Example numbers only.)
Lenders read ratios differently
There is no single limit. Lenders weigh these ratios differently, and some give more weight to steady income and time on the job. Each lender decides each file. That is one reason a dealer with several lender relationships can matter.
How to calculate your own DTI before applying
Add up all your monthly debt payments (minimum credit card payments, loan payments, rent or mortgage). Divide that total by your gross monthly income, which is your income before tax. Multiply by 100 to get your percentage. The lower the result, the more room a lender sees for a new payment. The 15% rule of thumb is about the car payment alone; this ratio covers everything you owe each month.
Down Payment Impact on Affordability
Every dollar of down payment directly reduces your monthly obligation — and can improve your approval odds. The table below shows the monthly payment difference on a $20,000 vehicle at the Subprime example rate (16.9% APR) over 72 months with varying down payments.
| Down Payment | Amount Financed | Monthly Payment |
|---|---|---|
| $0 | $20,000 | ~$444/mo |
| $1,000 | $19,000 | ~$422/mo |
| $2,000 | $18,000 | ~$399/mo |
| $3,000 | $17,000 | ~$377/mo |
A $3,000 down payment reduces your monthly payment by about $67/month and saves you roughly $1,790 in total interest over the 72-month term. More importantly, a down payment signals financial commitment to lenders, which can be the difference between a conditional approval and a clean one on a borderline file. Trying to keep the monthly number down? Here are cars with a low monthly payment and how they work.
You do not need to put money down to get approved. Many buyers in Alberta finance with $0 down, particularly on vehicles under $20,000. But if you have $1,000–$2,000 available, deploying it as a down payment is almost always the highest-return use of that capital in the context of a car purchase.
Payment examples assume the Subprime example rate (16.9% APR) over 72 months. Example, not an offer. Rates run from 4.99% APR (prime) to 29.9% APR (deep subprime); your rate depends on your file, and every lender decides each file. OAC.
Total Cost of Ownership Beyond the Payment
Your real monthly car cost is not your loan payment — it is your loan payment plus every recurring cost associated with that vehicle. The 15% rule of thumb covers the loan payment only, so these costs sit on top of it. Many buyers focus exclusively on the monthly payment and miss the full picture until their first insurance bill arrives. Vehicle choice has a significant effect on that bill — if insurance cost is a constraint, see which models are the cheapest to insure in Alberta.
| Cost Category | Typical Range (Alberta) | Notes |
|---|---|---|
| Insurance | $150–$300/mo | Higher for young drivers and recent claims |
| Fuel | $150–$250/mo | Varies by vehicle type and driving distance |
| Maintenance | $100–$150/mo | Oil changes, tires, brakes averaged monthly |
| Registration | $10–$20/mo | Alberta registration averaged over 12 months |
Real monthly budget example: $4,000/mo gross pay
On $4,000 a month of gross pay, a payment near 15% (a rule of thumb, not a lender rule) costs about $1,110 a month all-in once the other costs are added. Example numbers. Budget accordingly before committing to a payment range.
How Credit Score Affects What You Can Afford
Your credit score does not change what vehicle you want — it changes what that vehicle costs per month. On the same $25,000 vehicle, the Deep Subprime example rate costs about $247/month more than the Prime example rate. That gap is not small. It directly shapes which price tier fits the payment you are aiming for.
| Credit Tier | Score Range | Example Rate | Payment on $25,000 / 72mo |
|---|---|---|---|
| Prime | 750+ | 6.9% APR | ~$425/mo |
| Near-Prime | 650–749 | 9.9% APR | ~$462/mo |
| Subprime | 500–649 | 16.9% APR | ~$555/mo |
| Deep Subprime | 300–499 | 24.9% APR | ~$672/mo |
The gap between the Prime and Deep Subprime example rates on a $25,000 vehicle is about $247/month, or about $17,770 in additional interest over the 72-month loan. At a payment near 15% of $3,000 a month of gross pay ($450, a rule of thumb), that is why the loan the payment repays shrinks from about $26,000 at the Prime example rate to about $16,500 at the Deep Subprime example rate. If your credit took a hit, here's how in-house financing works.
The path out of subprime rates
Subprime rates are not permanent. After 12–24 months of on-time payments, many borrowers move up a full credit tier. At that point, refinancing at a lower rate is often possible — reducing both the monthly payment and total interest cost. The vehicle that gets you approved today is also the tool that builds the credit to get you a better rate tomorrow. We work with all credit situations and will show you exactly where you stand.
Payment examples assume $25,000 financed over 72 months with no down payment, at each tier's example rate. Example, not an offer. Rates run from 4.99% APR (prime) to 29.9% APR (deep subprime); your rate depends on your file, and every lender decides each file. OAC.
Frequently Asked Questions About Car Affordability
What percentage of my income should go to a car payment?
A common rule of thumb is a payment near 15% of your gross monthly pay, which is your pay before tax. It is a guide, not a lender rule: every lender decides each file and looks at your other debts too. On $4,000 a month before tax, 15% is a payment near $600. That is the loan payment alone. Insurance, fuel and maintenance are extra costs on top of it, so leave room for them over a 72–84 month term.
How much car can I afford on a $50,000 salary?
A $50,000 salary is about $4,167 a month before tax in gross pay. At 15% of that, as a rule of thumb, the payment is near $625 a month. Over 72 months with $0 down, that payment repays a loan of about $36,500 at the Prime example rate (6.9% APR), or about $28,000 at the Subprime example rate (16.9% APR). Higher rates repay a smaller loan for the same payment. Example, not an offer.
Does a larger down payment help me afford more car?
Yes. A larger down payment reduces the amount financed, which lowers your monthly payment directly, and it may help with the lender's view of your file. On a $20,000 vehicle at the Subprime example rate (16.9% APR) over 72 months, $2,000 down instead of $0 lowers the payment by about $44 a month. Every dollar of down payment is a dollar that does not accumulate interest. Example, not an offer.
What about insurance costs in Alberta?
Alberta has some of the highest auto insurance premiums in Canada. Budget $150–$300 per month for full coverage, depending on your vehicle, driving record and age. Young drivers (under 25) and those with recent at-fault claims or lapses in coverage pay at the high end. Insurance is on top of the payment, not part of the 15% rule of thumb: a $600 payment plus $250 insurance is $850 a month, not $600.
Can I afford a truck on a modest income?
Often, with the right vehicle choice. A brand-new truck is a stretch on a modest income, but older-model trucks cost much less. On $5,000 a month of gross pay, a payment near $750 (15%, a rule of thumb) repays a loan of about $33,500 at the Subprime example rate (16.9% APR), or about $40,500 at the Near-Prime example rate (9.9% APR), over 72 months with $0 down. The key is targeting the right price point, not the right brand. Example, not an offer.
Should I choose a longer loan term to lower my payments?
Longer terms lower your monthly cost but increase the total interest paid over the life of the loan. A $20,000 loan at the Subprime example rate (16.9% APR, $0 down) costs about $7,650 in interest over 48 months and about $14,240 over 84 months. A middle term such as 72 months is often a balance: the monthly payment stays manageable while total interest stays reasonable. Going beyond 84 months rarely makes sense unless you are certain the vehicle will last the full term. Example, not an offer.
What Our Customers Say
“A huge thank you to Wes and Luke for making my vehicle purchase such a great experience. This has been the best experience I've had at a dealership. They were patient, kind, and attentive.”
“Thanks to Luke and his team. They were able to find me my dream car and have it delivered between cities. Easy to deal with and easy to work with.”
“Excellent service, very happy with my ride, thank you Luke and Wes!”
Cars you could drive home
See all inventory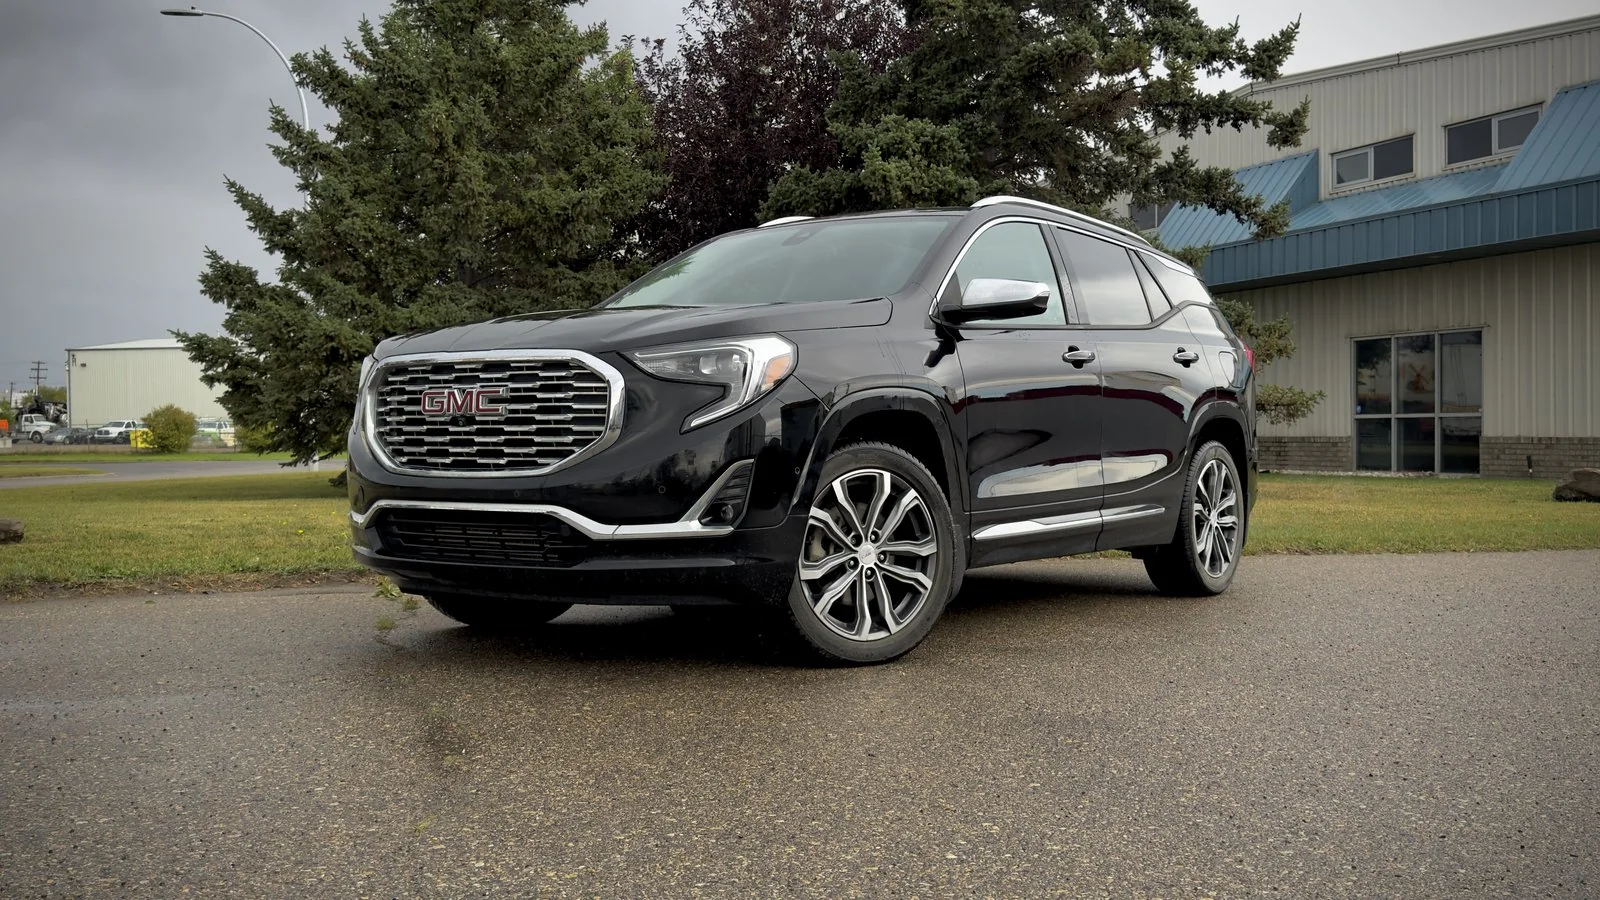
2020 GMC Terrain Denali
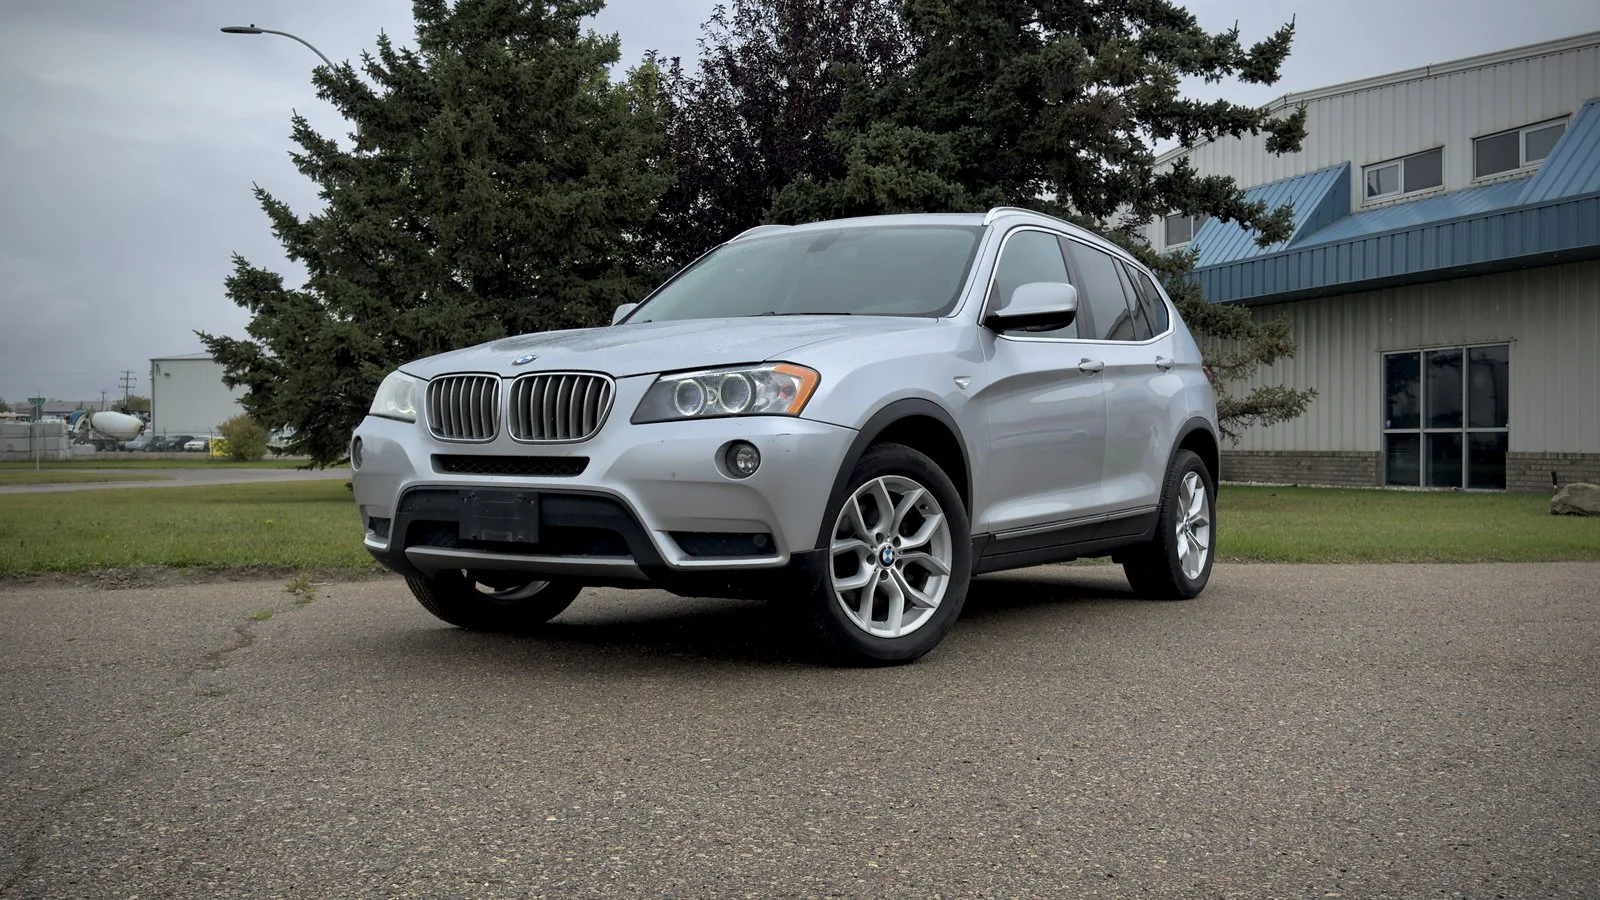
2014 BMW X3 xDrive28i
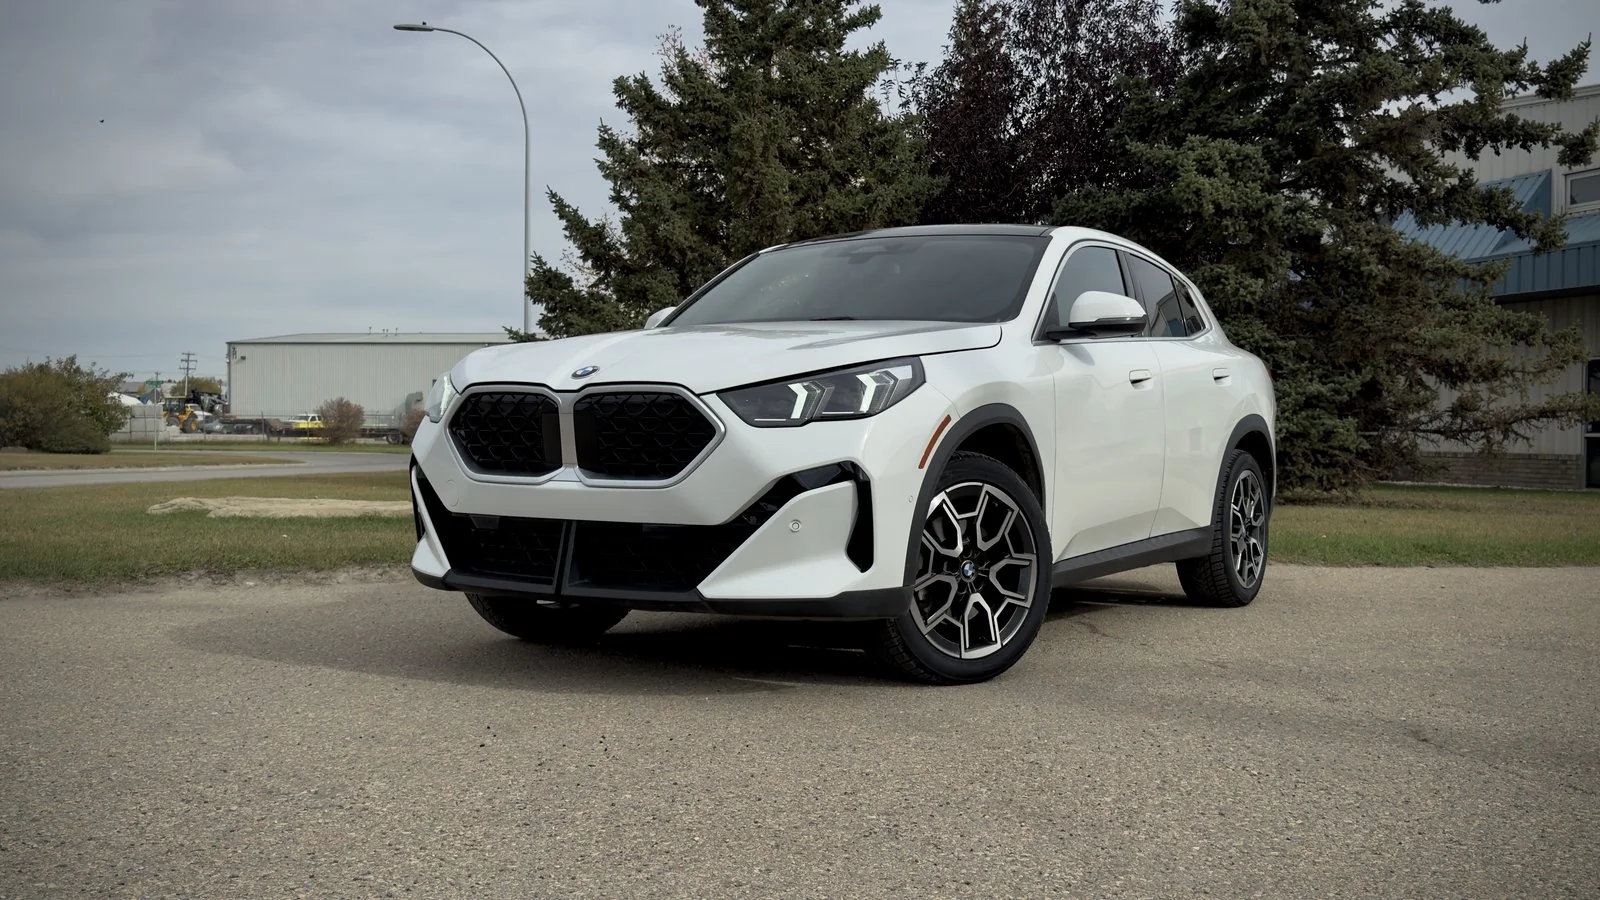
2025 BMW X2 xDrive28i
Not seeing it? We'll find it.
We source through our dealer partner network across Western Canada: 25,000+ vehicles to choose from. Tell us what you want and what works for your budget.
Find my car3 min · no credit impactOAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Find out what you qualify for
Get matched with lenders based on your income and credit. 3-minute application.
5.0121+ Google ReviewsAMVIC LicensedFree Delivery 300km
Related Resources
Ready to Find Out What You Qualify For?
We work with all credit situations — from prime to deep subprime. Apply for a no-obligation consultation and see what payment range fits your pay. Every lender decides each file.
No obligation. No pressure. Just honest answers about what fits your budget.
Payment examples and affordability ranges shown on this page are for illustration purposes only and are not guaranteed. Your actual payment, rate, and approved amount depend on your individual credit profile, income, vehicle selection, loan term, and lender approval criteria. All financing is on approved credit (OAC). Shift Happens Auto Sales does not guarantee credit approval or specific rates. Rate ranges are approximate and may change without notice.