
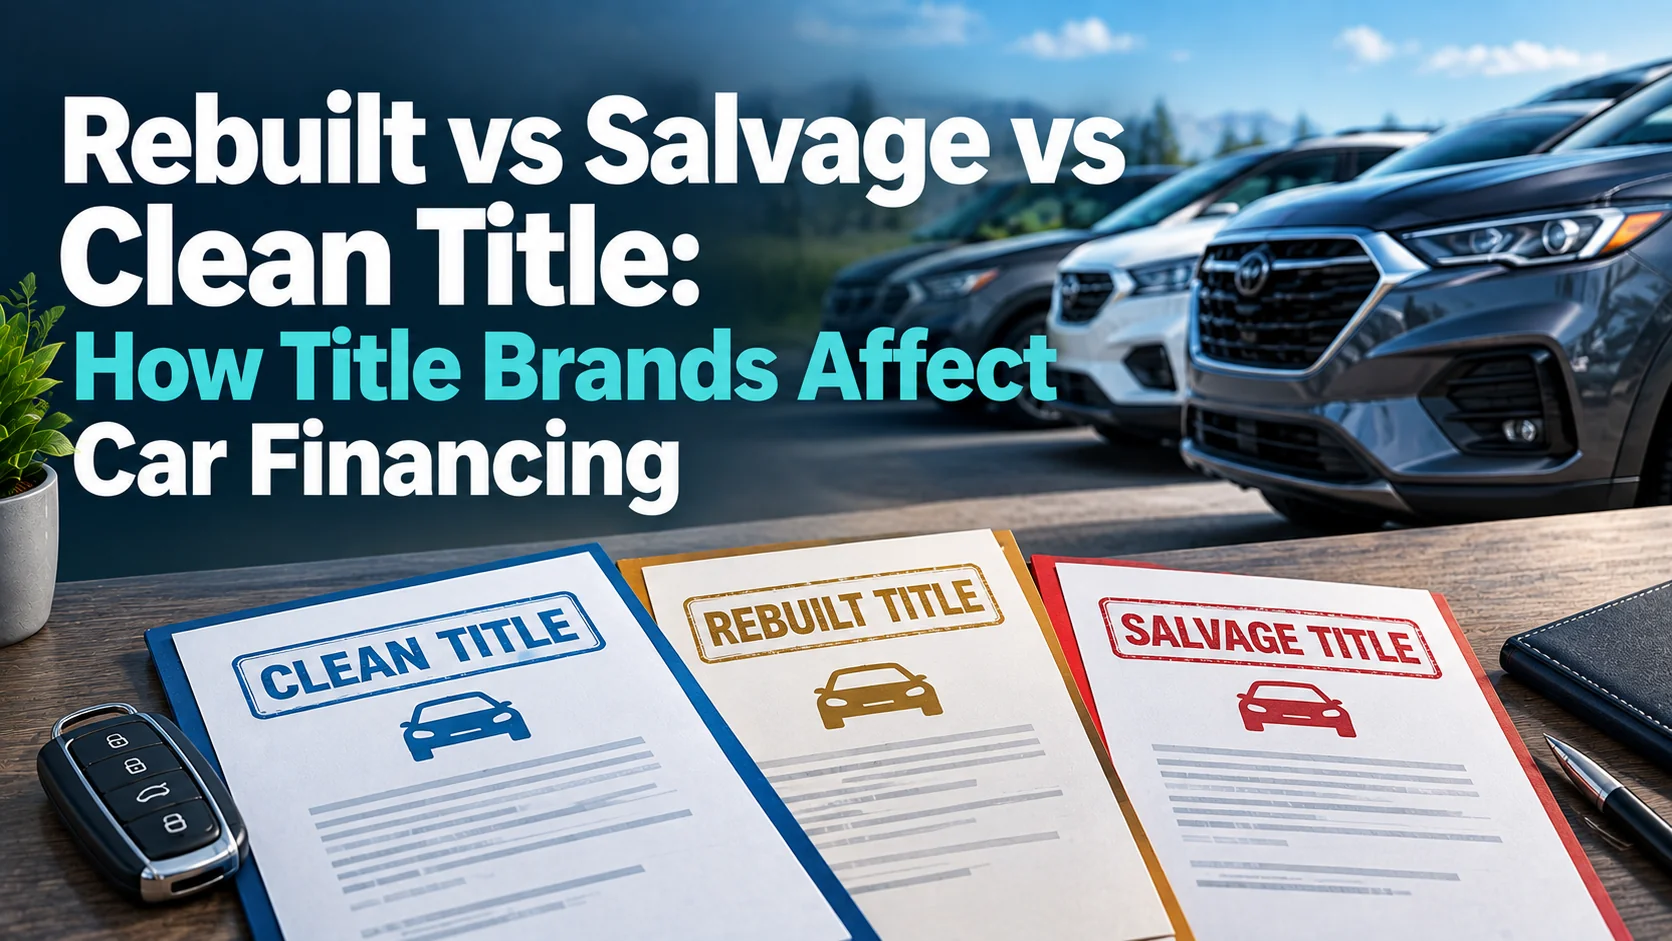
Rebuilt vs Salvage vs Clean Title: How Title Brands Affect Car Financing
In this article
- Can You Finance a Rebuilt or Salvage Title Vehicle in Alberta?
- The Three Title Brands in Alberta: What Each Means
- Clean Title
- Rebuilt Title (Previously "Rebuilt Write-off")
- Salvage Title
- How Lenders Evaluate Title Brands
- How to Check a Vehicle's Title Brand Before Buying
- Insurance Implications of Rebuilt Title Vehicles
- The Resale Value Trap
- When Buying a Rebuilt Title Vehicle Does Make Sense
- Adjacent Situations
- Could Shift Happens Help With This?
- Frequently Asked Questions
- Can I get a car loan for a rebuilt title vehicle in Alberta with bad credit?
- Does a rebuilt title affect my car loan interest rate in Alberta?
- How do I find out if a used car has a rebuilt or salvage title in Alberta?
- What is the difference between a rebuilt title and a hail damage brand in Alberta?
- Can a rebuilt title vehicle be cleared or converted to a clean title in Alberta?
- Compare and Apply
Check Your Options in 3 Minutes
No credit impact. All credit situations welcome.
★★★★★ 114+ Google Reviews · AMVIC Licensed · Free Delivery 300km
Can You Finance a Rebuilt or Salvage Title Vehicle in Alberta?
Financing a rebuilt title vehicle in Alberta is possible but significantly harder than a clean title vehicle — most prime lenders refuse entirely, and subprime lenders that do accept rebuilt titles typically require 20–30% down, reduce the loan-to-value to 80% of rebuilt value (not retail), and charge rates at the top of their range (24–29.99%). Salvage title vehicles are essentially unfinanceable through institutional lenders.
You've found what looks like an incredible deal: a 2020 Ford F-150 with 85,000 km at $18,500 — about $8,000 below comparable clean-title examples. Then you notice the fine print: "rebuilt title." Before you get excited about the discount, you need to understand exactly what that brand means for your financing options, your insurance rates, and your resale value down the road. The discount is real — but so are the costs it creates.
The Three Title Brands in Alberta: What Each Means
Clean Title
A clean title means the vehicle has never been declared a total loss by an insurer, has no significant undisclosed damage history, and is eligible for full standard financing. Clean title is the baseline — it's what you get on any vehicle that hasn't been through a major insurance write-off or flood event. The vast majority of used vehicles on reputable dealer lots in Alberta carry clean titles.
Rebuilt Title (Previously "Rebuilt Write-off")
A rebuilt title in Alberta means the vehicle was previously declared a total loss by an insurance company, then repaired and re-inspected to meet provincial safety standards. To obtain a rebuilt title, the vehicle must pass Alberta's out-of-province inspection protocol — a rigorous mechanical and safety check. A rebuilt brand stays on the title permanently regardless of subsequent repairs or ownership changes.
Rebuilt vehicles in Alberta must have their status clearly disclosed. Under AMVIC regulations and the used car inspection requirements, dealers must disclose branded titles in writing before sale. If they don't, you have recourse.
Salvage Title
A salvage title means the vehicle was declared a total loss and has NOT been repaired and re-inspected. Salvage vehicles cannot legally be driven on Alberta roads — they're mechanically unfit or unverified. Salvage vehicles can be purchased for parts, off-road use, or as project vehicles, but they carry essentially no financeable value through institutional lenders.
How Lenders Evaluate Title Brands
Here's where most buyers get surprised: lenders don't just care about whether a vehicle is drivable — they care about resale value, because the vehicle is their collateral. A rebuilt title vehicle is worth 20–40% less than a comparable clean title vehicle at retail, and substantially less at wholesale auction if they ever have to sell it after a default.
| Title Type | Prime Lenders (TD, RBC) | Subprime Lenders | Max LTV | Rate Impact |
|---|---|---|---|---|
| Clean title | Standard financing | Standard financing | 100–130% | None |
| Rebuilt title | Usually declined | Case-by-case, 20–30% down | 75–80% rebuilt value | +2–5 points |
| Salvage title | Declined | Declined | Not applicable | Not applicable |
| US title brand (Lemon) | Declined | Declined | Not applicable | Not applicable |
| Hail damage brand | Case-by-case | Generally acceptable | 80–90% of actual value | +1–2 points sometimes |
The lender's concern with a rebuilt title vehicle is the "double discount" problem: if you default on a $20,000 rebuilt-title loan and the vehicle goes to auction, they might recover $10,000 on a vehicle that was already discounted 30% from clean-title retail. Their collateral exposure is much worse than on a clean-title vehicle of the same stated value.
The real cost of a rebuilt title discount in Alberta: That $8,000 discount on the rebuilt F-150 sounds great. But if you need financing: (1) you'll likely need $5,000–$6,000 down instead of $2,000, (2) your rate may be 24.99% instead of 18.99% — costing roughly $3,200 more in interest over 60 months, (3) your insurance premium may be 15–25% higher, (4) resale value is permanently impaired. The effective "discount" can shrink to $1,000–$2,000 when all costs are accounted for. Check your options on a clean-title vehicle at our approval tool before deciding.How to Check a Vehicle's Title Brand Before Buying
Alberta title brands are recorded with ServiceAlberta and are legally required to be disclosed on the vehicle's registration documents. There are three ways to verify:
- CARFAX Canada — the most accessible option. A CARFAX Canada report pulls from Alberta's registration database plus cross-references US state databases for vehicles with US history. Mandatory reading before any used car purchase.
- Carproof — similar service to CARFAX Canada. Some dealers provide one of these for free. If the dealer "doesn't have one available," that's a flag worth probing.
- Alberta PPSA lien search — confirms whether there's an outstanding lien on the vehicle (active loan from a previous owner). This is separate from title brand checking but equally important. A $10–$15 PPSA search through ServiceAlberta is cheap insurance against buying a vehicle someone else's lender can repossess.
Neither CARFAX nor Carproof is perfectly comprehensive — damage that wasn't reported to insurance or that occurred outside Canada may not appear. A professional Alberta Vehicle Inspection by an independent mechanic ($150–$250) is the physical complement to the paper trail.
Insurance Implications of Rebuilt Title Vehicles
Insurance for rebuilt title vehicles in Alberta is more expensive and harder to find than clean title coverage. Standard insurers may decline to offer collision and comprehensive coverage on rebuilt-title vehicles entirely — leaving you with basic liability only. Specialty insurers that do cover rebuilt vehicles often charge 15–30% more for equivalent coverage, and many will only insure for the "rebuilt value" rather than retail replacement cost.
Why does this matter for financing? Some lenders require specific insurance coverage as a condition of the loan — particularly comprehensive coverage that protects their collateral in the event of theft or a non-collision event. If your insurance won't cover the vehicle to the lender's required standard, the loan won't fund even if credit approval was granted. For general guidance on Alberta vehicle insurance and how it interacts with financing, see Alberta auto insurance explained.
The Resale Value Trap
Rebuilt title vehicles sell for 20–40% less than comparable clean-title vehicles at retail, and this discount persists regardless of how well the vehicle is maintained or how many subsequent owners it has. The brand is permanent on the Alberta title. When you try to sell or trade in a rebuilt-title vehicle, you're selling into a smaller buyer pool (fewer buyers willing to accept the brand), and any dealer taking it in trade will heavily discount it to reflect resale difficulty.
This creates a "negative equity accelerant" problem for financed rebuilt-title vehicles: you start with a vehicle worth less than retail, you pay a higher interest rate, and your vehicle depreciates into a thinner resale market. If life events force you to sell or trade within the first 36 months, you're almost guaranteed to be significantly upside-down. That's a risk worth pricing in before you sign. Read more about how negative equity works in negative equity car financing.
When Buying a Rebuilt Title Vehicle Does Make Sense
For cash buyers who are mechanically knowledgeable, don't plan to finance, and intend to keep the vehicle long-term, rebuilt title vehicles can genuinely represent value. A well-repaired, inspected, and maintained rebuilt-title vehicle is functionally equivalent to a clean-title vehicle if the repair was done correctly. The discount reflects stigma as much as real diminished value — which benefits the informed cash buyer willing to do due diligence.
The key conditions: (1) cash purchase so financing constraints don't apply, (2) professional inspection by an independent mechanic who knows what to look for in rebuilt vehicles, (3) complete repair documentation showing what was damaged and how it was repaired, (4) long intended ownership (5+ years) so resale value impairment doesn't force an early exit.
If you're financing and looking for the value play, a clean-title high-mileage vehicle typically offers better all-in economics than a low-mileage rebuilt. Talk to the team at Airdrie about what's available in your budget. For subprime buyers who need financing, the constraints are real — and we work within them honestly. Start an application and tell us what you're looking at.
Adjacent Situations
If this post was useful, these directly-related guides will help you go deeper:
- Open-End vs Closed-End Lease vs Finance: Which Suits Used Buyers
- Conditional Sales Contract vs Loan vs Lease: Legal Differences
- 60 vs 72 vs 84 vs 96 Month Loans: Real Cost Comparison
- New vs Used vs CPO: 5-Year Cost of Ownership Compared
- Dealership vs Private Sale vs Auction: Where the Value Lives
- Buying a Used Car in Lethbridge vs Driving to Calgary
Could Shift Happens Help With This?
We're likely a fit if you: (1) are evaluating a rebuilt title vehicle purchase and want honest advice on financing feasibility, (2) have any credit situation and want to explore clean-title vehicles that fit your budget, (3) are in Alberta and want a transparent lender network assessment. Not a fit if: new vehicles only, lease-only, or buying outside western Canada.
The fastest next steps: check your approval likelihood (60 seconds) or start a financing application. No impact on your credit score until you formally proceed.
Frequently Asked Questions
Can I get a car loan for a rebuilt title vehicle in Alberta with bad credit?
It's very difficult. Rebuilt title vehicles are already challenging for prime borrowers; for subprime borrowers (scores below 600), most lenders view the combination of elevated borrower risk and impaired collateral value as unacceptable together. Some specialty subprime lenders will consider rebuilt titles with a 25–30% down payment and strong income. Cash is a significantly better strategy for rebuilt-title purchases when you have challenged credit.
Does a rebuilt title affect my car loan interest rate in Alberta?
Yes, meaningfully. Lenders that do accept rebuilt title vehicles price in their elevated recovery risk through higher rates — typically 2 to 5 percentage points above what the same borrower would receive on a clean-title vehicle. On a $20,000 loan over 60 months, 3 extra points costs approximately $1,800 in additional interest. That's part of the real cost calculation of a rebuilt-title "discount."
How do I find out if a used car has a rebuilt or salvage title in Alberta?
Run a CARFAX Canada or Carproof report on the VIN — both services pull from Alberta's registration database plus US state records. The title brand will appear if it's recorded in the system. Dealers in Alberta are legally required (AMVIC) to disclose branded titles in writing before sale. Additionally, check the physical registration documents — the title brand must appear on Alberta registration paperwork.
What is the difference between a rebuilt title and a hail damage brand in Alberta?
A rebuilt title indicates the vehicle was declared a total loss by an insurer and subsequently repaired and re-inspected. A hail damage brand indicates significant cosmetic hail damage was recorded but the vehicle was not declared a total loss. Hail-damaged vehicles are easier to finance — most lenders treat them similarly to clean title, sometimes with a small rate premium. Rebuilt titles are far more restrictive from a lender's perspective.
Can a rebuilt title vehicle be cleared or converted to a clean title in Alberta?
No. In Alberta, once a vehicle receives a rebuilt brand, that designation is permanent on the provincial title. There is no process to clear or convert it to a clean title regardless of subsequent repairs, ownership, or the passage of time. The brand follows the VIN permanently in Alberta's registration records.
Compare and Apply
- Bad Credit Financing — Complete Guide — financing for low credit scores
See what you pre-qualify for
Three quick answers — soft check, no commitment.
Financing Resources
Related Articles
Ready to Find Your Vehicle?
Browse our inventory or apply for financing. All credit situations welcome.
★★★★★ 114+ Google Reviews · AMVIC Licensed · Free Delivery 300km