Getting a Car Loan During an Active Bankruptcy
Last reviewed: October 2026
Can you buy a car during a bankruptcy in Canada?
You can, but talk to your licensed insolvency trustee first. Property you acquire before your discharge can go to your trustee unless the law exempts it, so how you pay (exempt cash, other cash or a loan) decides what happens to the car.
Who this page is for
- You are in a bankruptcy that has not been discharged yet, or about to file.
- You have steady work and need a vehicle to keep it.
- You want to know what to ask your trustee before you spend money or sign a loan.
Lenders look for steady income you can prove. If yours is not steady right now, start with your trustee, not a lender.
This page is about buying while the bankruptcy is still open. If you have already been discharged, start with car financing after bankruptcy. This page is general information, not legal advice. Your licensed insolvency trustee can tell you what applies to your file.
Financing During or After Bankruptcy
Active or discharged. We review every application and call you back.
5.0121+ Google ReviewsAMVIC LicensedFree Delivery 300km
Key Facts
- Talk to first
- Your licensed insolvency trustee
- Paying cash
- Money your trustee confirms is exempt is simplest; other money may belong to your estate
- Borrowing
- For credit of $1,000 or more, tell the lender you are an undischarged bankrupt
- Alberta exempt vehicle
- Your interest in one vehicle, up to $5,000
- First-bankruptcy discharge
- 9 months, or 21 months with surplus income payments
Tell Your Trustee, Then Tell Your Lender
The Three Ways to Buy During a Bankruptcy: Exempt Cash, Other Cash or a Loan
Property you acquire before your discharge can be sold for your creditors unless the law exempts it. That one rule is why how you pay matters. That comes from section 67 of the Bankruptcy and Insolvency Act. The Office of the Superintendent of Bankruptcy (OSB), the federal office that oversees trustees, puts it in plain words: your trustee sells your assets, including any you acquire during the bankruptcy, and assets that are exempted by provincial and federal laws are left out.
| How you pay | What happens | What to ask your trustee |
|---|---|---|
| Cash from money that is exempt | Exempt property stays with you and is left out of what your trustee sells. This is the simplest route, but only for money the law actually exempts. | Is this money exempt? Please confirm it in writing before I spend it. |
| Cash from money that is not exempt | Money and property you acquire before discharge can be sold for your creditors. A car bought with it can end up in your estate, and spending it without telling your trustee can put your discharge at risk, because creditors, your trustee and the OSB can oppose a discharge for misconduct. | Can I use this money? What happens to a car I buy with it? |
| A car loan | You must tell the lender you are an undischarged bankrupt when you borrow $1,000 or more. A loan is a new debt on top of your bankruptcy, and the car is still property you acquire before discharge, so ask what that means if it is worth more than you owe. | Do you need to approve this loan before I sign? Does anything change in my surplus income? |
What is surplus income, and does a car payment change it?
Surplus income is the part of your pay above what a family your size needs, as the OSB sets it each year. If it is $200 or more a month, you pay 50 percent of it to your estate, and your automatic discharge comes after 21 months instead of 9. Each month you give your trustee your pay stubs and proof of other income, and the trustee does the calculation.
The OSB formula subtracts a short list of set expenses, such as child and spousal support, child care and medical costs. A new car payment is not on that list, so do not count on one lowering what you pay your estate. Ask your trustee how your file is treated.
What Does “Exempt Property” Mean for a Vehicle in Alberta?
Exempt property is property the law says creditors cannot take. In a bankruptcy it stays with you. Which property is exempt comes from provincial law, so the Alberta rules apply to Albertans.
One Vehicle, Up to $5,000
Alberta's Civil Enforcement Act exempts a debtor's interest in one motor vehicle up to a value set by regulation, and the Civil Enforcement Regulation sets that value at $5,000. In plain terms, that is roughly your ownership share in one vehicle, what it is worth less what you still owe on it, up to $5,000. It is not a limit on the price of the car you can drive.
Your Car Loan Is Treated Separately
The OSB says bankruptcies generally do not affect the rights of secured creditors, which includes a lender with a claim on your car. Ask your trustee how your loan and your car will be treated.
Your Trustee Decides How It Applies
Whether a particular car or a particular pot of money is exempt depends on your file. Do not guess. Ask your trustee before you buy.
What Changes When You Finance a Car During an Active Bankruptcy?
Some lenders will look at an undischarged bankruptcy, but many mainstream lenders will not. The ones that do care more about your income, the vehicle and the size of the loan than about your score. A bankruptcy is assigned the lowest possible credit score, according to the OSB, so lenders in this space work from your current income and the vehicle. We serve Airdrie and Calgary, with walk-in visits or free delivery.
Who Lends
In our experience, most banks and prime lenders do not finance an undischarged bankruptcy. A smaller group of lenders have programs for it. Every lender decides each file.
What Lenders Ask For
- Steady income you can prove, such as recent pay stubs.
- How long you have been with your employer.
- The date you filed and the date you expect to be discharged.
- A letter from your trustee, if the lender asks for one.
- A down payment, even a modest one.
The Vehicle and the Loan
Lenders who take these files tend to prefer newer, lower-kilometre vehicles that hold their value, and a loan that is small next to what the car is worth. A down payment lowers the loan. Your trustee may also have a view on what is a reasonable vehicle for your situation.
What It Costs
Rates depend on your credit tier. Our lender programs run 4.99%–29.9% APR across all tiers, and an open bankruptcy often puts a file toward the top of that range. Rates can come down after discharge as your payment history builds. See car loan rates in Alberta for the tiers.
What Should I Bring to My Trustee Before I Buy or Borrow?
Go to your licensed insolvency trustee before you spend money or sign anything. The OSB says trustees are federally regulated professionals who deal with your creditors for you. Bring these:
- A written quote for the vehicle: year, make, model, VIN and price.
- The payment you are looking at: the amount, how often, how many months and the lender, if you are financing. If you apply with us, ask for the lender's terms in writing.
- An insurance quote for that vehicle. Lenders usually ask for proof of insurance before you take the car.
- Your recent pay stubs and proof of other income. Your trustee already collects these each month.
- Where the money is coming from, if you are paying cash or making a down payment, and whether it is exempt.
Questions to ask
- Do you need to approve this purchase or loan before I sign?
- Is the money I plan to use exempt?
- What happens to the car if it is worth more than I owe?
- Will this payment change my surplus income payments or my discharge date?
- Do you need to send a letter to the lender?
Not sure who your trustee is? The OSB keeps a directory of licensed insolvency trustees, and says trustees typically do not charge for the first consultation. A lender may ask for a letter from your trustee. For an example of the kind of letter lenders ask for, see how it works for a consumer proposal.
Nothing on this page constitutes legal or financial advice. Always discuss your specific situation with your licensed insolvency trustee before making decisions about new debt during an active bankruptcy.
Bankruptcy Discharge Timeline in Canada
Knowing when your bankruptcy ends helps you decide whether to buy now or wait. Discharge timing is set by section 168.1 of the Bankruptcy and Insolvency Act and depends on whether it is your first bankruptcy and whether surplus income applies. For the full picture, see our bankruptcy discharge timeline.
First Bankruptcy, No Surplus Income Payments
If this is your first bankruptcy and you are not required to make surplus income payments, you are automatically discharged 9 months after the date of bankruptcy, unless someone opposes it. The OSB also says you must attend two counselling sessions. Your trustee then issues your discharge certificate.
First Bankruptcy, With Surplus Income Payments
If you are required to make surplus income payments to your estate, the automatic discharge comes 21 months after the date of bankruptcy instead of 9. That happens when your income is above what the OSB says your family needs. Your trustee works out the amount each month from your pay stubs.
Second or Later Bankruptcy
A second bankruptcy is automatically discharged 24 months after the date of bankruptcy, or 36 months if you must make surplus income payments. If it is not your first or second bankruptcy, or the discharge is opposed, your trustee asks the court to hear your application. If you have declared bankruptcy more than once, the credit bureaus keep it on your report for 14 years.
Objections to Discharge
Your trustee, a creditor or the OSB can oppose your discharge if they believe you have committed misconduct, which includes failing to respect your duties, such as declaring your property to your trustee and cooperating with them. The court reviews the opposition and decides. It can refuse the discharge, suspend it or make it conditional.
What to Expect After Your Discharge
Discharge is the turning point: more lenders look at your file, and the question shifts from whether anyone will lend to how good the terms can be. Review current car loan rates in Alberta to benchmark your options. Ask about our extended warranty coverage for additional protection, and browse our used cars under $25,000 in Airdrie for lender-friendly vehicle options.
What Changes After Discharge
Your bankruptcy moves from open to discharged, and more lenders will look at the file. Vehicle choice widens, and you are no longer working around an open estate. The bankruptcy still shows on your credit report for 6 years after discharge in Alberta, and each lender decides each file.
Building Credit After Discharge
A car loan can add new positive history. Equifax says active accounts paid as agreed stay on your credit report as long as the account is open and the lender is reporting it. On-time payments are the part of your file you control.
Refinancing After Your Credit Recovers
If you financed during the bankruptcy at a high rate, it is worth asking about refinancing once you are discharged and have some on-time payment history. A lender looks at your current credit profile, not at how you first financed the car.
Active Bankruptcy Financing FAQs
Can I get a car loan during an active bankruptcy in Canada?
Some lenders will look at an undischarged bankruptcy, but many banks and prime lenders will not. If you borrow $1,000 or more, the law requires you to tell the lender you are an undischarged bankrupt. Talk to your trustee before you apply. We review every application and call you back, and each lender decides each file.
Can I pay cash for a car during a bankruptcy?
Cash from money your trustee confirms is exempt is the simplest route. Property you acquire before discharge can be sold for your creditors unless the law exempts it, so a car bought with money that is not exempt can end up in your estate. Ask your trustee which of your money is exempt before you spend it.
What specific information does a trustee need to provide for my car loan application?
Some lenders ask for a letter from your trustee that confirms the bankruptcy, the expected discharge date and that the trustee knows about the financing. What your trustee will provide depends on your file. We can tell you what a specific lender needs before you contact your trustee, so the request is complete the first time.
How long does a first-time bankruptcy last in Canada?
A first bankruptcy is automatically discharged 9 months after the date of bankruptcy, or 21 months if you must make surplus income payments. A second bankruptcy is 24 months, or 36 months with surplus income payments. The discharge is not automatic if it is opposed.
What interest rate should I expect for a car loan during active bankruptcy?
Your rate depends on your credit tier, and a file in an open bankruptcy often sits toward the top of the range. Our lender programs run 4.99%–29.9% APR across all tiers. Rates can come down after discharge as your payment history builds. Each lender decides each file, and your income, down payment and vehicle count too.
Can I keep my current vehicle during bankruptcy in Alberta?
Alberta law exempts your interest in one motor vehicle up to $5,000 (Civil Enforcement Act, section 88(d), and Civil Enforcement Regulation, section 37(1)(c)), and exempt property stays out of what your trustee sells. If you have a car loan, the Office of the Superintendent of Bankruptcy (OSB) says bankruptcies generally do not affect the rights of secured creditors. Ask your trustee how your car and your loan will be treated.
Will I be limited in what vehicle I can finance during bankruptcy?
In our experience, lenders who take undischarged files prefer newer, lower-kilometre vehicles that hold their value, and a loan that is small next to what the car is worth. A down payment lowers the loan. Your trustee may also have a view on what is a reasonable vehicle for your situation.
Is it better to wait until after discharge to get a car loan?
If you can wait, more lenders look at a discharged file. If you need a vehicle to keep working, waiting 9 to 21 months may not be practical. Either way, talk to your trustee first, because how you pay for the car matters while the bankruptcy is open.
Sources (pages opened October 5, 2026): Bankruptcy and Insolvency Act, section 67 (what a bankruptcy covers); Bankruptcy and Insolvency Act, section 168.1 (automatic discharge); Bankruptcy and Insolvency Act, section 199 (telling a lender you are an undischarged bankrupt); Office of the Superintendent of Bankruptcy: Considering bankruptcy; Office of the Superintendent of Bankruptcy: When bankrupts fail to respect their obligations; Office of the Superintendent of Bankruptcy: Directive No. 11R2-2026, Surplus Income; Office of the Superintendent of Bankruptcy: What is a Licensed Insolvency Trustee?; Alberta King's Printer: Civil Enforcement Act, section 88; Alberta King's Printer: Civil Enforcement Regulation, section 37; Financial Consumer Agency of Canada: How long information stays on your credit report; Equifax Canada: How long does information stay on your credit report?. These are public government pages. Laws and directives change, so ask your licensed insolvency trustee what applies to your file.
Cars in stock you could finance
See all inventory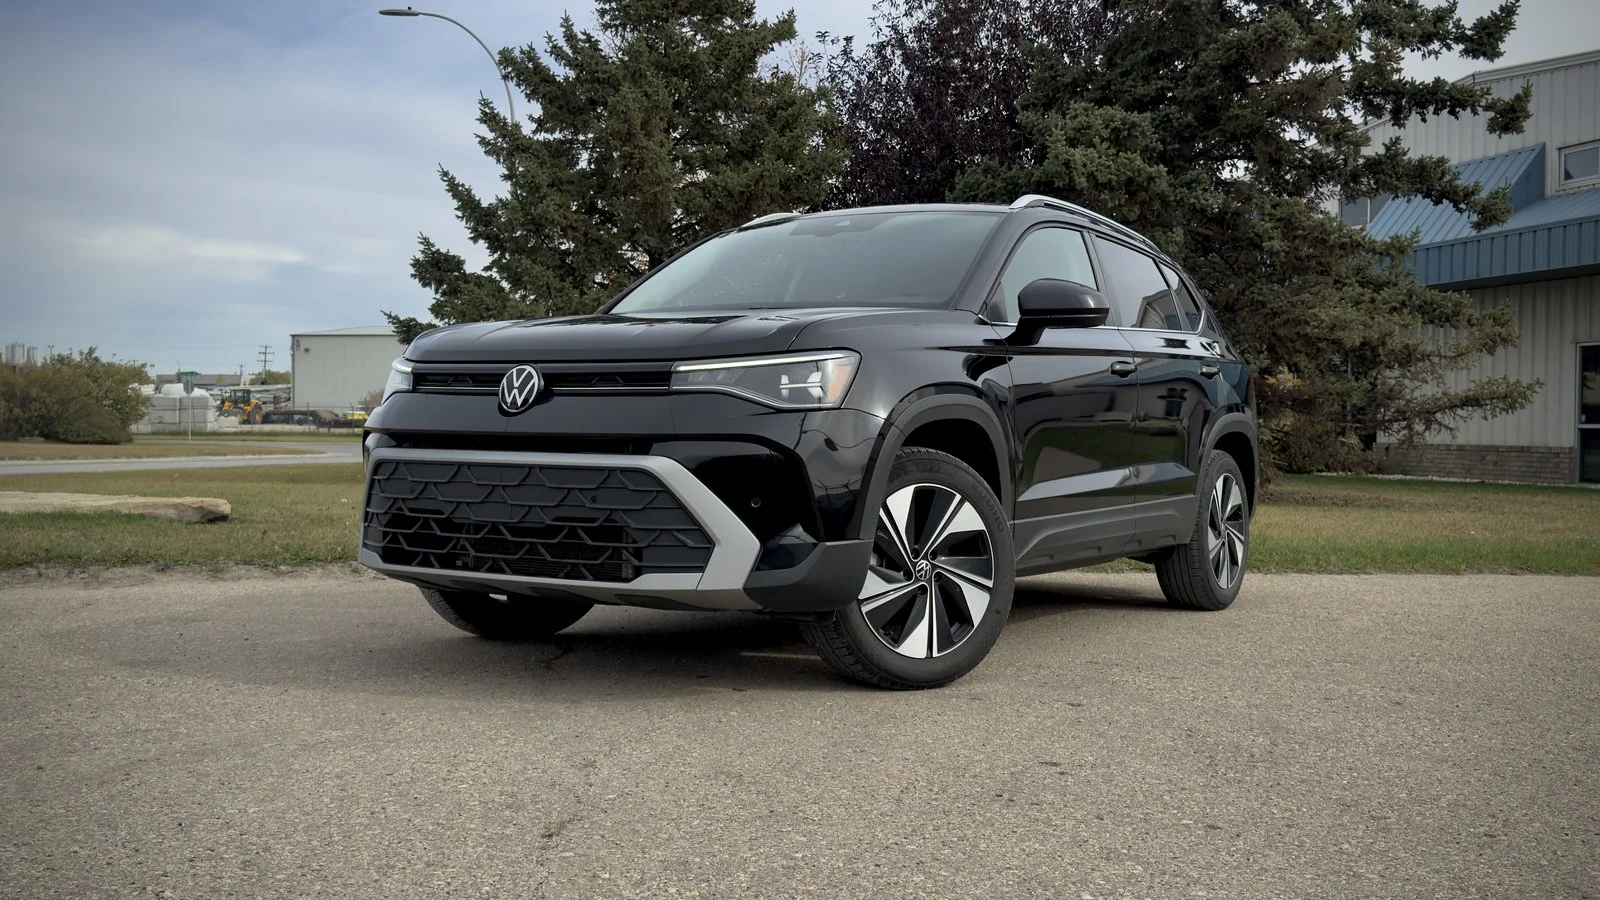
2025 Volkswagen Taos Comfortline
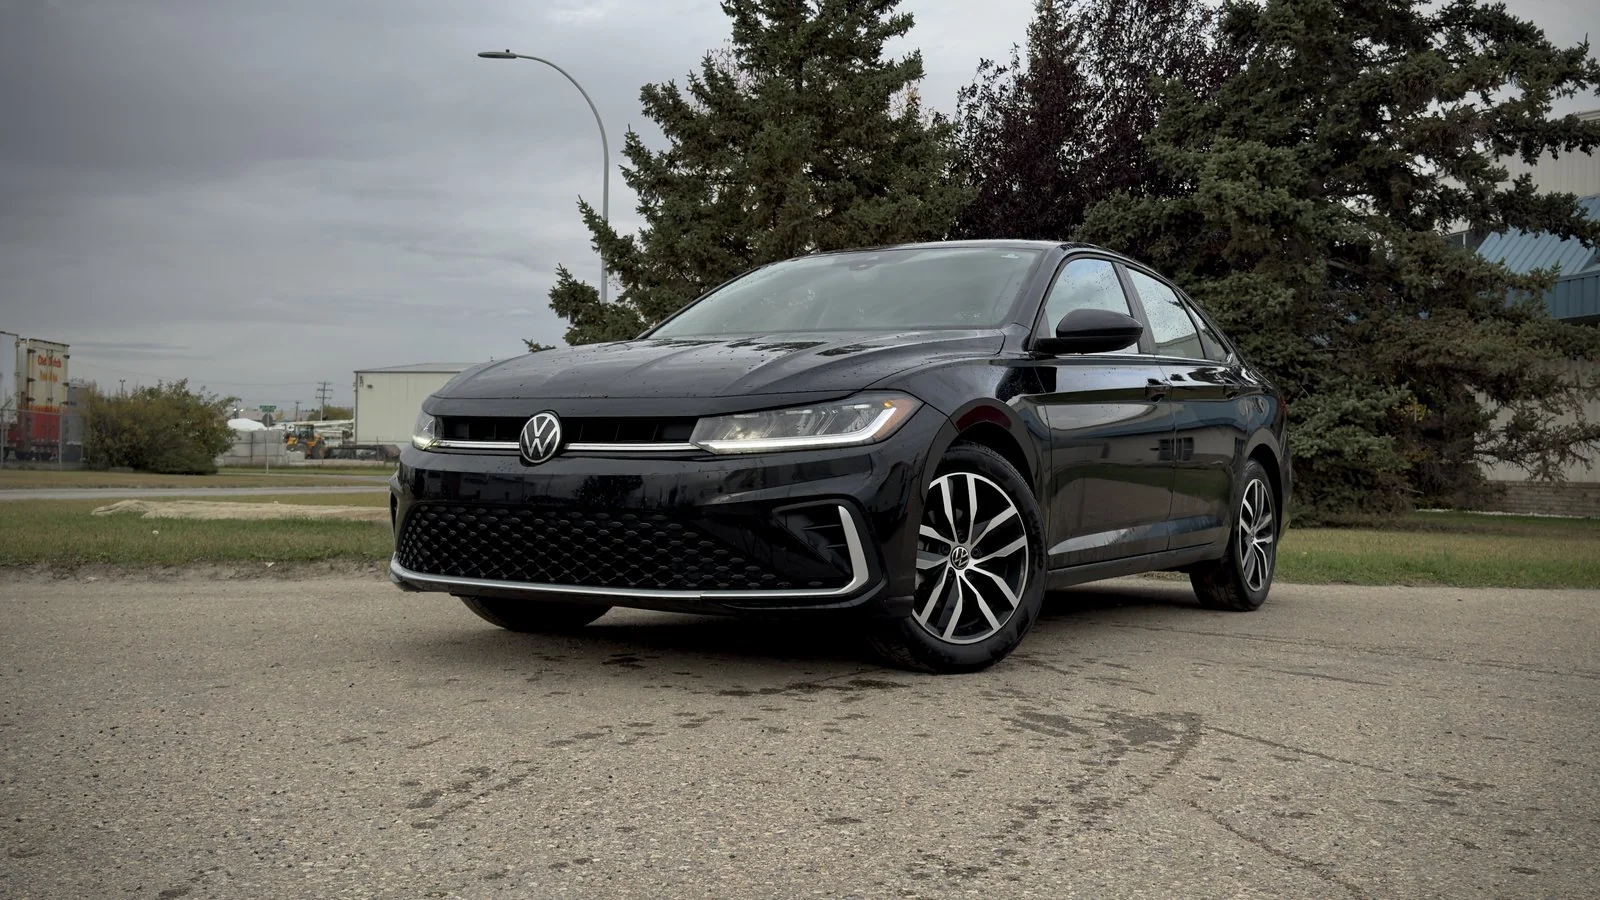
2026 Volkswagen Jetta Comfortline
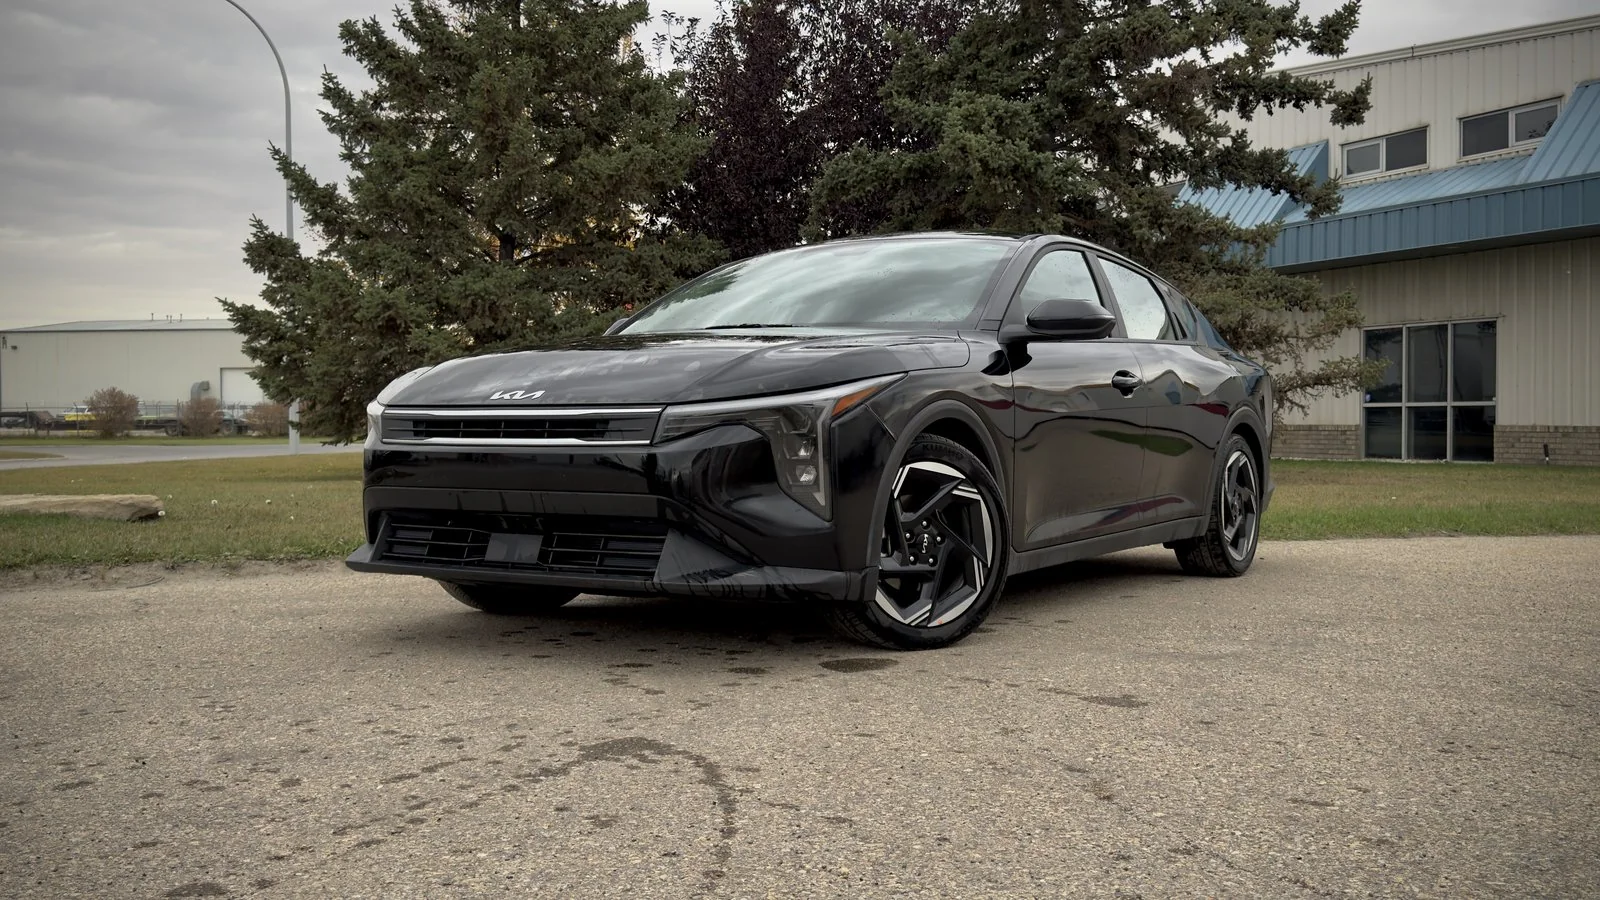
2025 Kia K4 EX
Not seeing it? We'll find it.
We source through our dealer partner network across Western Canada: 25,000+ vehicles to choose from. Tell us what you want and what works for your budget.
Find my car3 min · no credit impactOAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
What Our Customers Say
“Thanks to Luke and his team. They were able to find me my dream car and have it delivered between cities. Easy to deal with and easy to work with.”
“A huge thank you to Wes and Luke for making my vehicle purchase such a great experience. This has been the best experience I've had at a dealership. They were patient, kind, and attentive.”
“The buying experience was handled very professionally. Wes was very attentive and presented everything in an open and honest manner that gave me the reassurance that I made a good purchase.”
Financing During or After Bankruptcy
Active or discharged. We review every application and call you back.
5.0121+ Google ReviewsAMVIC LicensedFree Delivery 300km
In an Active Bankruptcy and Need a Vehicle?
Tell us your situation up front and we will go through your options with you. Talk to your trustee first, then apply. No judgment, just practical help.
Questions about how your bankruptcy affects your options? Call us and we will give you a clear answer without the runaround.