Car Financing After Divorce in Alberta
Separation changes everything — including your financial profile. Joint debts, credit score damage, and single-income qualifying are real obstacles. We help Albertans navigate post-divorce car financing with lenders who understand your situation, not just your score.
Last reviewed: October 2026
Going Through a Divorce?
Get your own vehicle financing. All credit situations welcome.
5.0121+ Google ReviewsAMVIC LicensedFree Delivery 300km
Key Facts
- Support income accepted
- Spousal + child support
- Joint loan refinancing
- Remove ex from loan
- Minimum credit score
- No hard minimum to apply. Your score mostly changes the rate (4.99%–29.9% APR).
- How it works
- We review every application and call you back
- Service area
- All of Alberta
Single Income Approvals Are Our Specialty
Why Does Divorce Complicate Car Financing?
It complicates financing because joint debts stay on your credit file until they are formally refinanced, your credit score often drops during the separation process, and your qualifying income drops from dual to single. Lenders experienced with post-divorce situations look at your current individual income and ability to pay — not your marital history.
Divorce is one of the most financially disruptive events a person can experience. Statistics Canada reports that approximately 38% of Canadian marriages end in divorce, and Alberta consistently ranks among the provinces with the highest divorce rates. The financial fallout extends well beyond legal fees.
During a marriage, credit is often intertwined. Joint auto loans, shared credit cards, a mortgage with both names — these all create a credit entanglement that does not automatically unwind when you separate. Your ex-spouse's financial behaviour continues to affect your credit report until every joint account is either closed, paid off, or refinanced into one name.
The transition from dual income to single income also reshapes what lenders are willing to approve. A household that once earned $120,000 combined may now be two households earning $60,000 and $60,000 separately — each carrying expenses that were previously shared. Lenders recalculate debt-to-income ratios on your individual numbers, and the math often does not work with traditional banks. That is where alternative lenders and specialists like us come in.
What Financial Challenges Follow a Separation?
The four most common are: joint debt on your credit report, a credit score drop from missed payments during the chaos of separation, reduced qualifying income as a single earner, and unresolved vehicle division. Each has a practical solution — and none of them permanently blocks you from getting financing.
Joint Debt on Your Credit
Joint auto loans and credit cards from your marriage still appear on your credit report. Even debts your ex was ordered to pay affect your debt-to-income ratio until they are formally refinanced or discharged.
Credit Score Drop After Separation
Missed payments during the chaos of separation, maxed credit cards from legal fees, and accounts going to collections are all common. Your score may have dropped 50-150 points through no single fault of your own.
Single Income Qualifying
Going from dual income to single income changes what you qualify for. We work with lenders who factor in spousal support, child support, and the Canada Child Benefit to maximize your qualifying amount.
Unresolved Vehicle Division
If your separation agreement is not finalized, vehicle ownership can be unclear. We help customers secure financing even during the transition period, and can refinance once the division is legally settled.
How to Remove Your Ex-Spouse From a Joint Auto Loan
A divorce agreement or court order may state that your ex is responsible for the vehicle loan — but the lender is not bound by your divorce decree. As far as the bank is concerned, both signers are equally liable until the loan is paid off or refinanced. This is one of the most misunderstood aspects of post-divorce finances.
The clean solution is to refinance the joint loan into the name of whoever is keeping the vehicle. This requires that person to qualify individually. If your credit has been damaged during the separation process, you may not qualify with your bank — but subprime and alternative lenders evaluate these situations differently.
We handle joint loan refinancing regularly. The process typically works like this:
- You apply with us, providing your individual income and the existing loan details.
- We submit to lenders who specialize in post-separation refinancing.
- Once approved, the new loan pays off the old joint loan entirely.
- The old joint loan is closed, removing your ex from the obligation (or removing you, depending on who keeps the vehicle).
The result: one clean loan, one name, one payment. Your ex's credit activity no longer affects your auto financing, and vice versa.
How Do I Buy a Car on One Income After a Separation?
Start with your own pay. Work out what fits your income alone, then show a lender every other source of income you have.
When you apply on your own, a lender looks at your income, your debts and the new payment. One bank's published credit policy says your total income must support your current liabilities and living expenses plus the additional credit you are applying for. Here is one example on one income.
- Gross pay
- $4,200 a month
- Credit score
- 550–599
- Vehicle
- used compact SUV, $22,000
- Down payment
- $0
- Amount financed
- $22,000 over 72 months
- Example rate
- 16.9% APR (Subprime example)
Payment:~$225/bi-weekly(or ~$488/mo)
That is about 12% of gross monthly pay. A common rule of thumb is to keep a car payment under 15% of gross pay.
Example, not an offer. Your rate depends on your file; rates run from 4.99% APR (prime) to 29.9% APR (deep subprime).
Check what is still in both names. A joint loan or card stays tied to you until it is paid off, closed or refinanced. You can get your credit report free from both Canadian credit bureaus, and one bank's advice page suggests checking it for a joint card you forgot about. The section above explains how to take your ex-spouse off a joint auto loan.
What about support payments? Whether a lender counts support as income, and how much of it, is that lender's decision. This is what the official sources say about how support shows up on paper. It is legal information, not legal advice.
- The Canada Revenue Agency treats a payment as support when it is a specific amount paid to you under a court order or written agreement, on a periodic basis.
- Spousal support you receive must be included in your income on your tax return. Child support generally does not have to be, so it will usually not show in the income your Notice of Assessment reports.
- Alberta's Maintenance Enforcement Program says a clearly written court order states when payments begin, when they are due, the amount of each payment and any terminating events. Know your end date before you rely on support.
- If your support comes through the Maintenance Enforcement Program, it is deposited directly into your bank account, so your bank statements show it.
Plan on your own pay. Treat support as extra a lender may or may not count, especially if your order has an end date. We cannot promise that any lender will count it, so tell us about every source of income you receive.
What to bring:
- Government photo ID.
- Your last two pay stubs and your latest T4 or Notice of Assessment.
- Your separation agreement or court order, showing the amounts, the dates and any end date.
- Bank statements that show support arriving.
- A list of any joint loans or cards still in both names.
We review every application and call you back, and every lender decides each file. For questions about your own order or agreement, talk to your lawyer.
Sources (pages opened October 5, 2026): Canada Revenue Agency: support payments; Canada Revenue Agency: amount you can claim or report; Canada Revenue Agency: after sending your tax return; Government of Alberta: Maintenance Enforcement Program; Financial Consumer Agency of Canada: your credit report; TD: credit granting; Scotiabank: are you responsible for your spouse’s debt. These are public pages, quoted to show what governments, banks and lenders publish. Every lender sets its own rules, so check the lender's own page before you rely on a detail.
How Alberta Family Law Handles Vehicle Division
Under Alberta's Family Property Act, vehicles acquired during the marriage are generally considered matrimonial property subject to equitable division. This does not always mean a 50/50 split — the court considers factors like who needs the vehicle for work, who has primary custody of children, and the overall balance of the property division.
Vehicles owned before the marriage, gifts, or inheritances may be exempt from division, though any increase in value during the marriage could still be divisible. If you and your ex-spouse both have vehicles, the typical outcome is that each person keeps the one they primarily drive, with the net value factored into the overall equalization payment.
Where it gets complicated is when there is negative equity — the loan balance exceeds the vehicle's value. Negative equity is a shared debt, and the court must decide how to allocate it. In practice, the person who keeps the vehicle usually assumes the debt, but this can be offset against other assets in the division.
If your separation agreement assigns you a vehicle but you cannot afford the existing loan on your own, refinancing to a more manageable payment structure is often the practical next step. We work with lenders across Alberta who understand these transition scenarios.
Rebuilding Your Credit Score After a Divorce
A divorce can set your credit back years, but rebuilding is absolutely possible — and an auto loan is one of the most effective tools to do it. Installment loans (like car loans) carry significant weight in credit score calculations because they demonstrate consistent, long-term payment behaviour.
Here is a realistic rebuilding timeline for someone starting with post-divorce credit damage:
Open individual accounts if you do not have any. A secured credit card and a small auto loan are the fastest combination. Make every payment on time. Your score may not move much yet — the bureaus are watching for a pattern.
With 6 months of on-time payments, your score typically begins climbing. Old negative items from the divorce period start aging, which reduces their impact. Most customers see a 40-80 point improvement in this window.
After a year of consistent payments, refinancing to a better rate becomes possible. By 18-24 months, many customers have moved from subprime to near-prime territory. The auto loan that started as a necessity becomes the foundation of your rebuilt credit profile.
The key principle: an auto loan taken at a higher rate today is an investment in a lower rate tomorrow. Every on-time payment builds equity in your credit file.
Alberta Resources for Divorcing Families
Navigating divorce involves more than just financing. Alberta offers several free and low-cost resources that can help with the legal and financial aspects of separation:
Alberta Legal Aid
Legal Aid Alberta provides free legal assistance to Albertans who qualify based on income. Family law matters including divorce, custody, and property division are covered. If you cannot afford a private lawyer, Legal Aid should be your first call.
Family Justice Services
Alberta Family Justice Services offers free mediation, parenting courses, and information sessions at courthouses across the province — Calgary, Edmonton, Red Deer, Lethbridge, and Medicine Hat. Mediation can help resolve property and debt division disputes without the cost of a full trial.
Credit Counselling Societies
Non-profit credit counselling organizations like the Credit Counselling Society of Alberta offer free consultations to help you understand your post-divorce financial picture. They can review your credit report, help you create a budget on your new single income, and advise on debt management strategies.
AMVIC Consumer Protection
As an AMVIC-licensed dealer, Shift Happens Auto Sales is held to Alberta's strict consumer protection standards. AMVIC regulates all automotive businesses in the province, ensuring fair dealing, accurate advertising, and full disclosure. You are protected by law when purchasing a vehicle from a licensed dealer.
Divorce Car Financing Across Alberta
We provide post-divorce vehicle financing across the province with free delivery within 300km of our Airdrie location. Major Alberta cities we serve include:
Frequently Asked Questions
How does Alberta's Family Property Act divide vehicles in a divorce?
Under Alberta's Family Property Act, vehicles acquired during the marriage are generally treated as matrimonial property subject to equitable division. This does not always mean a 50/50 split — courts consider who needs the vehicle for work, who has primary custody, and the overall balance of the division. Vehicles owned before marriage may be exempt, though value increases during the marriage could still be divisible. When both spouses need transportation, each typically keeps the vehicle they primarily drive.
If my divorce agreement says my ex is responsible for the car payment, why do I still need to worry?
Because the lender is not a party to your divorce agreement. As far as the bank is concerned, both names on the original loan contract remain equally liable until the loan is paid off or formally refinanced. If your ex misses a payment, it hits your credit report just as hard. The only clean resolution is refinancing the joint loan into a single name — the person who keeps the vehicle qualifies individually and the joint obligation is erased.
What is negative equity and how does it complicate vehicle division in a divorce?
Negative equity means the outstanding loan balance exceeds the vehicle's current market value. In a divorce, negative equity is a shared debt that must be allocated — typically the person who keeps the vehicle assumes the debt, but this can be offset against other assets in the settlement. If you are assigned a vehicle with negative equity, refinancing into a new loan on a less expensive vehicle can sometimes make the numbers work better for your new single-income budget.
Does the Canada Child Benefit count as income when applying for a car loan after separation?
Some lenders will count the Canada Child Benefit (CCB) as income, particularly for lower-income applicants. After divorce, your individual net income is typically lower, which can actually increase your CCB amount. Combined with employment income and court-ordered support payments, CCB can meaningfully strengthen your application. Our finance team knows which lenders will count it and will include it in your total income picture.
How quickly can a credit score recover after divorce-related damage in Alberta?
With disciplined action, meaningful recovery happens within 12 to 24 months. The fastest approach: refinance or close joint accounts immediately to stop ongoing damage, then establish individual accounts — an auto loan and a secured credit card create two active tradelines. Six months of on-time payments typically produces a 40 to 80 point improvement. By 18 to 24 months, many customers have moved from deep subprime to near-prime territory.
Can I apply for post-divorce car financing if my separation is not yet legally finalized?
Yes. Many of our applicants are in the middle of the separation process and cannot wait. If you have an interim separation agreement, it helps clarify your financial situation for lenders. If nothing is formalized yet, we submit based on your individual income and current credit profile. The finality of your divorce does not determine your eligibility — your individual finances do.
Related Resources
Related Buyer Guides
These guides cover credit rebuilding, co-applicant decisions, and the approval steps most relevant to borrowers coming out of a separation.
- Divorce Recovery: Rebuilding Your Car Credit After a Split
- Rebuilding After a Consumer Proposal: Month-by-Month Car Plan
- How Long After a Repossession Can You Get a Car Loan in Alberta?
- Apply Alone or With a Co-Applicant: The Credit Math Explained
- How to Dispute a Collection Hurting Your Auto Application
- Common-Law vs Married: How Lenders Treat Your Relationship Status
What Our Customers Say
“If you're looking for a new vehicle or to trade in your old one, Luke is your guy!! Same day we called he had us an approval, and the 1st vehicle he showed us was exactly what we wanted!”
“I honestly can't thank Luke enough. From start to finish he was patient, respectful, transparent, and genuinely cared about helping me find the right vehicle instead of just making a sale.”
“Fast service and the car is in great condition. Good job both Wes and Luke. I'm looking forward to doing business with you guys again soon.”
Cars you could drive home
See all inventory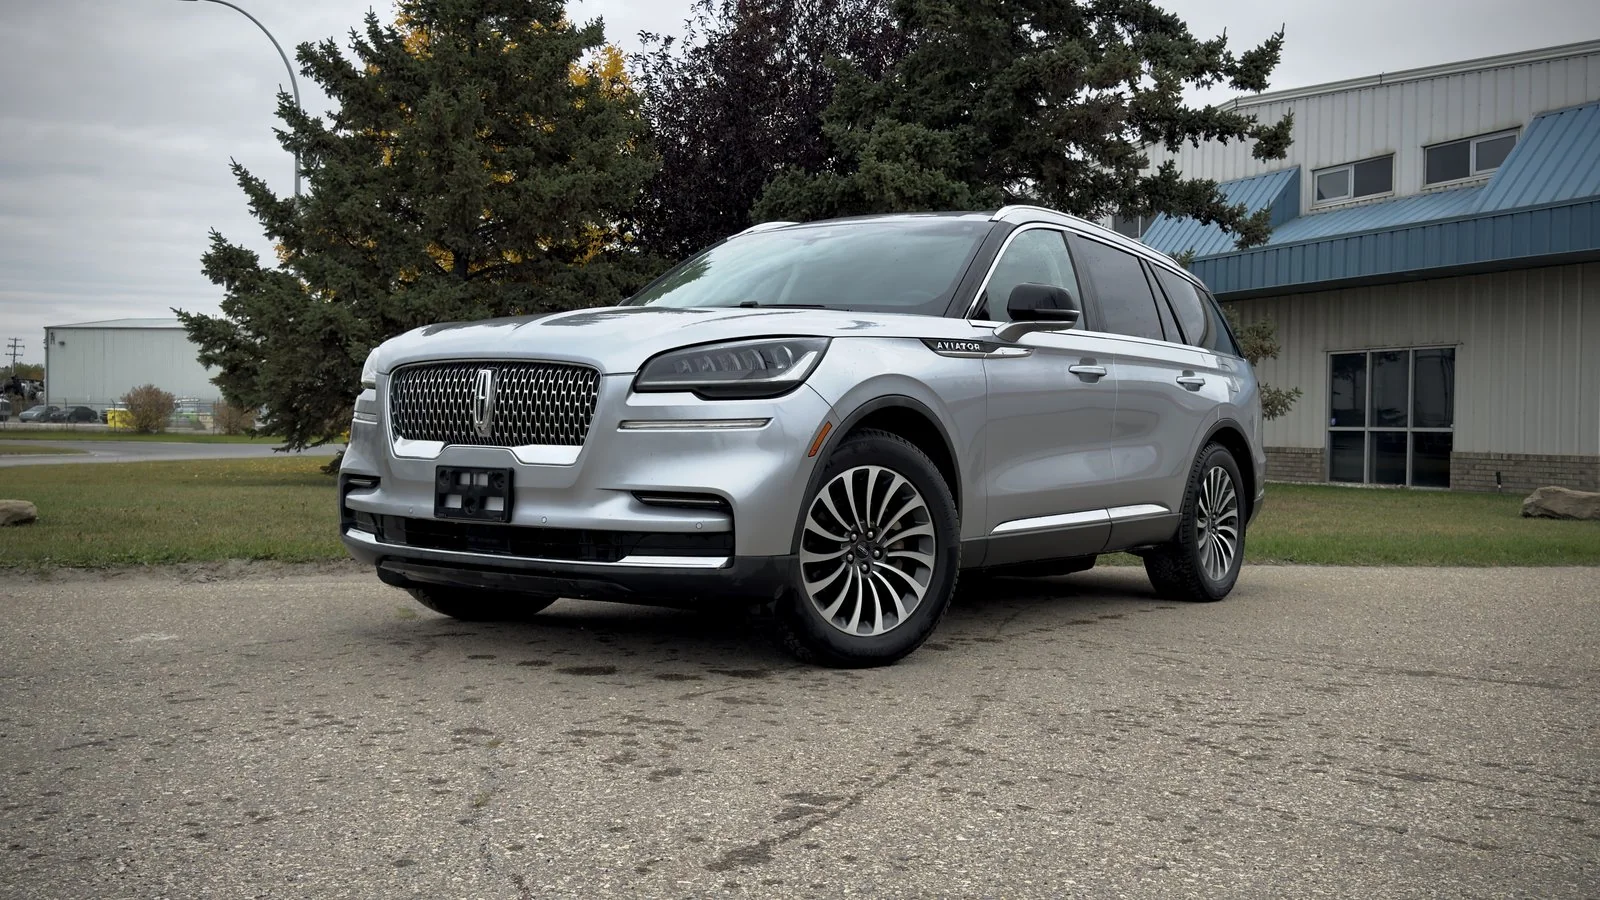
2022 Lincoln Aviator Reserve
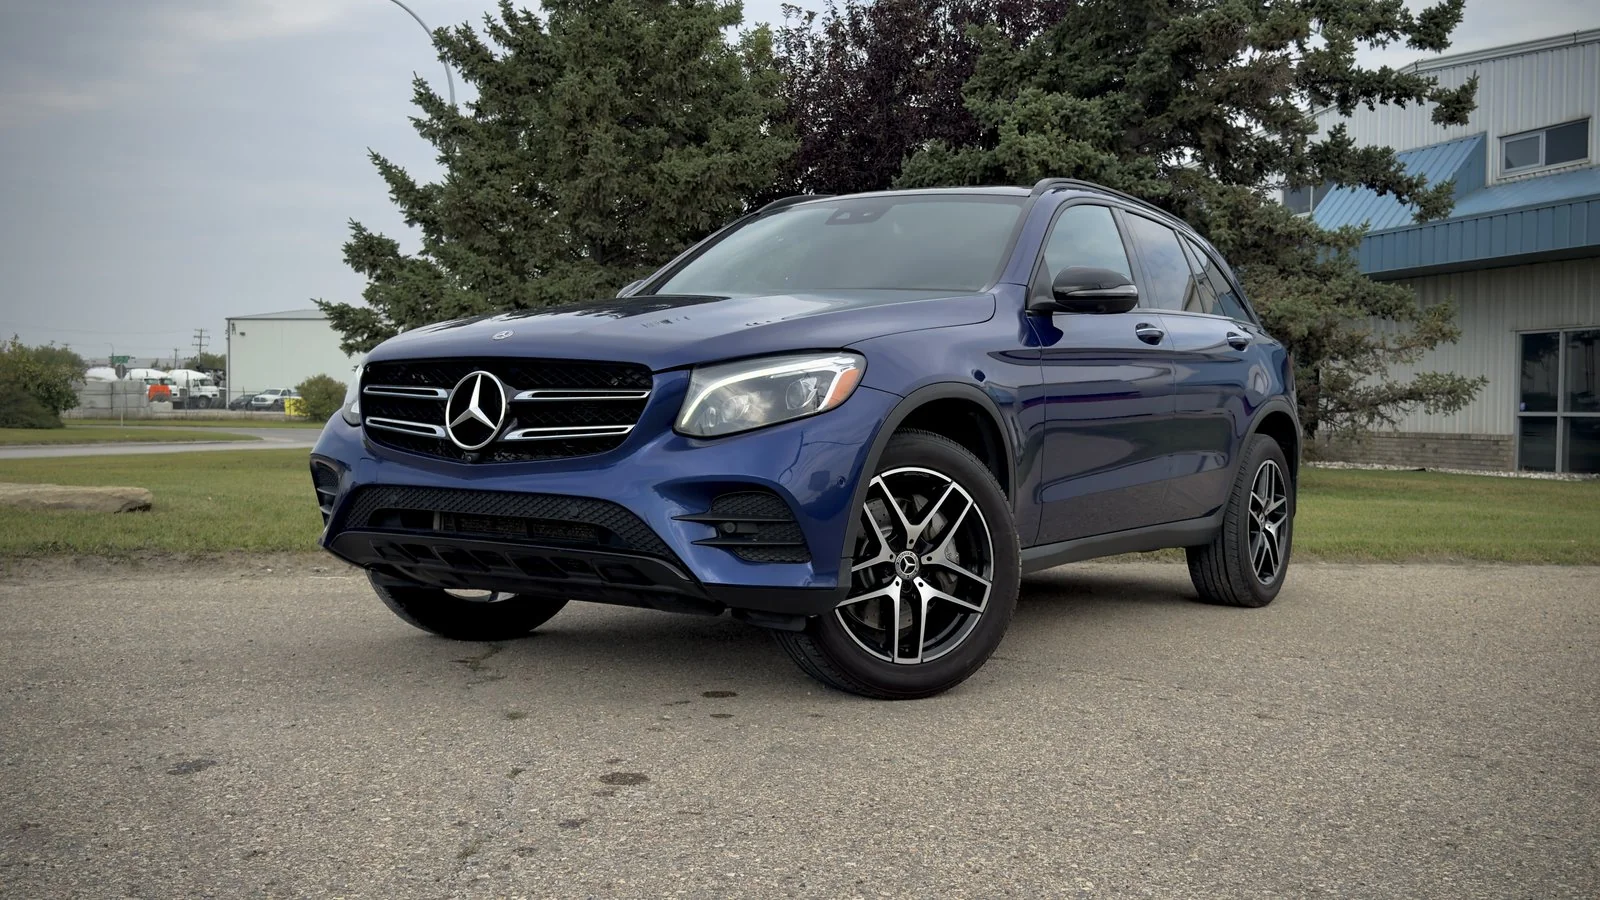
2019 Mercedes-Benz GLC-Class GLC300
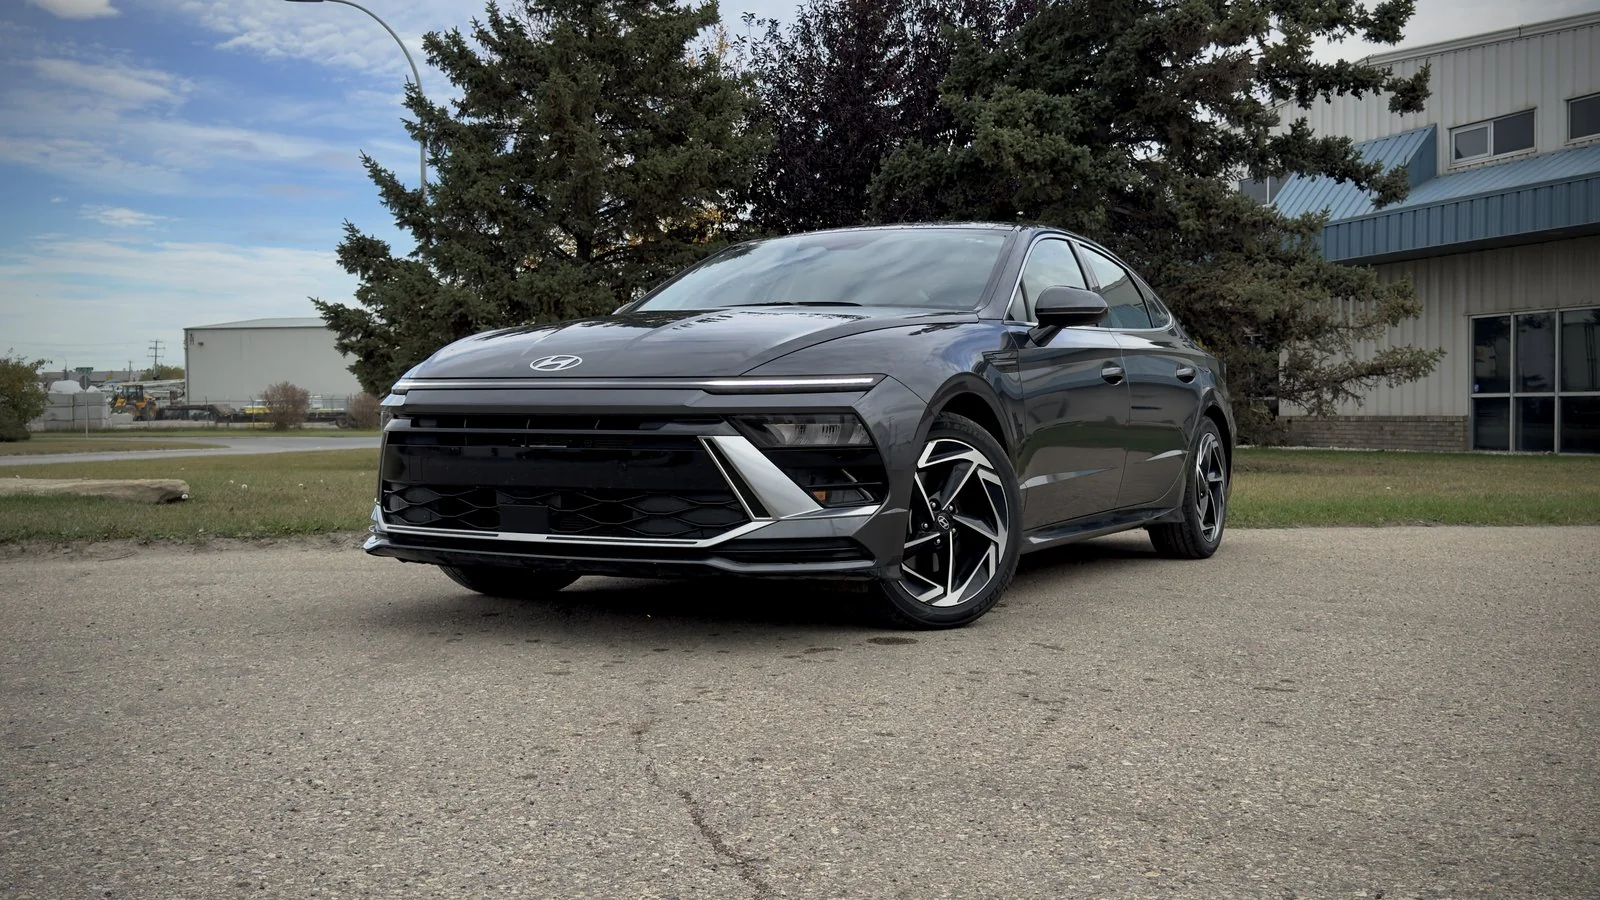
2025 Hyundai Sonata Preferred w/ Trend
2026 Nissan Kicks S
Not seeing it? We'll find it.
We source through our dealer partner network across Western Canada: 25,000+ vehicles to choose from. Tell us what you want and what works for your budget.
Find my car3 min · no credit impactOAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Going Through a Divorce?
Get your own vehicle financing. All credit situations welcome.
5.0121+ Google ReviewsAMVIC LicensedFree Delivery 300km
Ready to Move Forward After Divorce?
Apply online in 3 minutes. No obligation, no judgment — just a straightforward path to the vehicle you need for your next chapter. We serve all of Alberta with free delivery within 300km.