How Much Car Can I Afford in Alberta?
A payment near 15% of your gross pay is a rule of thumb, not a lender rule. Real payment examples, and how to work out your vehicle budget before you shop.
Last reviewed: October 2026
Find Your Actual Payment
We'll tell you exactly what you qualify for. No credit impact.
5.0118+ Google ReviewsAMVIC LicensedFree Delivery 300km
Key Facts
- Budget Rule of Thumb
- 15% of gross monthly pay (pay before tax)
- Not a Lender Rule
- Every lender decides each file
- Typical Loan Range
- $15K–$30K
- Lender Network
- 21+
How Much Car Can I Afford in Alberta?
A payment near 15% of your gross monthly pay (pay before tax) is a common rule of thumb, not a lender rule. On $6,000 a month, that is a payment near $900, before insurance and fuel.
Your rate changes the payment. See what a loan costs by credit tier and the income it usually needs.
The 15% Rule of Thumb for Alberta Buyers
A common rule of thumb: keep your car payment near 15% of your gross monthly pay, which is your pay before tax. It is a guide, not a lender rule. Every lender decides each file and looks at your other debts too. The 15% is the loan payment alone: insurance, fuel and maintenance are extra costs on top, so leave room for them (see the full cost table below).
Alberta has no provincial sales tax on vehicle purchases — only GST (5%). That keeps the tax you pay, or finance, on a vehicle lower than in provinces that add a provincial sales tax.
Income to Vehicle Budget — Alberta Examples
| Annual / Monthly Gross Pay | Payment Near 15% | Example Loan Size | Notes |
|---|---|---|---|
| $40,000 / $3,333 a month | $500 | $22,500–$27,000 | A down payment stretches this budget furthest |
| $55,000 / $4,583 a month | $688 | $30,500–$37,000 | Solid mid-range selection available |
| $70,000 / $5,833 a month | $875 | $39,000–$47,000 | Wider used truck and SUV selection |
| $90,000 / $7,500 a month | $1,125 | $50,500–$60,500 | Certified pre-owned trucks, full-size SUVs |
Pay is before tax. Each payment is 15% of gross monthly pay, a rule of thumb and not a lender rule. Loan sizes are over 72 months with $0 down: the low end at the Subprime example rate (16.9% APR), the high end at the Near-Prime example rate (9.9% APR). Trade-in not included. Example, not an offer. Rates run from 4.99% APR (prime) to 29.9% APR (deep subprime); your rate depends on your file, and every lender decides each file.
What Drives Your Monthly Payment
Vehicle price: the biggest lever
Every $1,000 in vehicle price adds about $17–$27 a month to your payment over 72 months, depending on your rate (the Prime example rate of 6.9% APR to the Deep Subprime example rate of 24.9% APR). Choosing a $22,000 vehicle over a $27,000 vehicle saves about $85–$134 a month, a meaningful difference over a 6-year loan. Example, not an offer.
Interest rate: the silent multiplier
On a $22,000 vehicle over 72 months with $0 down, the Subprime example rate (16.9% APR) costs about $82 a month and about $5,880 more in total interest than the Near-Prime example rate (9.9% APR). Example, not an offer. Your credit score is a big part of what sets your rate. Improving your score before applying — or using a co-signer — can shift you into a meaningfully lower tier. If your credit took a hit, here's how in-house financing works.
Loan term: shorter is cheaper overall
Longer terms (72–84 months) reduce monthly payments but increase total cost. A 60-month term builds equity faster and keeps you ahead of the vehicle's depreciation curve. For bad credit borrowers rebuilding, a 60-month term also means the loan is reported closed sooner — which helps your credit profile. If keeping the payment low matters most, here are low-payment options and the total-cost trade-offs.
Down payment: your most direct budget tool
On a 72-month loan at the Subprime example rate (16.9% APR), a $3,000 down payment lowers your monthly payment by about $67. A $5,000 down payment lowers it by about $111. Down payments also reduce total interest paid, since every dollar down is a dollar that never accrues interest. Example, not an offer.
Planning to buy a home later? A car payment also counts in a mortgage lender's debt ratios.
The Full Cost of Vehicle Ownership in Alberta
Your loan payment is one piece of the ownership cost puzzle. The 15% rule of thumb covers the loan payment only. Alberta buyers also need to budget for the other four cost categories, on top of the payment, before committing.
| Cost Category | Monthly Estimate | Notes |
|---|---|---|
| Loan payment | Near 15% of gross pay | Rule of thumb, not a lender rule; varies by vehicle, rate, term |
| Insurance | $150–$300 | Higher with past claims or bad driving record |
| Fuel | $150–$250 | Based on ~1,500 km/month, average AB gas prices |
| Maintenance reserve | $50–$100 | Amortized oil changes, tires, routine repairs |
| Registration / licence | $11 | ~$130/year in Alberta |
Add the Other Costs on Top
Frequently Asked Questions
What is the 15% rule for car affordability?
It is a rule of thumb, not a lender rule: keep your car payment near 15% of your gross monthly pay, which is your pay before tax. On $6,000 a month gross, that is a payment near $900. The 15% is the loan payment alone. Insurance, fuel and maintenance are extra costs on top, so budget for them separately. Every lender decides each file and looks at your other debts too.
How much car can I afford on a $60,000 salary in Alberta?
A $60,000 salary is about $5,000 a month before tax. At 15% of that, as a rule of thumb, the payment is near $750. Over 72 months with $0 down, that payment repays a loan of about $33,500 at the Subprime example rate (16.9% APR), or about $40,500 at the Near-Prime example rate (9.9% APR). A down payment lets you reach a higher price without raising the payment. Example, not an offer.
Does a down payment help me afford more car?
Yes, directly. Every dollar of down payment reduces the amount financed, which reduces the monthly payment for the same vehicle, or lets you buy a more expensive vehicle at the same payment. A $3,000 down payment on a 72-month loan at the Subprime example rate (16.9% APR) lowers the payment by about $67 a month. Example, not an offer.
Should I extend my loan term to afford a more expensive vehicle?
Extending your term lowers your monthly payment but increases the total interest you pay. Going from 60 to 84 months on a $20,000 loan at the Subprime example rate (16.9% APR, $0 down) lowers the payment by about $88 a month but adds about $4,480 in total interest. The better strategy is usually a less expensive vehicle rather than the longest term. Example, not an offer.
How does bad credit affect how much car I can afford?
Bad credit means a higher interest rate, so more of each payment goes to interest and less to the loan. For the same $750 payment over 72 months with $0 down, the Prime example rate (6.9% APR) repays a loan of about $44,000, and the Subprime example rate (16.9% APR) about $33,500. Moving up even one tier before you buy raises the loan the same payment repays: from Subprime to Near-Prime (9.9% APR) that is about $7,000 more. Example, not an offer.
What other costs should I budget for besides the loan payment?
In Alberta, budget for auto insurance ($150–$300/month depending on vehicle and driving history), fuel ($150–$250/month for an average commuter), maintenance ($50–$100/month averaged) and registration (about $130 a year). Together that is roughly $361–$661 a month on top of your loan payment, and none of it is part of the 15% rule of thumb. Underestimating these is the most common affordability mistake.
One application — 21+ lenders.
We submit your file once and shop every lender that fits your profile, from deep-subprime specialists to prime lenders, including major-bank programs we can access through our lender network.
What Our Customers Say
“Who ever thought you could buy a car online. I was surfing the net looking for a more reliable vehicle when Luke called me with some proposals. Very friendly and straight up.”
“A huge thank you to Wes and Luke for making my vehicle purchase such a great experience. This has been the best experience I've had at a dealership. They were patient, kind, and attentive.”
“Working with Shift Happens was a great experience. Dima and Luke were both professional, friendly, and always quick to respond. They made the process simple and stress-free.”
Cars you could drive home
See all inventory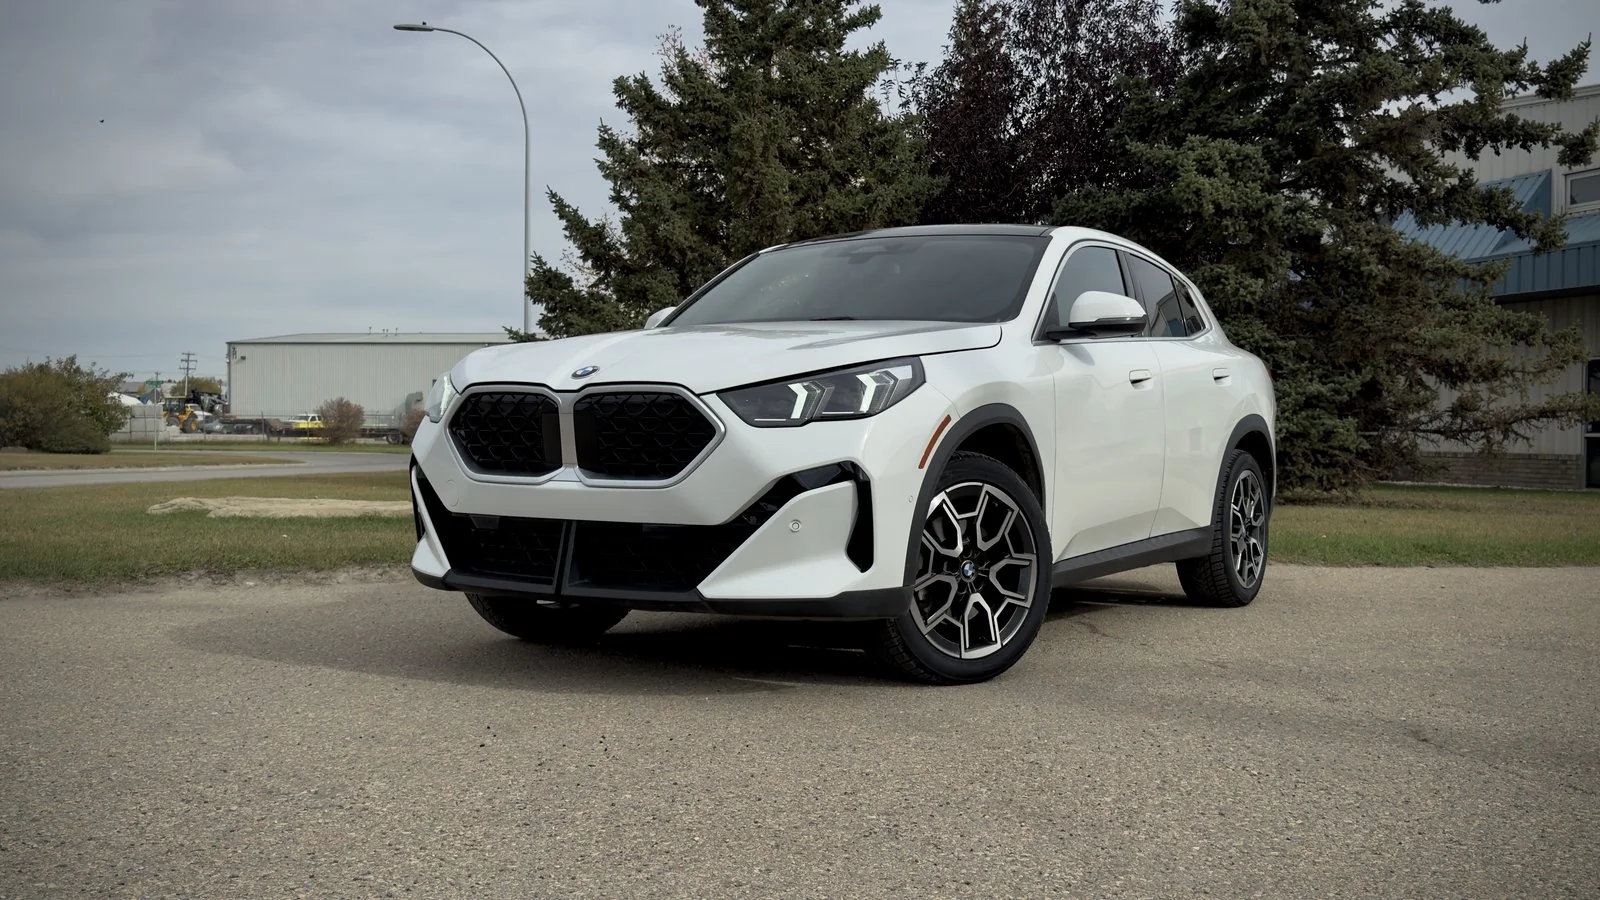
2025 BMW X2 xDrive28i
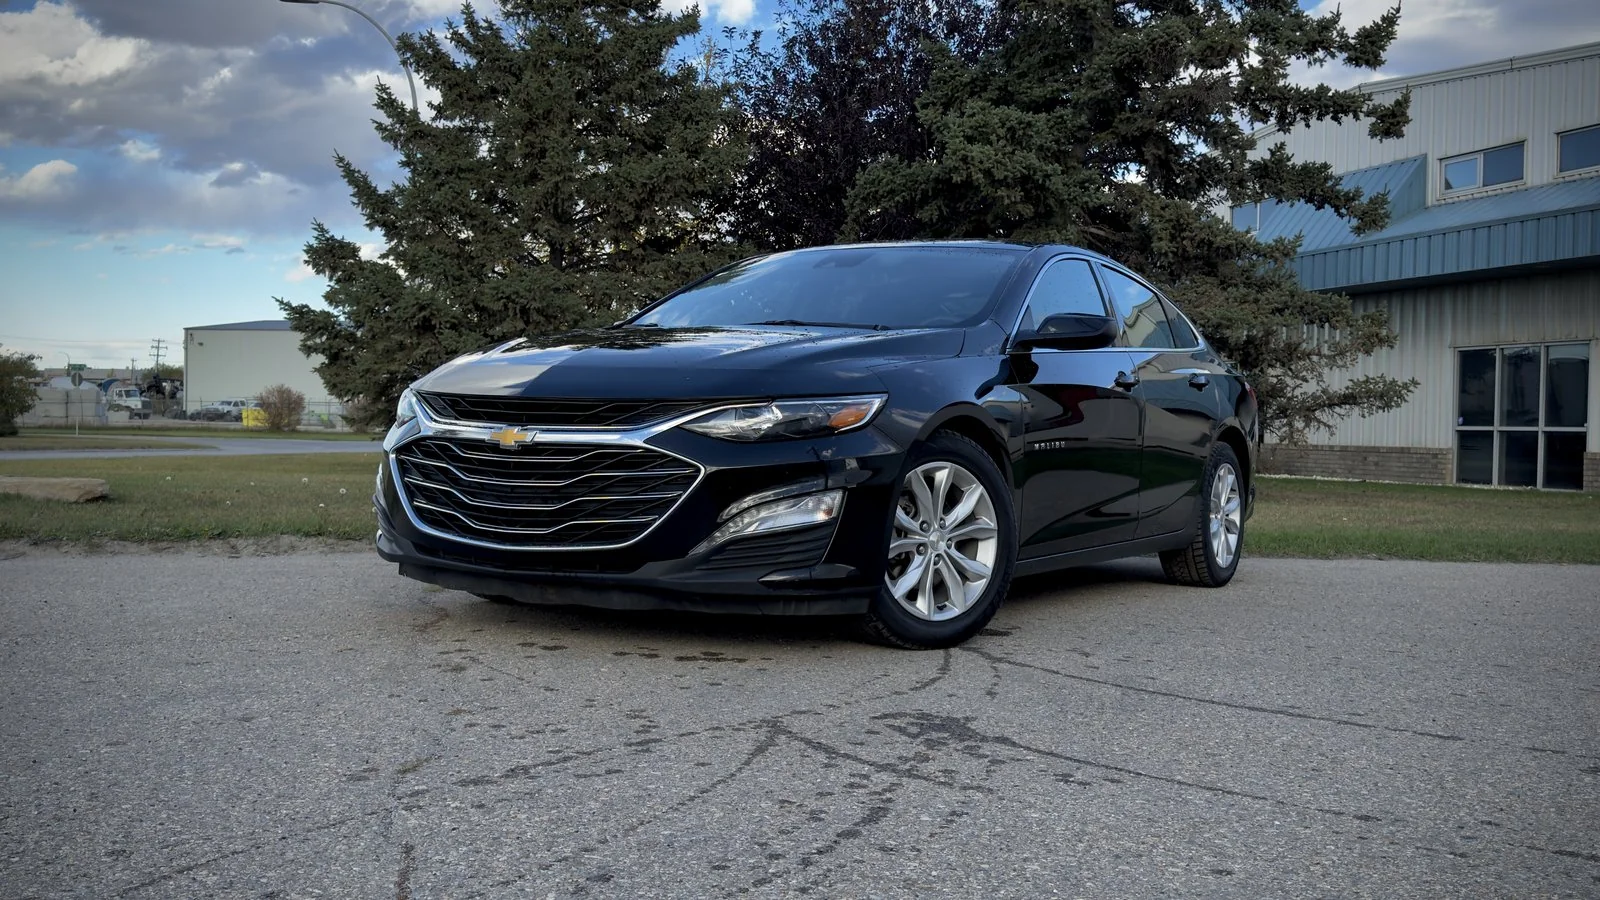
2025 Chevrolet Malibu 1LT
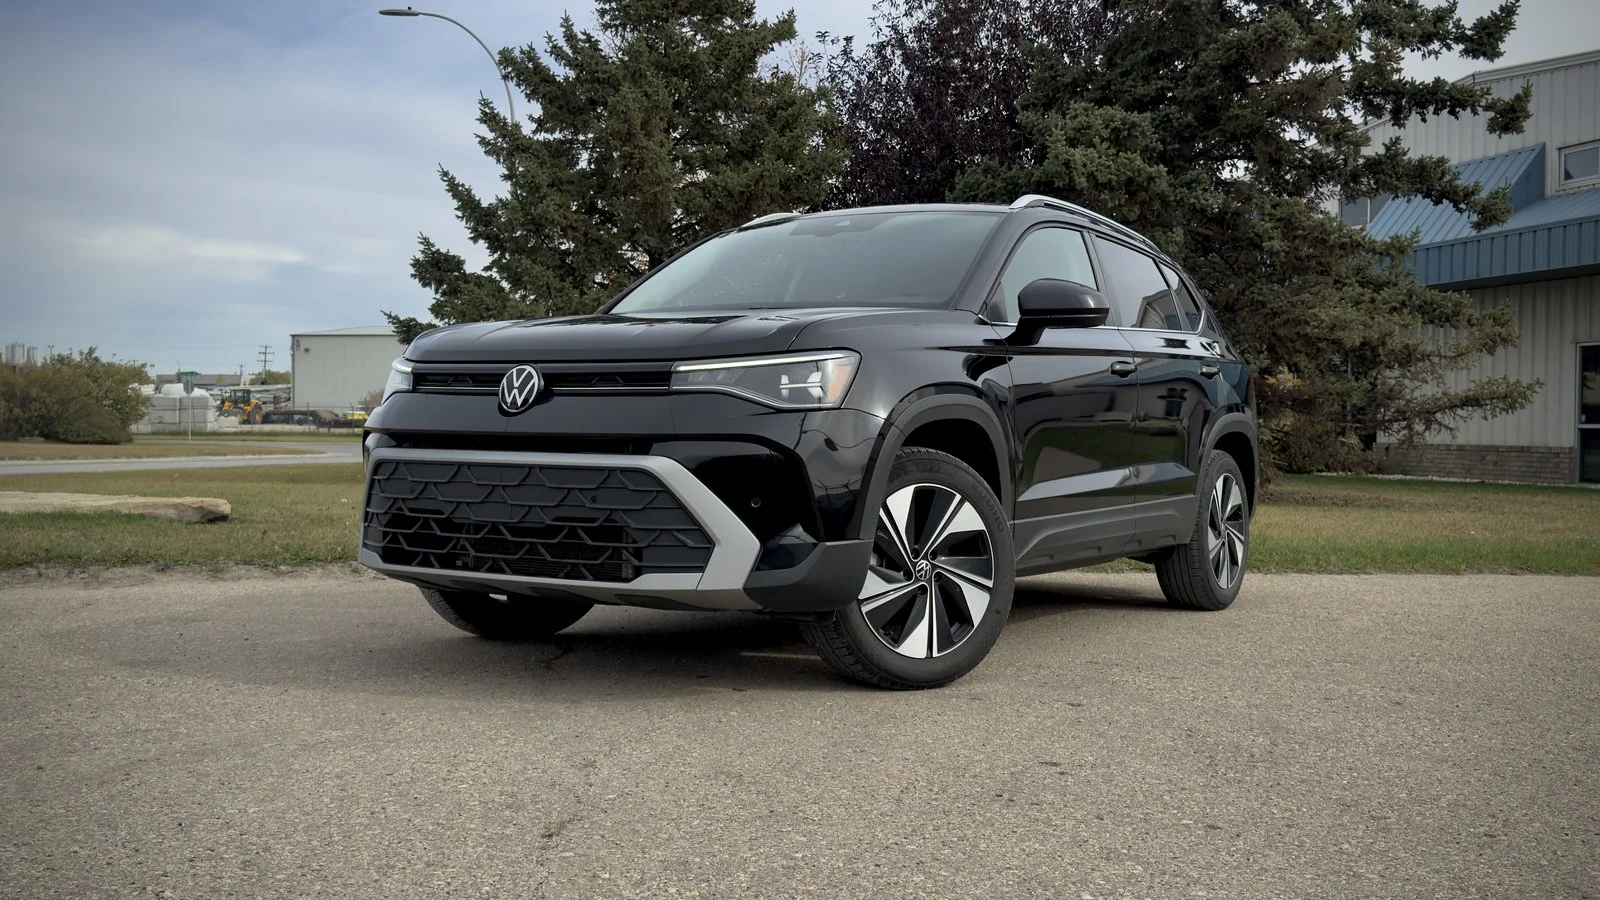
2025 Volkswagen Taos Comfortline
Not seeing it? We'll find it.
We source through our dealer partner network across Western Canada: 25,000+ vehicles to choose from. Tell us what you want and what works for your budget.
Find my car3 min · no credit impactOAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Find Your Actual Payment
We'll tell you exactly what you qualify for. No credit impact.
5.0118+ Google ReviewsAMVIC LicensedFree Delivery 300km
Related Resources
More information on related topics and situations.
See What Fits Your Budget
We'll match you with vehicles in your actual payment range across 21+ lenders, OAC.