Banks Said No? What a Specialty Lender Looks At
In this article
- Banks Said No? What a Specialty Lender Looks At
- Why Banks Reject Bad Credit Auto Loan Applications
- How Subprime Auto Financing Works
- What Credit Score Do You Actually Need?
- Documents You'll Need for Bad Credit Auto Financing
- Tips to Improve Your Chances of Approval
- How Bad Credit Car Loans Help Rebuild Your Credit
- Common Myths About Bad Credit Car Financing
- Ready to Apply?
- Compare and Apply
Check Your Options in 3 Minutes
No credit impact. All credit situations welcome.
5.0118+ Google ReviewsAMVIC LicensedFree Delivery 300km
Banks Said No? What a Specialty Lender Looks At
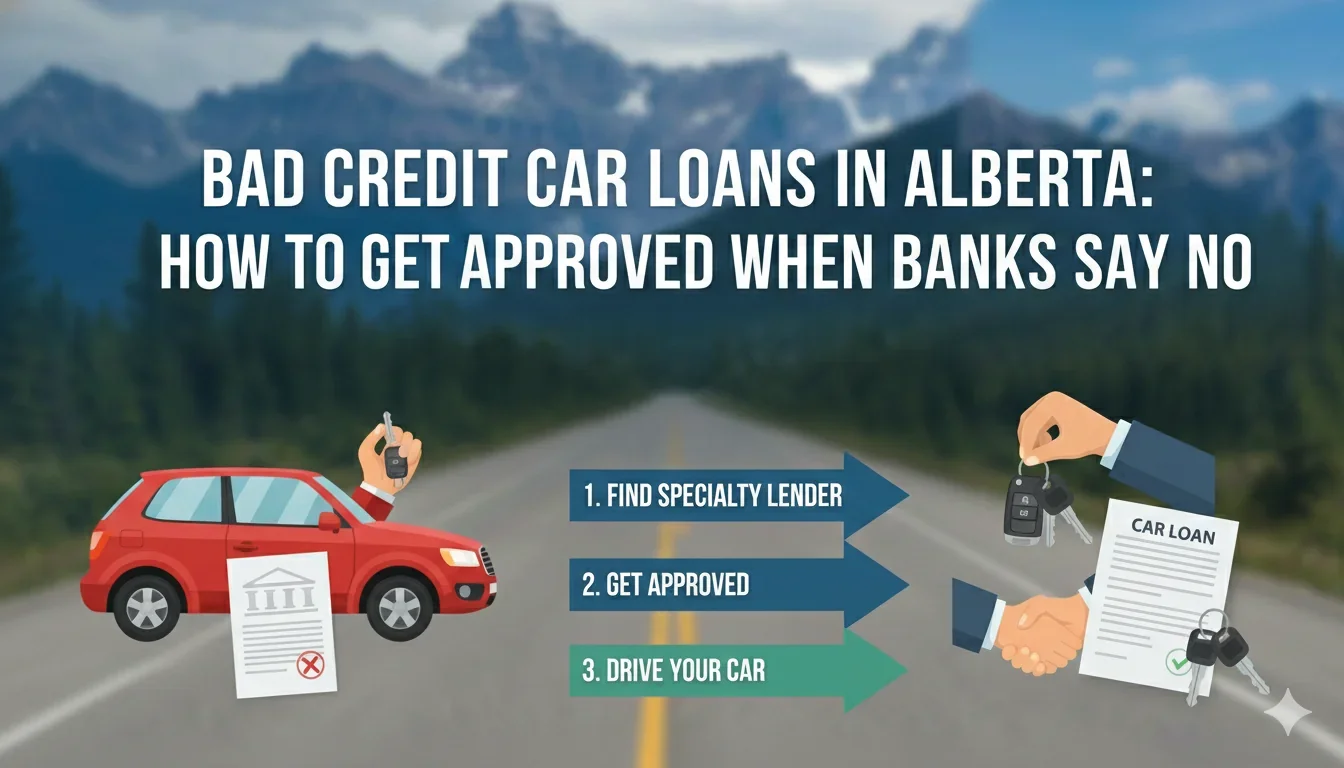
If you've been turned down for a car loan by your bank in Calgary, Edmonton, or anywhere in Alberta, you're not alone. A low credit score doesn't mean you can't finance a quality vehicle: specialty (subprime) lenders exist for people in your situation. If your bank has just declined you, read what to do after a bank declines your car loan, and see how bad credit car loans in Alberta work.
Why Banks Reject Bad Credit Auto Loan Applications
Traditional banks and credit unions in Alberta use rigid approval criteria. If your credit score falls below their threshold — typically 650 or higher — your application gets automatically declined. They don't consider the full picture: your current income, job stability, or the fact that a past financial hardship doesn't define your future ability to make payments.
Common reasons Albertans end up with challenged credit include job loss during economic downturns (something Calgary and Edmonton know well), divorce, medical emergencies, or simply being young and having made some financial mistakes. None of these should permanently prevent you from getting reliable transportation.
How Subprime Auto Financing Works
Subprime lenders specialize in working with borrowers who don't meet traditional lending criteria. Instead of relying solely on your credit score, they evaluate your complete financial picture:
- Current income and employment stability — Can you afford the payments today?
- Down payment amount — Even a small down payment shows commitment
- Time at current job — Stability matters more than salary amount
- Monthly budget — Lenders want you to succeed, not struggle
At Shift Happens Auto Sales in Airdrie, we work with multiple subprime lenders across Alberta. This means we can match your specific situation with the lender most likely to approve you — and at the best rate available for your credit profile.
What Credit Score Do You Actually Need?
Here's the truth: there is no minimum credit score required to apply for financing through a dealership that specializes in challenged credit.
Your interest rate will reflect your credit situation. Rates in our lender programs run 4.99%–29.9% APR, depending on your score, income and down payment. While higher than prime rates, these loans serve a critical purpose: they get you driving and give you the opportunity to rebuild your credit with every on-time payment.
Documents You'll Need for Bad Credit Auto Financing
Having your documents ready speeds up the approval process significantly. Most lenders require:
- Valid Alberta driver's license or government-issued photo ID
- Proof of income — recent pay stubs (last 2-3), or bank statements showing regular deposits
- Proof of address — utility bill, bank statement, or lease agreement
- List of personal references (typically 3-5)
- Void cheque or banking information for payment setup
Self-employed? You can still apply. Bring your last two years of Notice of Assessment from CRA, plus recent bank statements showing business income.
Tips to Improve Your Chances of Approval
1. Be Honest About Your Situation
Lenders check everything. Being upfront about your credit history builds trust and helps your financing specialist find the right lender for your situation. If you have a consumer proposal, a recent bankruptcy, or collections on your file — tell us. We've seen it all and it won't change how we help you. If a bankruptcy is part of your history, this page on car financing after bankruptcy in Alberta explains how lenders view each stage.
2. Save for a Down Payment
Even $500-$1,000 makes a difference. A down payment reduces your loan amount, lowers your monthly payment, and signals to lenders that you're committed. If you have a trade-in vehicle, its value can serve as your down payment.
3. Keep Your Current Job
Lenders love stability. If you've been at your current job for six months or more, you're in a much stronger position than someone who just started. If possible, wait until you've passed the probation period before applying.
4. Choose a Realistic Vehicle
Approval is easier when the loan amount makes sense for your income. A $25,000 vehicle with manageable payments is a smarter choice than stretching for a $45,000 truck that puts your budget under pressure.
How Bad Credit Car Loans Help Rebuild Your Credit
When your lender reports your payments to the credit bureaus (Equifax and TransUnion), each on-time payment adds positive history to your credit report.
After 2-3 years of good payment history, you may qualify to refinance at a lower interest rate, or you'll be in a much stronger position when financing your next vehicle.
Common Myths About Bad Credit Car Financing
"I'll only qualify for junk cars"
False. At Shift Happens, our inventory includes quality pre-owned vehicles from 2015 and newer. Bad credit financing doesn't mean bad vehicles — it means a different lending process.
"The interest rate will be outrageous"
Rates are higher than prime, but they're not predatory. Alberta's consumer protection laws regulate lending practices. Legitimate dealerships work with regulated lenders who follow fair lending standards.
"I need a co-signer"
Not necessarily. While a co-signer can improve your rate, many lenders approve applications based solely on the primary applicant's income and employment.
Ready to Apply?
If you're in Calgary, Edmonton, Airdrie, Red Deer, or anywhere in Alberta and you've been told your credit isn't good enough for a car loan — we'd like to show you otherwise. Our online financing application takes about three minutes. We review every application and call you back.
Over 70% of our customers have credit challenges. You're not alone, and you deserve reliable transportation. Let us help you get there.
Compare and Apply
- Bad Credit Car Loans in Alberta — how lenders look at your whole file, with any credit
- Complete Bad Credit Car Buying Guide (Alberta) — your complete Alberta subprime buyer guide
Financing Resources
Cars you could drive home
See all inventory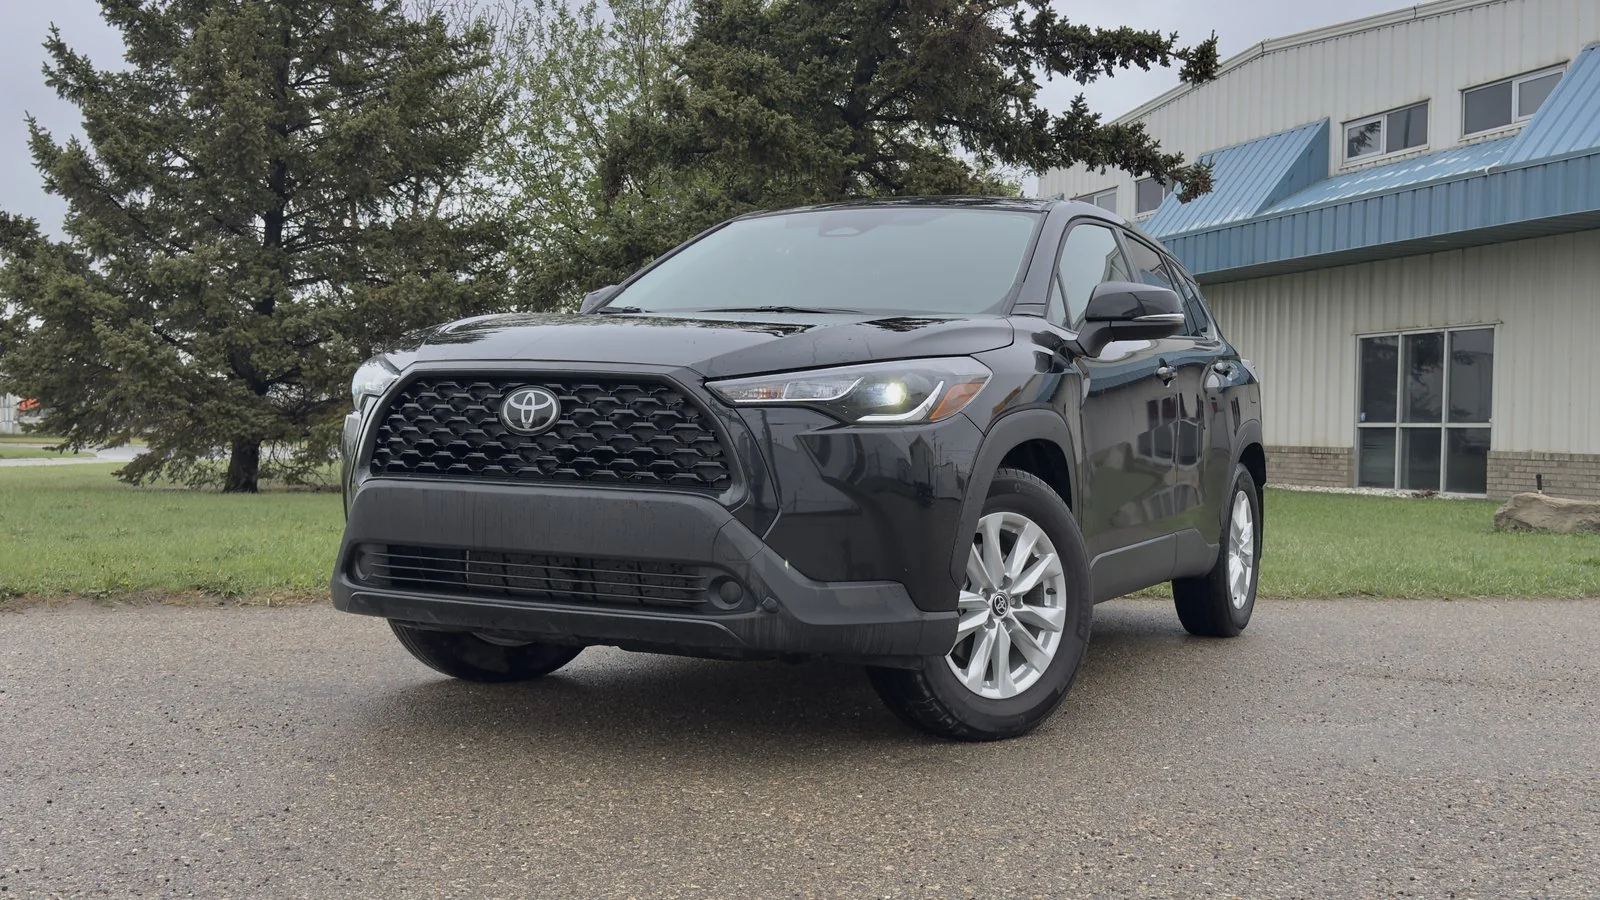
2024 Toyota Corolla Cross LE
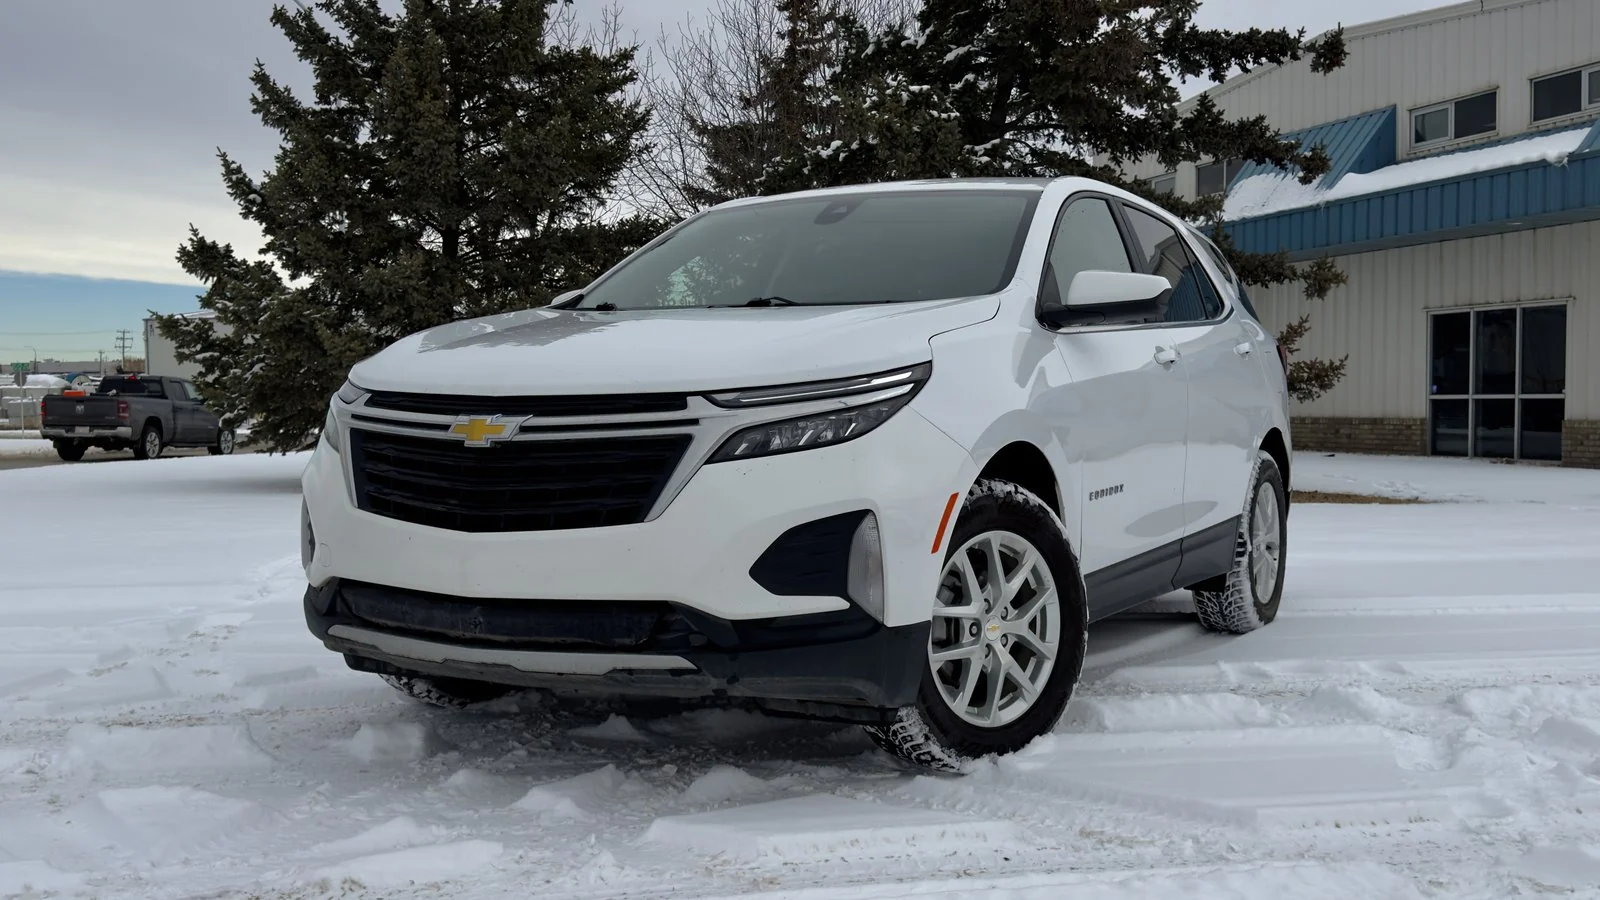
2022 Chevrolet Equinox LT
2020 Mercedes-Benz GLA250 4Matic
Not seeing it? We'll find it.
We source through our dealer partner network across Western Canada: 25,000+ vehicles to choose from. Tell us what you want and what works for your budget.
Find my car3 min · no credit impactOAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Related Articles
Ready to Find Your Vehicle?
Browse our inventory or apply for financing. All credit situations welcome.
5.0118+ Google ReviewsAMVIC LicensedFree Delivery 300km