Car Loan After Repossession in Alberta
A repossession is one of the most stressful financial events a person can go through. We work with all credit situations — including repo — and we do it without judgment.
Last reviewed: October 2026
Can I get a car loan after a repossession in Alberta?
Yes. Shift Happens works with 21++ lenders including specialists for repossession history. Some approve immediately after repo — income and employment stability matter most.
A repossession is a setback, not a dead end.
Had a Repo? You Still Have Options
Many lenders work with repossession history.
5.0121+ Google ReviewsAMVIC LicensedFree Delivery 300km
Key Facts
- Stays on your credit report
- Up to 6 years for late or unpaid loans (Financial Consumer Agency of Canada)
- Approval timing
- Some lenders: immediately
- APR range
- 4.99–29.9%
- Loan amounts
- $5K–$45K
- Down payment
- Improves approval odds
A Repossession Does Not Permanently Disqualify You
What Happens to Your Credit After a Repossession?
A repossession is recorded on your credit report as a derogatory item and typically lowers your credit score by 50–150 points, depending on your starting score and overall credit profile. Information about late or unpaid loans stays on a Canadian credit report for up to 6 years, according to the Financial Consumer Agency of Canada.
Understanding exactly what appears on your report helps you know what lenders are seeing — and how to frame your situation.
What Appears on Your Credit Report
The repossession itself shows as a derogatory account status. The missed payments leading up to the repo are also recorded separately — each missed payment is its own negative mark. If there is a deficiency balance that went to collections, that collection account appears as well. This means a single repossession event can create multiple negative entries, which is why the credit score impact can be significant. Each of these entries carries a rating; see what R8, R9 and I9 mean to a car lender.
How Long a Repossession Stays on Your Report
The Financial Consumer Agency of Canada says information about late or unpaid loans stays on a credit report for up to 6 years. Equifax Canada says negative information generally stays for about 6 years, and it counts a collection account's 6 years from the date of first delinquency (when the account first fell behind). Neither page names repossession, so the dates on your own report are what count. The good news: lenders look at your whole profile, not just this single entry.
How Your Score Recovers
Credit scores begin recovering as soon as you establish new positive payment history. A secured credit card opened the month after your repossession, used responsibly and paid on time, starts generating positive trade lines immediately. A car loan — even at a higher rate — adds an installment account to your profile, which diversifies your credit mix and creates a monthly positive data point. Most people see meaningful score recovery within 12–24 months of consistent positive behaviour, even with the repossession still on their report.
Sources for how long information stays on a credit report (pages opened October 5, 2026): Financial Consumer Agency of Canada: How long information stays on your credit report; Equifax Canada: How long does information stay on your credit report?.
Alberta Repossession Laws — Your Rights Under the PPSA
In Alberta, vehicle repossession is governed by the Personal Property Security Act (PPSA) and the Civil Enforcement Act. You have specific rights that lenders must respect, including notice requirements, the right to redemption, and protections around deficiency balance collection.
Knowing what lenders can and cannot do protects you — and understanding the deficiency balance rules is especially important when applying for a new loan afterward.
The Seizure Process
In Alberta, a lender can repossess a vehicle without a court order once you are in default — typically after one missed payment, though most lenders allow more time and attempt contact first. The lender must use a licensed civil enforcement agency (bailiff). The seizure must be done without a breach of the peace — the bailiff cannot enter a closed garage without your consent and cannot use force. If the vehicle is on private property like a locked garage, the bailiff must get a court order to access it.
Your Right to Redeem
After seizure but before the vehicle is sold, you have the right to redeem — meaning you can pay off the full outstanding balance plus the lender's enforcement costs to get the vehicle back. The lender must give you written notice of the intended sale and an opportunity to redeem. This redemption window is your last chance to keep the vehicle; once it sells, the right expires. If you were in a temporary financial crisis and have since resolved it, the redemption option is worth exploring before the vehicle is listed.
Deficiency Balance — What You Still Owe
If your vehicle sells for less than your outstanding loan balance, you owe the difference — called a deficiency balance. Our glossary explains what a deficiency balance is in Alberta's own legal wording. Alberta lenders must sell the vehicle in a commercially reasonable manner (they cannot dump it at a distressed price to create an inflated deficiency) and must provide you with a written accounting of the sale proceeds and remaining balance. You have the right to dispute the sale process if you believe it was not commercially reasonable. Unresolved deficiency balances often end up in collections, which adds another derogatory entry to your credit report — addressing or settling a deficiency improves your position when applying for new financing. If that debt has grown into a bankruptcy, here is how financing before you're discharged works. If a lender takes the deficiency to court and part of your pay is garnished, here is what a wage garnishment shows on a car loan file.
Surplus Proceeds
If your vehicle sells for more than your outstanding balance, you are entitled to the surplus. This is less common — it typically only happens when the vehicle has significant equity relative to the loan balance — but it is your legal right. If you believe your lender sold your vehicle for proceeds that should have left a surplus, request the written accounting and follow up. The funds belong to you.
How Soon After Repossession Can You Get a Car Loan?
Some lenders will consider your application immediately after a repossession; most prefer 6–12 months of elapsed time combined with positive rebuilding activity. The key variables are your current income, the size of any down payment, and whether any deficiency balance has been addressed.
There is no universal waiting period. Lenders make individual decisions based on your full picture — not just the repossession notation.
Immediately After Repo — Deep Subprime
A small group of deep-subprime lenders will consider applications right after a repossession. These lenders focus almost entirely on current income — typically wanting $2,500+ monthly gross. Expect rates at the higher end of the range and likely a down payment requirement of 15–20%. Vehicle selection matters too: lenders in this tier want reliable, appropriately priced collateral — a $12,000– $20,000 vehicle with solid resale value rather than a $35,000 truck.
6–12 Months Post-Repo — More Lender Options
At the 6–12 month mark, the range of available lenders expands meaningfully. If you have been paying other bills on time, opened a secured credit card, or shown any positive credit activity since the repo, you are a notably better application than someone at day one. Rates are still elevated but lenders at this stage often have more program flexibility — smaller down payment requirements, slightly longer terms.
2+ Years Post-Repo — Near-Prime Territory
With two years of clean payment history since the repossession — especially if you have been making on-time payments on a new car loan — many lenders begin treating your application similarly to other subprime files rather than flagging the repo as a primary concern. This is typically when refinancing becomes viable and when rates begin to approach the mid-teens rather than the high twenties.
What Changes 1, 2 and 3 Years After a Repossession?
Time helps, but what you do with it helps more. A repossession is one dated entry on your credit report, and every month of on-time payments after it is a newer, better one. Here is what usually changes at 12, 24 and 36 months of clean payment history.
These are patterns we see, not promises. Every lender decides each file, and your income, your down payment and any deficiency balance still matter at every stage. The repossession can stay on your report for up to 6 years, so each of these milestones happens while it is still there.
The Repossession Is No Longer the Newest Thing in Your File
What usually changes. A full year of on-time payments is the first thing a new lender can point to. The repossession is still on your report, but it now sits beside twelve months of recent, positive history. In our experience, more lenders will look at your file than in the first months after the repo, and it reads as someone rebuilding rather than someone in trouble. A better rate is usually still too early to count on.
What to do. Keep every payment on time and set up autopay. Order your report from both Equifax and TransUnion, and check the repossession date and any deficiency balance. If you settled a deficiency or set up payments on it, keep the paperwork.
Your Payment Record Starts to Outweigh the Repossession
What usually changes. Two years of on-time payments, usually with steady income over the same stretch, is the point where many lenders weigh your recent record more than the single event behind it. It is often the time to ask whether the loan you are paying could be refinanced at a better rate. Whether it can depends on your score, your income and the car, and every lender decides each file.
What to do. Ask about refinancing your car loan and compare your current rate with the tiers on our car loan rates page. Bring your payment record and your recent pay stubs.
The Repossession Is Old News Next to Your Recent History
What usually changes. Three years of payments, more time with your employer and a repossession that is well behind you give a lender a lot to look at. In our experience, this is when more choices open up on your next vehicle and a lower rate becomes more realistic. A lender will still see the repossession while it is on your report, and each lender decides each file.
What to do. Bring three years of proof: pay stubs, bank statements and your payment record. If your loan is paid down, find out what your car is worth before you shop, since a trade-in can count toward the next one.
Why the clean months count for so much: the Financial Consumer Agency of Canada says your payment history is “the most important part of your credit score.” It is the part of your file you control. For more on how the months add up, see our credit rebuilding timeline.
Source (page opened October 5, 2026): Financial Consumer Agency of Canada: Improving your credit score.
How to Rebuild Your Credit After a Repossession
The most effective credit rebuild strategies after a repossession are: securing a new installment loan (a car loan), opening a secured credit card, paying every bill on time, and addressing any outstanding deficiency balance — in roughly that order of impact.
Recovery is not passive. Waiting for time to pass without adding new positive data to your file is the slowest path. Our customers in Airdrie and Calgary who take deliberate steps after a repo typically see meaningful improvement within 12–18 months. Here is how to accelerate it — starting with second chance financing, which is specifically designed for situations like yours:
Step 1 — Address the Deficiency Balance if You Can
If your lender is pursuing a deficiency balance, this is worth addressing before applying for new credit. It does not have to be paid in full — lenders will sometimes negotiate a settlement for less. Even a formal payment arrangement (showing intent to resolve it) improves how you look to a new lender. An outstanding deficiency sent to collections adds another negative mark and can complicate new financing applications.
Step 2 — Open a Secured Credit Card
A secured credit card — typically requiring a $500–$1,000 deposit at your bank — is the simplest way to start generating new positive trade lines. Use it for small recurring purchases (gas, groceries) and pay the full balance every month. After 3–6 months of on-time payments, your credit profile begins to look like someone actively rebuilding, not someone frozen in a past event.
Step 3 — Get a Car Loan and Pay It Perfectly
An installment loan (like a car loan) is the most powerful credit rebuilding tool available. It adds a different account type from a credit card, demonstrates that you can manage larger payment obligations, and generates a monthly positive data point for 3–7 years. Every single on-time payment is a counter-narrative to the repossession notation. After 12–18 months of perfect payments, the repo starts to look like history rather than your current reality to lenders.
Step 4 — Never Miss Another Payment
This sounds obvious, but it is the single most important rule. A second missed payment or default after a repossession signals a pattern rather than a setback — and it resets the recovery clock. Set up autopay. Build a small emergency fund. If you sense a payment is at risk, contact your lender proactively — most lenders have hardship programs for customers who reach out before they miss a payment.
Step 5 — Monitor Your Credit Report
Pull your credit report from both Equifax and TransUnion every 6 months (free through their respective websites in Canada). Verify the repossession date is accurate, check that on-time payments are being reported correctly, and dispute any errors in writing. A credit bureau dispute is free and errors in your favour can produce an immediate score improvement. Knowing exactly what your report says also helps you explain your situation clearly to lenders.
Steps to Get a Car Loan After Repossession
The process for financing a vehicle after a repossession follows the same basic path as any car loan application — but the documentation requirements are higher and the lender pool is smaller, which is why working with a dealer who has access to multiple subprime lenders matters.
Gather Your Documentation
Lenders processing post-repo applications want to see: government-issued photo ID, your two most recent pay stubs (or 3 months of bank statements if self-employed), proof of residence (utility bill or lease agreement dated within 60 days), and ideally a letter of employment confirming your position and tenure. If you have settled or arranged payment on the deficiency balance, any documentation of that arrangement is worth including. The stronger your documentation package, the fewer questions the lender needs to ask.
Determine Your Down Payment
Assess honestly how much you can put down. Even a small down payment — $500 to $1,000 — demonstrates skin in the game. A larger down payment (10–20%) materially improves approval odds and lowers the loan-to-value ratio, which reduces the lender's risk on the collateral. Trade-in value from a vehicle you own outright can substitute for a cash down payment.
Choose the Right Vehicle
After a repossession, lenders scrutinize the vehicle as collateral more carefully. They want reliable, appropriately valued vehicles — not the most expensive option on the lot. A $15,000–$22,000 practical vehicle with good resale value is easier to finance than a $35,000 pickup on a compromised credit file. Think of the vehicle as part of the application, not just the goal. Choose something the lender can feel confident about as security for the loan.
Apply Through a Subprime-Experienced Dealer
A dealer with relationships across multiple subprime and deep-subprime lenders can submit your application to the lenders most likely to approve your specific situation — rather than sending it to one prime lender who declines it and adds a hard inquiry to your report. We know which lenders work with recent repos, which require 6-month seasoning, and which have strong Alberta programs. That knowledge is what turns a stack of applications into a single targeted submission.
Review and Accept Your Terms
Post-repo rates will be higher than prime. Accept this going in — the rate is temporary. What matters is getting the vehicle, making every payment, and using the loan to rebuild your profile so that in 18–24 months you are in a position to refinance. Understand the full payment schedule, the total cost of credit, and any early prepayment terms before signing. Ask questions. This is a financial commitment you are making to your own recovery — treat it accordingly.
Understanding the Rates — Honest Numbers
Post-repossession car loans in Alberta carry APRs ranging from 14.99% to 29.9% for most applicants, with a small number of strong-income situations qualifying in the 6.99–14.99% range. These rates are temporary — they reflect the risk lenders are taking today, not a permanent judgment on your creditworthiness.
We believe in being upfront about what financing looks like after a repossession. Misleading customers about rates doesn't serve anyone. See our full breakdown of Alberta car loan rates by credit tier for context on where you are starting and where you can realistically reach after 12–18 months of on-time payments.
Rate Range Breakdown
The Refinance Horizon
Most post-repo customers who make every payment on time enter a refinance window at 18–24 months. By that point, your credit score has recovered materially, the repossession is aging off its peak impact, and a new lender sees a clean installment track record. A refinance from 25% APR to 12% APR on a $15,000 balance can reduce your monthly payment by $100–$150. Think of the first loan as the bridge, not the destination.
Loan Terms and Amounts
Our lender network supports loan amounts from $5,000 to $45,000 with terms ranging from 12 to 96 months. For post-repo applicants, a mid-range term (48–72 months) typically balances manageable monthly payments with reasonable total interest cost. Longer terms lower monthly payments but increase total interest — choose based on what you can comfortably service, not just what is technically approved.
How We Help — No Judgment, Just Solutions
We have built relationships with over 21 lenders across the subprime and deep-subprime spectrum specifically so that customers with challenging credit histories — including repossessions — have real options, not just a polite decline.
Repossessions happen. Job losses, divorces, medical events, family crises — the reasons are always human, even when the credit report makes them look like numbers. We have worked with customers who came to us days after a repo, customers who waited years to try again, and everything in between — including those on disability income. We also offer vehicle protection plans to ensure a breakdown does not put you back in the same situation.
We Know Which Lenders Work With Repos
Not every lender does. Sending a post-repo application to the wrong lender wastes time and adds a hard inquiry to your credit report. We know which lenders have specific programs for recent repossessions, which require 6-month seasoning, and which are strongest for Alberta incomes. That knowledge means one targeted submission rather than a scattershot approach that damages your file.
We Present Your Situation Accurately
A lender sees your credit report. We can help put context around it — the circumstances of the repossession, what has changed since, and why you are a different risk today than your score alone suggests. A job letter, a strong pay stub, a reasonable vehicle selection, a modest down payment — these are the details that turn a borderline decline into an approval.
We Do Not Oversell or Apply Pressure
If the deal does not make sense for you financially, we will tell you. A car loan you cannot comfortably service leads to another default, another repossession, and a worse situation than before. We would rather lose a deal than put a customer in a loan that sets them up to fail. We work with all credit situations — that includes being honest when the timing is not right.
Free Delivery Across Alberta
We deliver vehicles up to 300km at no cost. If you are in Calgary, Edmonton, Red Deer, Lethbridge, or anywhere in between, we bring the vehicle to you. After a repossession, you may be without transportation — we close that gap so getting to a lot is not the barrier. In Edmonton? Here are the details on repo financing for Edmonton buyers.
Frequently Asked Questions
Can I get a car loan after a repossession in Alberta?
Yes. A repossession does not permanently prevent you from getting a car loan. Many lenders specialize in exactly this situation. Approval depends primarily on your current income, employment stability, and how long ago the repossession occurred. Some lenders will work with you immediately after a repo; others prefer 6-12 months of recovery time. A down payment significantly improves your odds.
How long does a repossession stay on my credit report in Canada?
The Financial Consumer Agency of Canada says information about late or unpaid loans stays on your credit report for up to 6 years. Equifax Canada says negative information generally stays about 6 years, counted from the date of first delinquency (when the account first fell behind) for accounts sent to collections. Neither names repossession, so the dates on your own report are what count. Lenders look at what has happened since.
How soon after repossession can I get approved for a car loan?
It depends on the lender. A small number of deep-subprime lenders will consider applications immediately after a repossession, provided you have stable income. Most mainstream subprime lenders prefer to see 6-12 months of elapsed time and some rebuilding activity — a secured credit card, on-time bill payments — before approving a new loan. The more time that has passed and the stronger your current income, the more lender options become available to you.
What is a deficiency balance after repossession?
A deficiency balance is the amount you still owe after your lender sells the repossessed vehicle. If your vehicle was sold for less than your outstanding loan balance, you are responsible for the difference. In Alberta, lenders must sell the vehicle in a commercially reasonable manner and provide you with a written accounting. If you have an unresolved deficiency balance, it can affect new loan applications — some lenders will want to see it addressed or at least have a payment arrangement in place before approving new financing.
What interest rate should I expect on a car loan after repossession?
Rates after a repossession are higher than standard market rates. Depending on your current income, time since the repossession, and any new credit activity, you can expect rates in the range of 14.99-29.9% APR. This is temporary — every on-time payment improves your credit profile, and many customers are able to refinance into lower rates after 18-24 months of consistent payments on the new loan.
Does a down payment help after a repossession?
Yes, significantly. A down payment reduces the lender's risk by lowering the loan-to-value ratio on the vehicle. After a repossession, a down payment of 10-20% can be the difference between approval and decline with many lenders. It also reduces your monthly payment and total interest paid over the life of the loan. If you can put together even a modest down payment — $1,000-$3,000 — it meaningfully improves your options.
How soon after a repossession can I finance another vehicle?
There is no mandatory waiting period. Some of our customers have been approved within weeks of a repossession. The key factors are your current income stability, down payment, and whether the repossession balance has been settled or is still outstanding. A settled repo is significantly easier to work around than an active deficiency balance.
What changes at 12, 24 and 36 months after a repossession?
In our experience, more lenders look at your file as the repossession ages and your on-time payments add up. At 12 months the repossession is no longer the newest thing in it. At 24 months it is worth asking about a better rate. At 36 months your recent payment record carries more weight. These are patterns, not promises, and every lender decides each file.
Cars in stock you could finance
See all inventory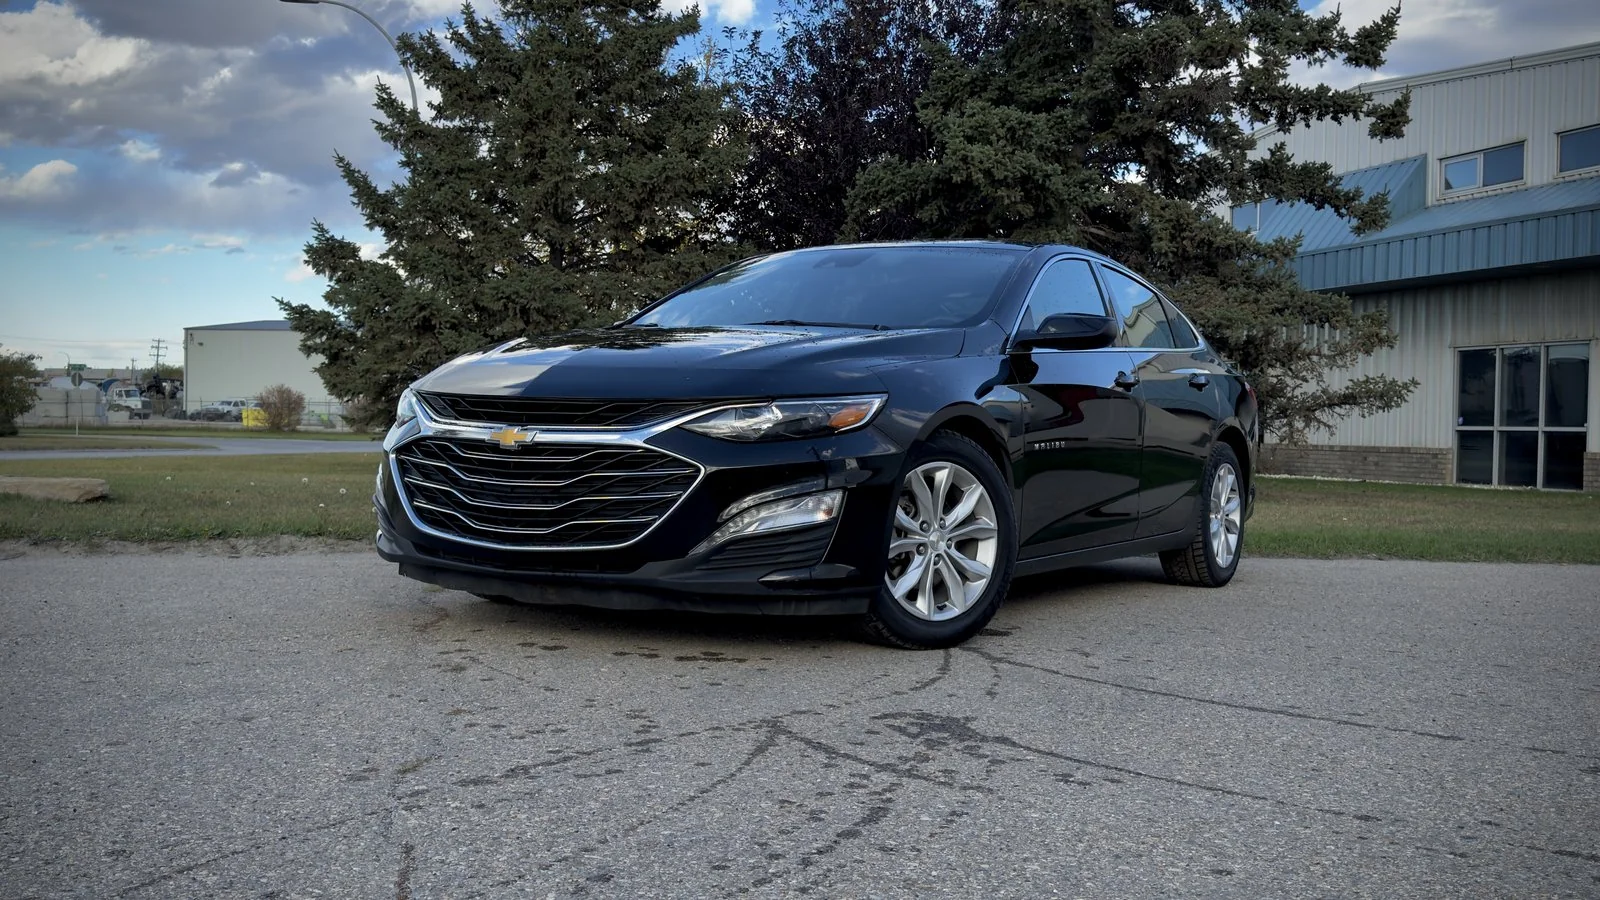
2025 Chevrolet Malibu 1LT
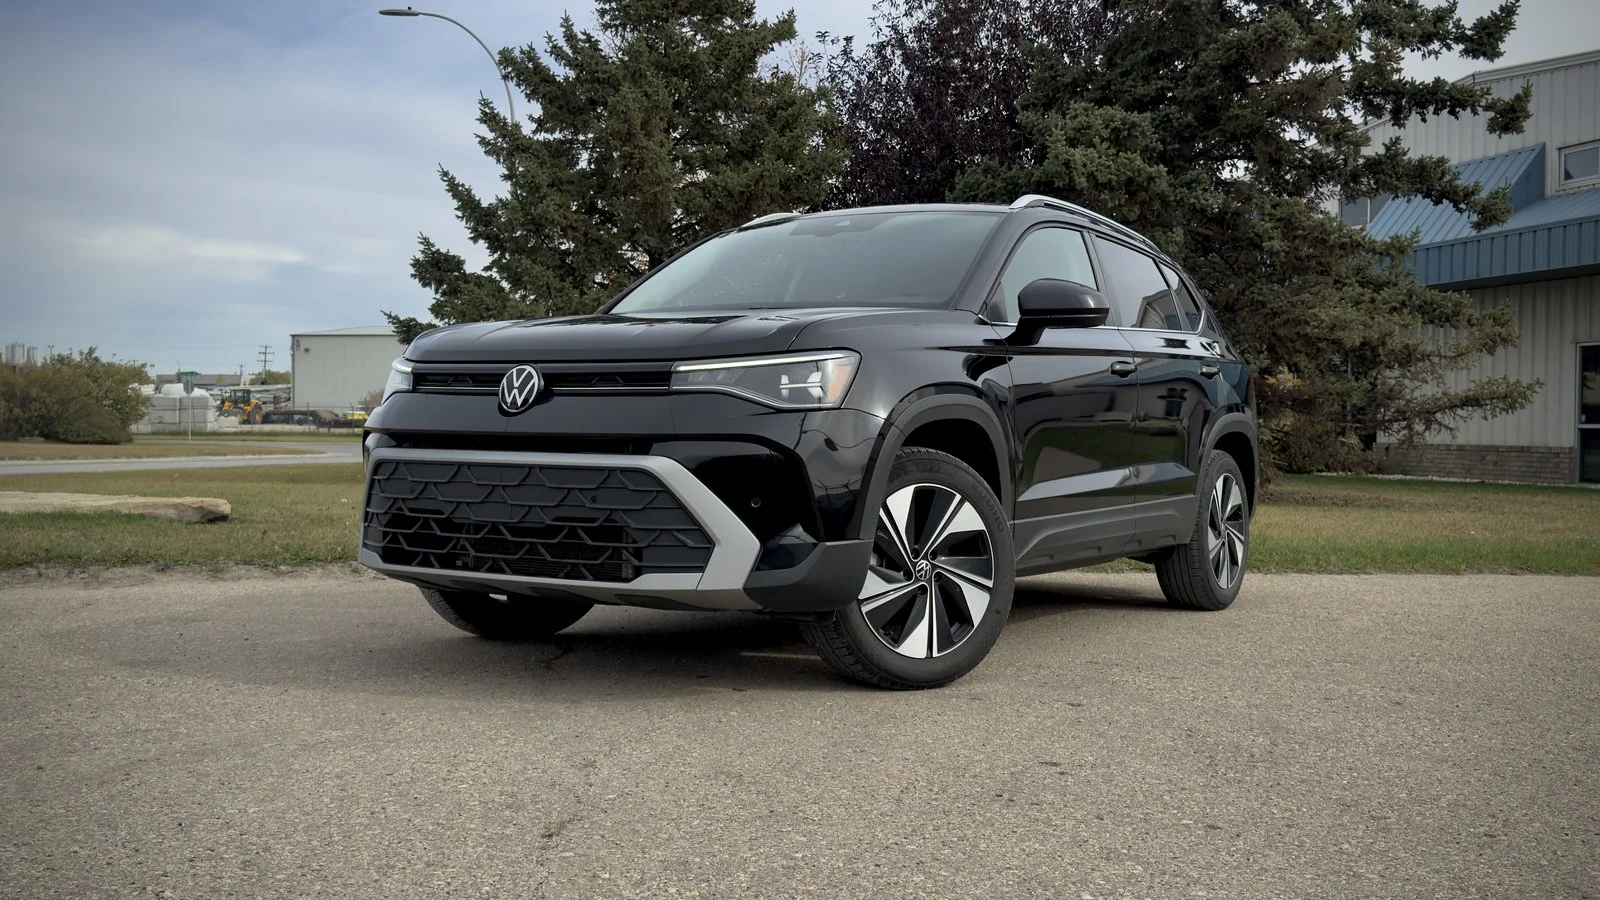
2025 Volkswagen Taos Comfortline
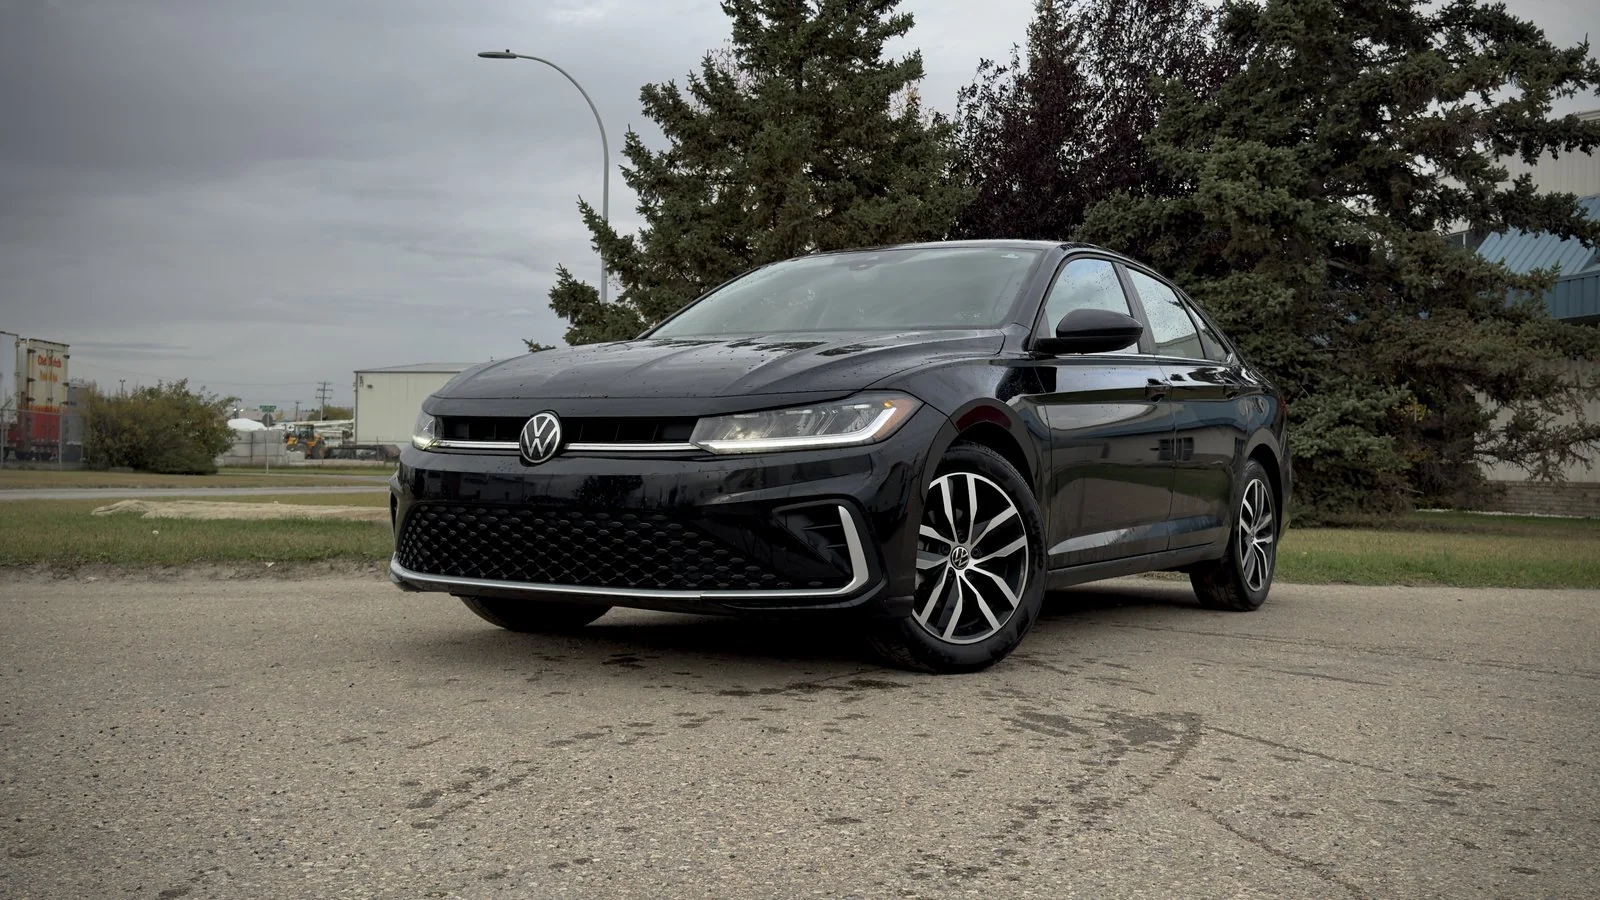
2026 Volkswagen Jetta Comfortline
Not seeing it? We'll find it.
We source through our dealer partner network across Western Canada: 25,000+ vehicles to choose from. Tell us what you want and what works for your budget.
Find my car3 min · no credit impactOAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Related Resources
What Our Customers Say
“A huge thank you to Wes and Luke for making my vehicle purchase such a great experience. This has been the best experience I've had at a dealership. They were patient, kind, and attentive.”
“Thanks to Luke and his team. They were able to find me my dream car and have it delivered between cities. Easy to deal with and easy to work with.”
“Luke was awesome to deal with and made the car buying experience enjoyable again for me and my wife after a few very unpleasant interactions in the past. I would highly recommend.”
Had a Repo? You Still Have Options
Many lenders work with repossession history.
5.0121+ Google ReviewsAMVIC LicensedFree Delivery 300km
Other Financing Options
Ready to Start Over?
A repossession is a chapter, not the ending. We work with all credit situations and we have helped people in exactly your position get back on the road. Apply now — no obligation, no pressure, no judgment.