Car Loan with Collections in Alberta
Millions of Canadians have collection accounts — many don't even know it until they apply for credit. Collections happen for all kinds of reasons: a forgotten gym membership, a missed medical bill, an old phone contract. They do not have to stop you from getting the vehicle you need.
Last reviewed: October 2026
Collections on File? We Can Help
Many lenders look past collections. Check options.
5.0121+ Google ReviewsAMVIC LicensedFree Delivery 300km
Key Facts
- Loan amount range
- $5,000 – $45,000
- Interest rate range
- 4.99% – 29.9% APR
- Loan terms available
- 12 – 96 months
- Collections accepted
- Paid and unpaid considered
- Service area
- All of Alberta
You are not alone in this
Can You Get a Car Loan with Accounts in Collections?
Many people do. Collections are one of the most common credit challenges we see, and they are also one of the most manageable when you apply with the right lenders.
Major banks and credit unions typically decline applicants with open collections because their underwriting models are built for prime borrowers with clean files. That is not a judgment on you — it is a product-market fit problem. Their products are designed for a different customer.
Subprime and non-prime lenders operate on a different framework. They evaluate your current ability to repay — your income, your employment stability, your monthly obligations — alongside your credit history. A collection from four years ago carries far less weight in that framework than a steady paycheque and a reasonable debt-to-income ratio today.
The key factors these lenders consider alongside your collections:
- Monthly income: Stable employment income is the single most important qualifying factor. It overrides a lot of credit history.
- Time at current job: Six months minimum at the same employer signals stability. Two or more years is ideal.
- Debt-to-income ratio: Lenders want your total monthly debt payments — including the new car payment — to stay below roughly 40–45% of gross monthly income.
- Down payment: Even $1,000–$2,000 down reduces lender risk and can be the difference between approval and decline.
- Collection age and amount: Older collections and smaller balances carry less weight. A $200 gym fee from 2020 is not the same as a $6,000 credit card balance from last year.
We match your application to lenders who specifically work with collection-affected files. One application to us reaches 21+ lenders — you do not have to shop around and accumulate credit inquiries on your own. For the complete picture, read our full bad credit financing guide.
Paid vs. Unpaid Collections: What Lenders Actually See
The short answer: paid is better than unpaid, but neither automatically blocks approval. Here is the nuanced picture lenders are actually working from.
Unpaid Collections
An unpaid collection means the debt is still technically outstanding. It affects your credit score, it appears as an open derogatory item, and it increases your total outstanding debt — which lenders count toward your debt-to-income ratio. Lenders are more cautious about unpaid collections because they represent unresolved financial obligations. That said, context matters: a single small unpaid collection from years ago is a very different signal than multiple recent unpaid accounts across several creditors.
Paid Collections
A paid collection shows that you resolved the obligation — which lenders view as a positive character signal. However, paying a collection does not remove it from your credit report. Equifax says it stays until six years from the date of first delinquency, changing from "open" to "paid" or "settled." The credit score improvement from paying varies — sometimes it improves your score, sometimes it has minimal impact if the collection is old. What it reliably does is remove it from your active debt obligations, which improves your debt-to-income ratio immediately.
Settled Collections (Paid for Less Than Full Balance)
Settling a collection for less than the full amount is a legitimate debt resolution strategy. The account will show as "settled" on your credit report, which is slightly less favorable than "paid in full" but significantly better than an open unpaid collection. Many lenders accept settled accounts without issue, particularly when the settlement happened at least 12 months prior to your car loan application.
The Three Factors Lenders Use to Weigh a Collection
Not all collections are equal. Lenders who specialize in non-prime financing evaluate each collection through three lenses before making a decision. Our customers across Airdrie, Calgary, and rural Alberta go through this assessment too.
Age: How Old Is the Collection?
Collections lose impact as they age. A collection that is four or five years old has significantly less weight in a lender's decision than one from 12 months ago. Most specialized lenders use a sliding scale: collections under 12 months old receive the most scrutiny, collections 12–36 months old are given moderate weight, and collections older than three years are often treated as background noise — present but not decisive. If your only collections are old, your application is in a much better position than you might assume.
Amount: How Large Is the Balance?
Lenders apply informal thresholds to collection amounts. Collections under $250–$500 — typical for gym memberships, utility bills, and minor telecom accounts — are often treated as negligible when the rest of the application is strong. Collections in the $500–$2,000 range receive more attention, particularly if unpaid. Collections over $2,000 are the most impactful and lenders may want to see them addressed (paid or settled) before approving, depending on the overall application strength. Large consumer debt collections ($5,000+) require the strongest compensating factors — strong income, stable employment, down payment.
Type: What Kind of Debt Is It?
The origin of a collection tells a story. Medical collections are widely recognized as situational — illness is not a financial character flaw, and lenders know it. Telecom and utility collections are often administrative oversights. Gym memberships and subscription services frequently end up in collections due to contract disputes rather than financial hardship. Credit card and loan defaults are viewed more seriously because they represent a direct borrowing obligation that went unpaid. When we review your file, we prepare context for lenders — the type of collection is part of the story we tell on your behalf.
Common Collections That Appear Without Warning
One of the most common things we hear is: "I didn't even know I had a collection until I applied." It happens constantly. Here are the most common sources — and why specialized lenders understand them.
Medical Bills
One of the most common collections Albertans don't know they have. A missed ambulance fee, a balance after insurance, an out-of-province clinic charge — these can end up in collections without a single warning. Lenders in our network treat medical collections more leniently than most, understanding they rarely reflect financial character.
Telecom & Utility Accounts
Old cell phone contracts, forgotten cable bills, and utility balances from a previous address are extremely common. Many people don't realize these were sent to collections until they pull their credit report. Because these are typically small amounts and are often genuinely overlooked rather than willfully unpaid, specialized lenders view them with appropriate context.
Gym & Subscription Memberships
Gym memberships are notorious for showing up in collections. A cancelled membership that wasn't properly discharged, a forgotten minimum contract term — these small-balance collections have little bearing on your ability to repay a car loan. Lenders who work with non-prime applicants understand this distinction and do not weight gym collections the same as credit card defaults.
Credit Card & Consumer Debt
A credit card or line of credit in collections carries more lender scrutiny than a utility bill, particularly if it is recent or large. However, even consumer debt collections do not automatically block approval. Age, amount, and context matter — and our lender network includes specialists who evaluate the full picture, not just the negative marks.
How Does an Unpaid Ticket or Bill End Up as a Collection Account?
Short answer: a bill can end up in collections. A Calgary parking ticket, by Calgary Parking's own page, does not affect your credit rating, but an unpaid one can still stand in the way of a car.
How a Bill Becomes a Collection Account
When you do not pay a bill, the Financial Consumer Agency of Canada says the company you owe can use its own collections department if it has one, hire a collection agency to collect for it, or sell the debt to an agency. You will usually get a written notice first that names the agency, the company you owe and the amount. It adds that once a creditor sends your debt to a collection agency, your credit score will go down.
Equifax says past-due accounts turned over to a collections agency could also be included in your credit report. It also says your report may not match at the two bureaus, because some lenders report to both, just one, or none at all. On the bureaus' account codes, an account placed for collection is rated 9; see what R9 and I9 mean.
What About a Parking Ticket in Calgary?
Calgary Parking's page says parking tickets do not add demerit points or impact your credit rating. It also says that if you do not pay the fine you are issued a Violation Ticket with a first appearance date. Not paying, or not contacting the Provincial Traffic Court by that date, can lead to a conviction, extra court fees, a licence suspension, and being unable to obtain or renew a vehicle registration or driver's licence until all outstanding fines are paid.
The registration point is the one to clear before you buy a car. The City of Calgary's bylaw-ticket page says you can ask for more time to pay on or before the appearance date, and that missing the date may mean a conviction in your absence or an arrest warrant. The Government of Alberta says it is up to you to check with a registry about your services.
Alberta's Fines Enforcement Program collects unpaid Traffic Safety Act and Criminal Code fines (and no-cash bail forfeitures), and the City says its bylaw tickets are not Traffic Safety Act tickets, such as speeding tickets. The program says it can stop registry services until the debt is fully paid, that it takes 5 to 7 days to get them back once the debt is cleared, and that it can garnish wages. That is a different path from a collection account. If it has reached your pay, see how lenders read a wage garnishment.
A bill from a private company, such as a parking-lot operator, is not covered by Calgary Parking's page. If a company says you owe it money and the account goes unpaid, the steps above apply. If you think the charge is wrong, the consumer agency says to tell the collector, contact the creditor to find out how to correct the error, and check your credit report to see whether the debt appears on it.
What a Lender Sees
A collection account that has been reported shows on your credit report, and the consumer agency says negative information about late or unpaid loans can stay for up to 6 years. A collection can show as an R9 or I9. Here is what those codes mean to a car lender. A registry block is a separate thing from your credit report. It comes up when you try to register or renew a vehicle. Before you apply, read your own report and check each collection against the notice: the agency's name, the amount and the date. Clear or dispute what you can.
Sources (pages opened October 5, 2026): Financial Consumer Agency of Canada: Dealing with a debt collector; Financial Consumer Agency of Canada: How long information stays on your credit report; Equifax Canada: What information is in a credit report?; Calgary Parking: Pay a ticket; City of Calgary: I got a Calgary bylaw ticket. Now what?; Government of Alberta: Fines Enforcement Program. These are public pages, quoted to show what they say. Check the source page before you rely on a detail.
What to Do Before Applying for a Car Loan with Collections
You do not have to have a perfect credit file before applying — but taking these steps can significantly improve your options and the rate you qualify for.
Step 1: Pull Your Own Credit Report
Request free copies of your Equifax and TransUnion reports directly from each bureau: the Financial Consumer Agency of Canada says you can access your credit report online for free from both. Review both — collection accounts sometimes appear on one bureau and not the other. Make a list of every collection: creditor name, amount, date, and current status. Pulling your own report is a soft inquiry and does not affect your score.
Step 2: Dispute Errors — They Are More Common Than You Think
If a collection does not belong to you, the amount is wrong, or the date is inaccurate, dispute it directly with the bureau (Equifax or TransUnion). The Financial Consumer Agency of Canada says credit bureaus must correct errors for free. In Alberta you can also file a written statement of protest: the bureau must use its best efforts to check the information, and your protest goes into every report it gives out about you. A corrected error comes off your report entirely — far better than paying a debt that is not yours.
Step 3: Consider Pay-for-Delete on Active Collections
Before paying any collection, call the collection agency and ask whether they will agree to delete the entry from your credit report upon receipt of payment. Get any agreement in writing before you pay. Many agencies — particularly those holding older debts — will agree, especially if you are offering to pay in full. A deleted collection improves your score more than a paid-but-remaining collection. Note: under Alberta's Limitations Act a payment on an old debt, or an acknowledgment of it that is in writing and signed by you, can restart the limitation period — read Step 4 before you pay or sign anything on a very old debt.
Step 4: Understand the Alberta Limitations Act Before Paying Old Debts
Alberta's Limitations Act provides a two-year window for creditors to sue you for most unsecured debts. If your collection is older than two years and you have not made any payment or acknowledged it in writing, the creditor has lost their right to sue. Making a payment on a time-barred debt can potentially restart the limitation clock. Before paying old collections, understand your rights under Alberta law or consult a non-profit credit counsellor. You can still apply for a car loan while time-barred collections sit on your file — they affect your score, not your legal exposure.
Step 5: Apply With a Specialist, Not Your Bank
If you apply at your bank with collections on your file and get declined, that hard inquiry stays on your report. Applying at a second bank creates a second inquiry — and so on. Multiple hard inquiries in a short period lower your score further and signal desperation to subsequent lenders. A better approach: apply once with a dealer who has relationships with multiple non-prime lenders. Your file goes to the right lenders from the start, typically with a single inquiry, and you get a real answer without damaging your file through trial and error.
Alberta Collection Laws: What You Need to Know
Alberta has specific legislation governing how collection agencies can operate and what rights you have as a debtor. Understanding this context matters before you take any action on outstanding collections.
The Consumer Protection Act and Collection Rules
Alberta's Consumer Protection Act and its Collection and Debt Repayment Practices Regulation govern what collection agencies can and cannot do. Collectors must be licensed in Alberta. They cannot phone or visit you to collect a debt on any day except between 7 a.m. and 10 p.m. They cannot use threatening, profane, or harassing language. They cannot contact your employer except to verify employment, and they cannot contact third parties about your debt without your consent. If a collector violates these rules, you can file a complaint with Service Alberta.
The Two-Year Limitation Period
Alberta's Limitations Act (2000) sets a two-year basic limitation period for most claims, including unsecured debt collection. The clock typically starts from when you last made a payment, last acknowledged the debt in writing, or the creditor discovered (or ought to have discovered) the breach. After two years, the creditor cannot sue you in Alberta court to collect — but the debt remains valid and the collection can still appear on your credit report. The ten-year ultimate limitation period applies to judgments already obtained in court.
Exempt Property in Alberta
If a creditor has obtained a court judgment against you, Alberta's Civil Enforcement Act protects certain property from seizure. Under its Civil Enforcement Regulation, the exemption for one motor vehicle is up to $5,000, and household furnishings and appliances up to $4,000; food and clothing for you and your dependants are covered too. Whether an exemption applies to a vehicle you own is a question for a lawyer.
Credit Bureau Timelines in Alberta
Equifax Canada says a collection account is removed six years from the date of first delinquency on the account (typically when it went to collection). A collection whose first delinquency was in early 2020 comes off your Equifax report in early 2026. This is relevant when planning your financing timeline: if a collection is close to aging off your report naturally, sometimes waiting a few months is a worthwhile strategy. We can help you assess whether that applies to your specific situation.
Sources (pages opened October 6, 2026): Equifax Canada: How long does information stay on my credit report?; Financial Consumer Agency of Canada: Ordering your credit report and score; Financial Consumer Agency of Canada: Checking your credit report for errors; Alberta King's Printer: Limitations Act; Alberta King's Printer: Collection and Debt Repayment Practices Regulation; Alberta King's Printer: Credit and Personal Reports Regulation; Alberta King's Printer: Civil Enforcement Regulation. General information, not legal advice.
How We Help Albertans with Collections Get Approved
We are not just a car dealership — we are a financing intermediary with relationships across a network of 21+ lenders, many of whom specialize specifically in non-prime and collection-affected files. That includes customers with disability income or non-traditional employment. Once approved, we recommend pairing your vehicle with a protection plan to safeguard your payments — and your rebuild. See current Alberta car loan rates to set expectations before applying. Here is what working with us actually looks like.
One Application, 21+ Lenders
You fill out one secure application. We review your file and match it to the lenders most likely to approve it — not the ones most likely to decline it. You avoid the credit score damage of multiple hard inquiries across multiple institutions. One inquiry, the right lenders, a real answer within 24 hours.
We Build Context Around Your Collections
Lenders receive files with context, not just raw credit data. If your collection is a medical bill or a telecom dispute, we note that. If your employment is strong and your income covers the payment comfortably, we lead with that. The story matters — and we know how to tell it in a way that gives lenders confidence in your file.
We Work With What You Have Today
We do not ask you to clean up your entire credit file before applying. If you need a vehicle now — for work, for family, for independence — we help you get approved with your current situation and build a plan from there. An auto loan with consistent payments is itself one of the most effective credit rebuilding tools available.
Free Province-Wide Delivery
Approved and ready to go? We deliver free within 300km of our Airdrie location — covering Calgary, Red Deer, Edmonton corridor, and most of central Alberta. Farther afield? We can arrange delivery province-wide. You should not have to travel hours to pick up your vehicle.
Using a Car Loan to Rebuild Credit After Collections
A car loan is not just transportation — it is a structured credit-building instrument when managed well. Here is what consistent payments on an auto loan actually do to your credit file over time.
The loan opens a new positive tradeline on your credit report. It will not boost your score immediately — new accounts temporarily lower the average age of credit — but it establishes the starting point for a positive payment history. Make every payment on time from day one.
Six months of on-time payments creates a visible positive pattern. Your score typically starts moving upward. The collections that dragged your score down are now being offset by a growing track record of reliable payments. Many customers see 30–60 point improvements in this window.
Twelve to eighteen months of consistent payments is where meaningful score movement happens. The old collections are aging and losing impact. The positive payment history is growing. Customers who start in the 520–580 range often reach 620–650 in this window — the threshold where mainstream lenders start to become accessible again.
With 18 to 24 months of on-time payments and an improving score, refinancing to a lower rate becomes a real option. A rate drop from 24.99% to 14.99% on a $20,000 balance saves thousands over the remaining term. The auto loan you got when you needed it most becomes the vehicle for a much better financial position going forward.
An installment loan like an auto loan is one of the most powerful credit rebuilding tools because it demonstrates payment consistency over time — which is the core of what credit scores measure. Collections age and fade. Positive payment history compounds.
Frequently Asked Questions
Can I get a car loan if I have accounts in collections in Alberta?
Yes. Having accounts in collections does not automatically disqualify you from getting a car loan in Alberta. Many lenders — particularly those who specialize in non-prime financing — look beyond collections to your current income, employment stability, and ability to make consistent payments. The age, amount, and type of collection all factor into how lenders view your application. A small medical bill in collections from three years ago is treated very differently than a recent large credit card default.
Does it matter whether my collection is paid or unpaid?
Yes, it matters — but perhaps not as much as you think. Paid collections are viewed more favorably because they show you resolved the debt, but Equifax says a paid collection still stays on your report until six years from the date of first delinquency. Unpaid collections carry more weight with lenders because the debt is still outstanding and affects your debt-to-income ratio. However, even unpaid collections do not prevent approval with the right lenders. What matters most is the pattern: one unpaid collection from an old gym membership is very different from three unpaid collections from the last 12 months.
What is pay-for-delete and does it help my car loan application?
Pay-for-delete is a negotiation strategy where you offer to pay a collection in full (or settle for less) in exchange for the collection agency agreeing to remove the entry from your credit report entirely. Not all collection agencies will agree, but many will — especially for older debts they have been unable to collect. A successful pay-for-delete removes the negative item rather than just marking it paid, which can improve your score more than simply paying it. If you are planning to apply for car financing, negotiating pay-for-delete in the months before your application can meaningfully strengthen your file.
How long do collections stay on my credit report in Alberta?
Equifax Canada says a collection account is removed six years from the date of first delinquency on the account (typically when it went to collection). If you pay it before then, it stays on your Equifax report, but it may have less of an impact on your score. Before you pay or sign anything on a very old debt, read the limitation-period answer below or talk to a non-profit credit counsellor.
What is the Alberta statute of limitations on collection debts?
Alberta's Limitations Act sets a two-year limitation period for most unsecured debts, including credit cards, lines of credit, and unpaid bills. After two years from the date you last made a payment or acknowledged the debt in writing, the creditor or collection agency can no longer sue you in court to collect the debt. However, the debt does not disappear — it can still appear on your credit report for up to six years. Being past the limitation period does not erase the collection from your credit file, but it does mean the collector has no legal recourse if you choose not to pay.
How much does one collection account lower my credit score?
It depends on the rest of your file. The Financial Consumer Agency of Canada says that once your creditor sends your debt to a collection agency, your credit score will go down, and Equifax says paying a collection may lessen its impact. Consistent on-time payments on your active accounts — including a car loan — add positive history while the collection ages.
Related Resources
What Our Customers Say
“A huge thank you to Wes and Luke for making my vehicle purchase such a great experience. This has been the best experience I've had at a dealership. They were patient, kind, and attentive.”
“Dealt with Luke and Wes. It was one of the best car buying experiences I have ever encountered. I went back to buy another vehicle from these guys as they are just so easy to deal with.”
“The truck is gorgeous and it's exactly what they said it was. I recommend to anyone.”
Cars you could drive home
See all inventory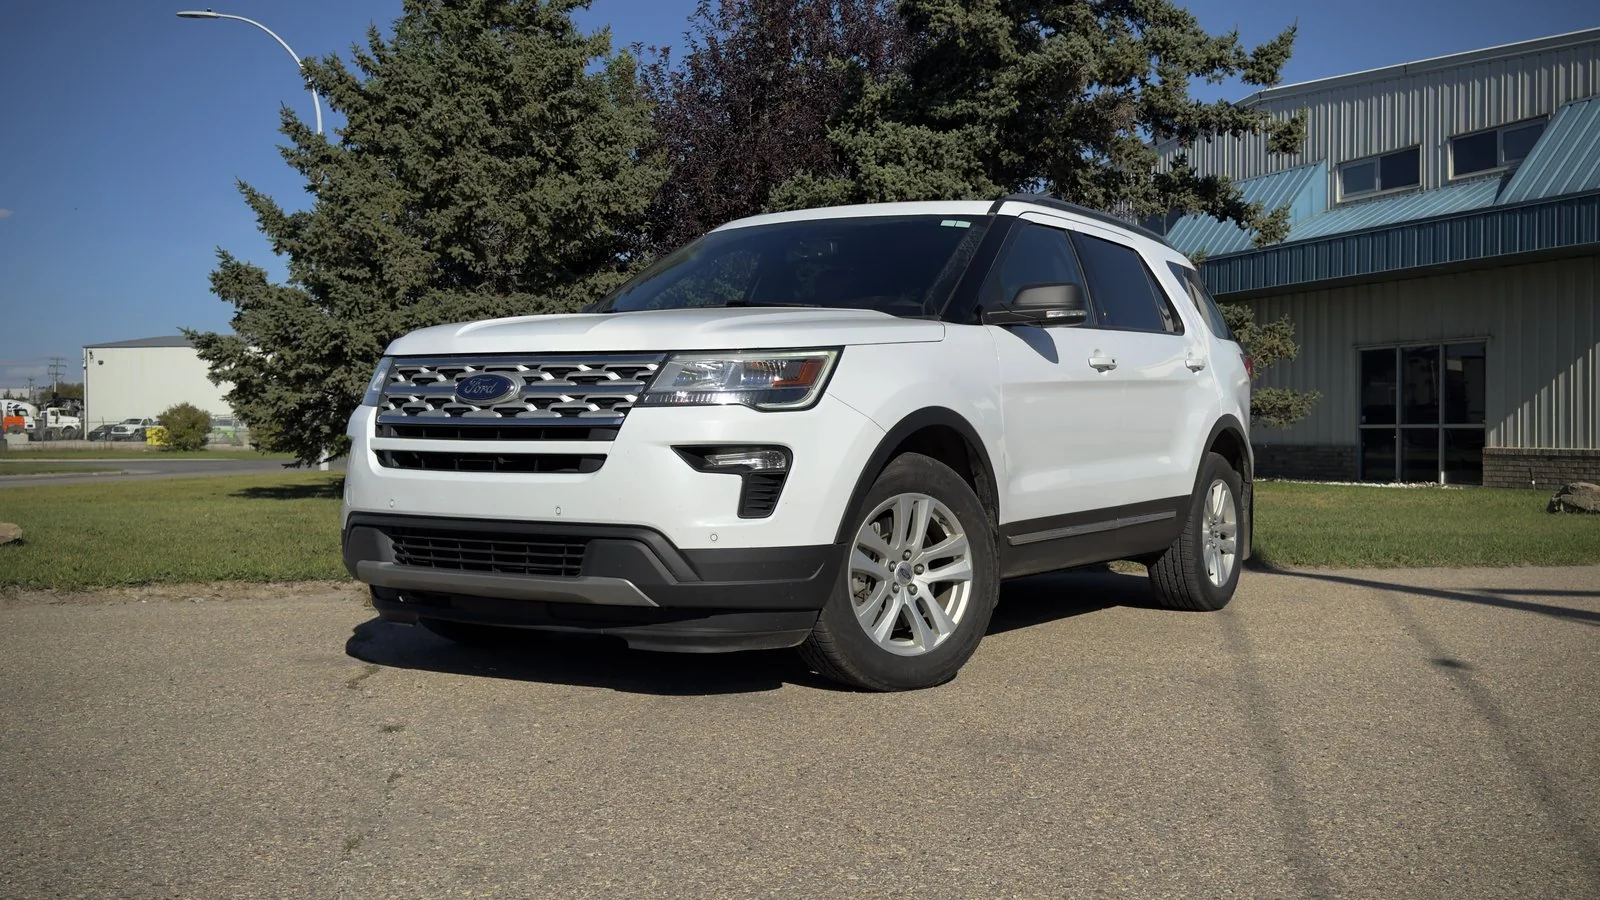
2019 Ford Explorer XLT
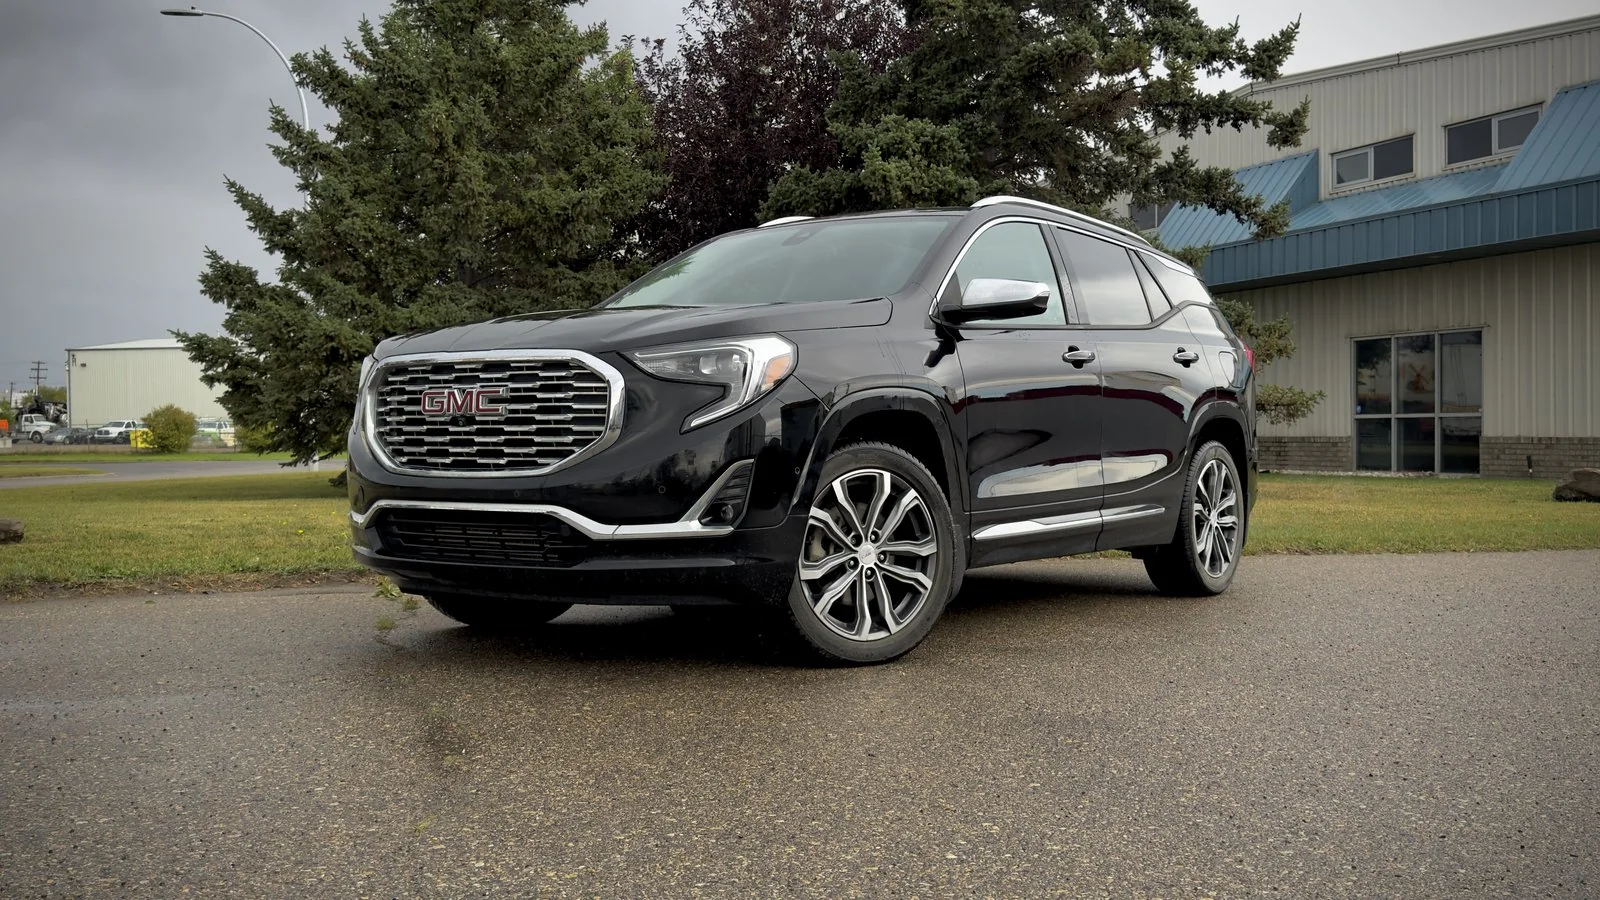
2020 GMC Terrain Denali
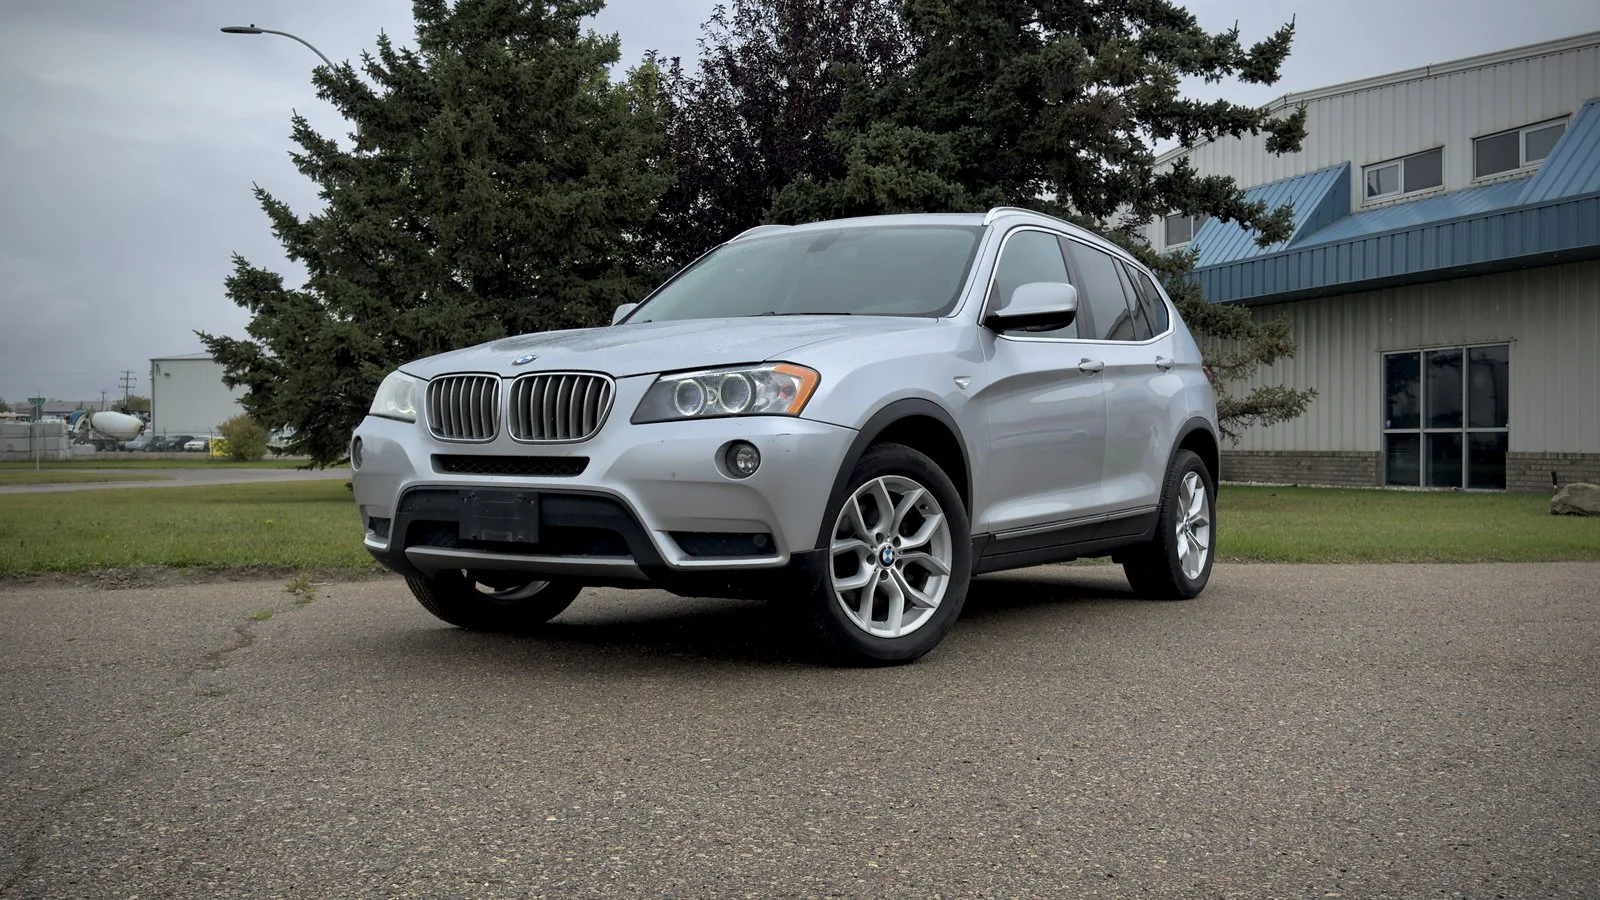
2014 BMW X3 xDrive28i
2025 BMW X2 xDrive28i
Not seeing it? We'll find it.
We source through our dealer partner network across Western Canada: 25,000+ vehicles to choose from. Tell us what you want and what works for your budget.
Find my car3 min · no credit impactOAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Collections on File? We Can Help
Many lenders look past collections. Check options.
5.0121+ Google ReviewsAMVIC LicensedFree Delivery 300km
Other Financing Options
Ready to See What You Qualify For?
Collections do not have to define your financing options. Apply online in 3 minutes — no obligation, no judgment. We work with all credit situations and will give you a clear, honest answer about what approval looks like for your file today. We serve all of Alberta with free delivery within 300km.
AMVIC licensed. No obligation. We work with all credit situations.