Rebuilding After a Consumer Proposal: A Car Plan
In this article
- Can You Get a Car Loan During or After a Consumer Proposal in Alberta?
- What Does a Consumer Proposal Do to Your Credit File?
- How Long Does a Consumer Proposal Stay on Your Credit Report?
- What Should You Do First?
- Can You Buy a Car While the Proposal Is Active?
- What Changes When the Proposal Is Finished?
- How Do You Keep Building Your Credit?
- Is This a Fit for Your Situation?
- Frequently Asked Questions
- How long does a consumer proposal stay on my credit report in Alberta?
- Can I get a car loan during an active consumer proposal, not after?
- Does my Licensed Insolvency Trustee need to approve a car loan during the proposal?
- What's the best vehicle price range for a consumer proposal car loan?
- Can I refinance a proposal-era car loan after the proposal is finished?
- Compare and Apply
Check Your Options in 3 Minutes
No credit impact. All credit situations welcome.
5.0118+ Google ReviewsAMVIC LicensedFree Delivery 300km
You filed a consumer proposal, and your payments go to your Licensed Insolvency Trustee (LIT). Now you need a vehicle. Maybe the old one died, or you are back to steady work. This post covers what a proposal does to your credit file and for how long, what to do first, what lenders usually ask for and what changes once the proposal is finished. Our guide to car loans during a consumer proposal covers the lender side in more detail.
Can You Get a Car Loan During or After a Consumer Proposal in Alberta?
You can apply during a proposal. In our experience, lenders usually ask for your trustee's written consent while the proposal is active, so talk to your trustee first. In our experience, more lenders look at the file after the proposal is finished. Rates follow your score band and the rest of your file, and every lender decides each file. We cannot promise what any lender will decide.
What Does a Consumer Proposal Do to Your Credit File?
The Office of the Superintendent of Bankruptcy (OSB) says a consumer proposal "is a formal, legally binding process that is administered by a Licensed Insolvency Trustee (LIT)," that the term "cannot exceed five years" and that "Payments are made through the LIT, and the LIT uses that money to pay each of your creditors."
On your credit report, Equifax's guide defines rating 7 as "Making regular payments under a consolidation order or similar arrangement." One firm of licensed insolvency trustees says each creditor included in a proposal reports the debt as "included in a proposal" with an R7 rating. Look for it when you read your reports. The same firm adds that creditors sometimes report an included account as "included in a bankruptcy" by mistake, and that if you see this you should ask your trustee for a copy of your proposal documents and dispute it with the bureaus.
How Long Does a Consumer Proposal Stay on Your Credit Report?
The Financial Consumer Agency of Canada (FCAC) says Equifax and TransUnion remove a consumer proposal from your credit report "3 years after you've paid off all the debts included in the proposal, or 6 years after you sign the proposal (whichever comes first)." Equifax says the same. That "whichever comes first" caps it at 6 years from signing. Worked out from that rule:
| If the proposal is paid off | It comes off your report |
|---|---|
| 2 years after you sign | 5 years after you sign |
| 3 years after you sign | 6 years after you sign |
| 4 years after you sign | 6 years after you sign (the 6-year cap comes first) |
| 5 years after you sign | 6 years after you sign (the 6-year cap comes first) |
The table is our arithmetic on FCAC's rule, so check the dates on your own reports. The accounts that were included in the proposal are separate entries. Equifax says a credit account purges "six (6) years from date of last activity."
What Should You Do First?
- Keep every proposal payment on time. The OSB says that if you are making monthly payments and miss three, "the proposal will be deemed annulled." Your creditors can then act to collect.
- Ask your trustee before you take on new credit. Your own proposal paperwork decides what you can do, and we cannot see it.
- If you want to keep a car you already own, keep paying its loan. The OSB says you keep your assets "so long as you make your payments to your secured creditors."
- Get both credit reports. FCAC says you can access your credit report online for free from Canada's 2 main credit bureaus, Equifax and TransUnion. Check how the proposal and each included account are shown.
- Pay every other bill on time. FCAC says payment history is "the most important part of your credit score."
- Consider a small secured credit card. FCAC says one may be an option "if you have bad credit," and that you give the issuer a security deposit. Read the terms for set-up and annual fees first.
Can You Buy a Car While the Proposal Is Active?
You can apply at any time, but each lender decides each file. In our experience, a lender in this spot usually asks for the trustee's written consent, your proposal payment record, proof of income and some money down. We cannot give you numbers for any of those. In our experience, lenders typically look for about $2,800 a month in income you can prove, from all sources combined. If you are under that, talk to us first.
Your rate follows your score band and the rest of your file. Rates in our lender programs run 4.99%–29.9% APR across all tiers. Example, not an offer: a $16,000 loan at 24.9% APR over 60 months is about $216 bi-weekly (about $469 a month). 24.9% is the example rate for our Deep Subprime tier (19.9%–29.9%). A rule of thumb we use is a car payment of about 15% of your gross monthly pay. It is a guide, not a lender rule. At that rule of thumb, the $469 example fits gross pay of about $3,200 a month, before you add your proposal payment to the budget. Ask your trustee whether the payment fits. See what a car loan costs by credit tier for the range in every score band.
What Changes When the Proposal Is Finished?
The OSB says that if you meet the conditions in full, "you will be legally released from the debts included in the proposal." You will receive a certificate of full performance, and the OSB says to send a copy to the major credit-reporting agencies so your credit record is updated. Keep all your proposal documents for future lenders.
In our experience, more lenders look at a file once the proposal is complete, and terms are often better. These are patterns, not promises, and every lender decides each file. The OSB says your ability to get credit after a proposal "depends on convincing lenders of your personal financial maturity and ability to repay the debt," and that "no one is required to give you credit."
If you took a loan during the proposal at a higher rate, it can be worth asking about a lower rate once you have a record of on-time payments. Whether a lender will do it depends on your score, your income and the car. Example, not an offer, to show what a lower rate is worth on the same loan: $16,000 over 60 months at 24.9% is about $216 bi-weekly with about $12,120 in interest. At 16.9%, our Subprime example rate, it is about $183 bi-weekly with about $7,810 in interest, about $4,310 less.
How Do You Keep Building Your Credit?
- Keep your balances low. FCAC says: "Try to use less than 30% of your total credit limit."
- Do not apply for credit you do not need. FCAC says to avoid sending multiple applications at once or too close together.
- Do not chase a mix of accounts. Equifax says credit mix "is generally one of the smaller factors in credit score calculations" and that you should not open credit accounts you do not need.
Our post on consumer proposals in Alberta covers the process from filing to finish.
Is This a Fit for Your Situation?
We sell used vehicles in Alberta and work with buyers whose credit took a hit. If you have steady income and you are in a consumer proposal or have just finished one, we can look at your file. We review every application and call you back. Every lender decides each file, so we cannot promise a result. You can start on our financing application page.
Frequently Asked Questions
How long does a consumer proposal stay on my credit report in Alberta?
FCAC says 3 years after you have paid off all the debts included in the proposal, or 6 years after you sign it, whichever comes first. The accounts included in the proposal have their own dates, so read your own reports.
Can I get a car loan during an active consumer proposal, not after?
You can apply. In our experience, lenders usually want your trustee's consent, a current proposal payment record and proof of income. Every lender decides each file.
Does my Licensed Insolvency Trustee need to approve a car loan during the proposal?
We cannot tell you what your proposal says, so ask your trustee before you apply. In our experience, many lenders ask for the trustee's written consent, and it helps to have it ready.
What's the best vehicle price range for a consumer proposal car loan?
There is no set range. Start from the payment. A rule of thumb we use is a payment of about 15% of your gross monthly pay, and your proposal payment comes out of the same budget. Our affordability calculator shows how price and down payment change the payment. Every lender decides each file.
Can I refinance a proposal-era car loan after the proposal is finished?
Sometimes. It depends on your score, your income, the balance left and the car, and every lender decides each file. We cannot promise it. The example above shows what a lower rate is worth on the same loan.
Compare and Apply
- Complete Bad Credit Car Buying Guide (Alberta) — step-by-step guide to bad credit car buying in Alberta
Sources (pages opened October 6, 2026): Financial Consumer Agency of Canada: How long information stays on your credit report, Getting your credit report and credit score, Improving your credit score, Choosing a credit card; Equifax Canada: Consumer Credit Report User Guide (PDF), How long does information stay on your credit report?, How to dispute information on your credit report, What is a credit mix?; Office of the Superintendent of Bankruptcy: Consumer proposals, Consumed by debt?; Licensed insolvency trustees: Hoyes, Michalos & Associates: How does a consumer proposal affect your credit rating?. These are public pages, quoted to show what they say. Check the source page before you rely on a detail. This is general information, not legal advice.
Financing Resources
Cars you could drive home
See all inventory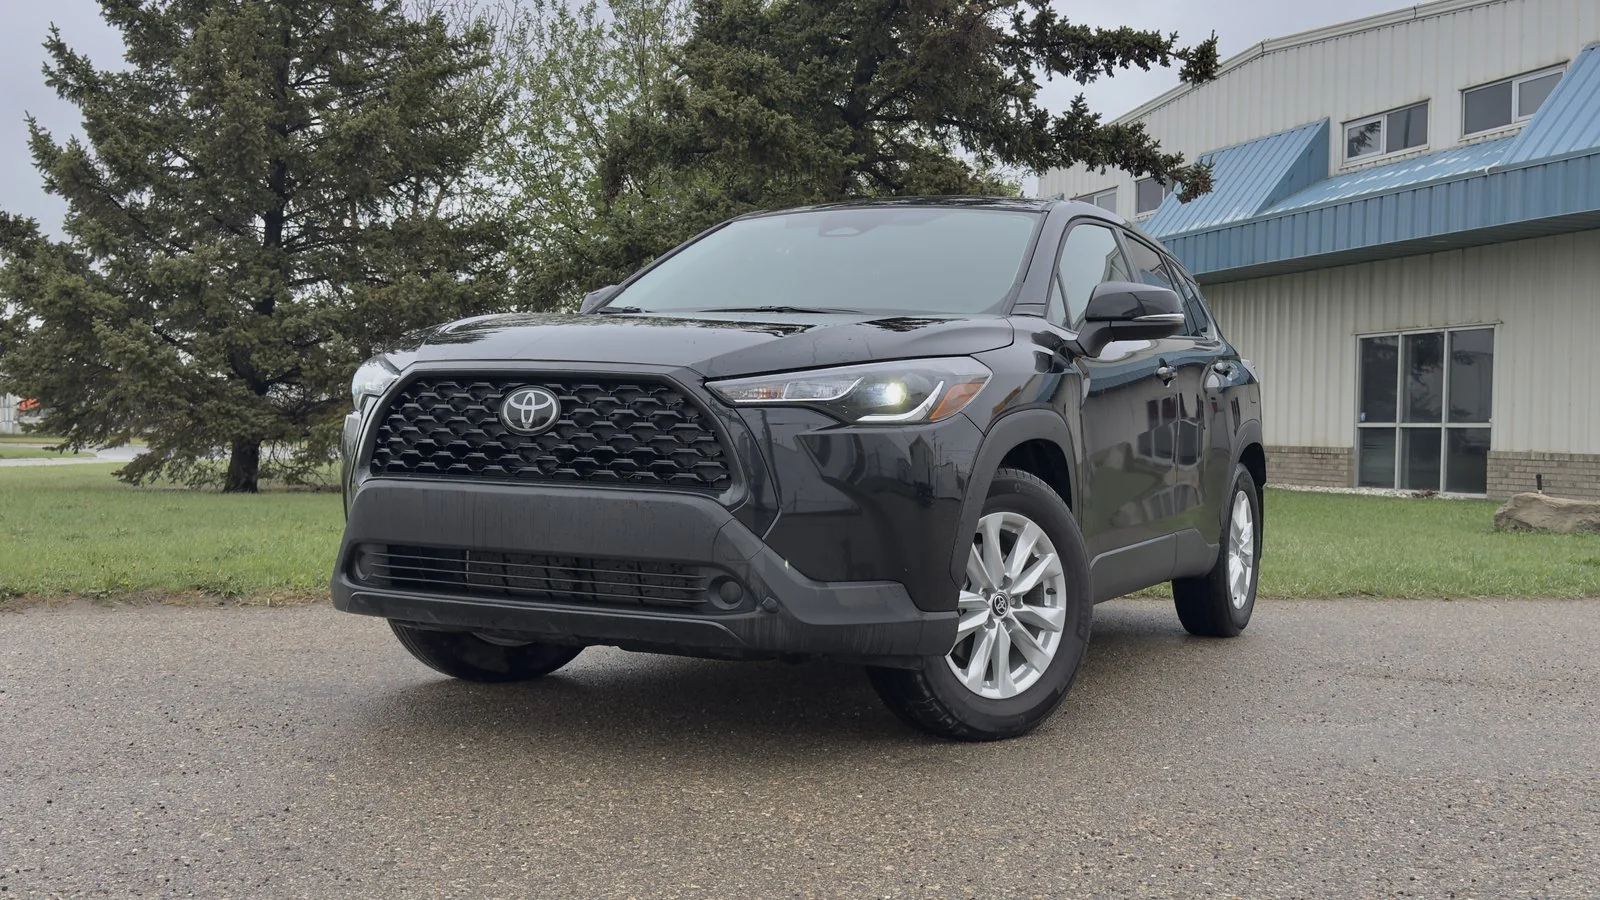
2024 Toyota Corolla Cross LE
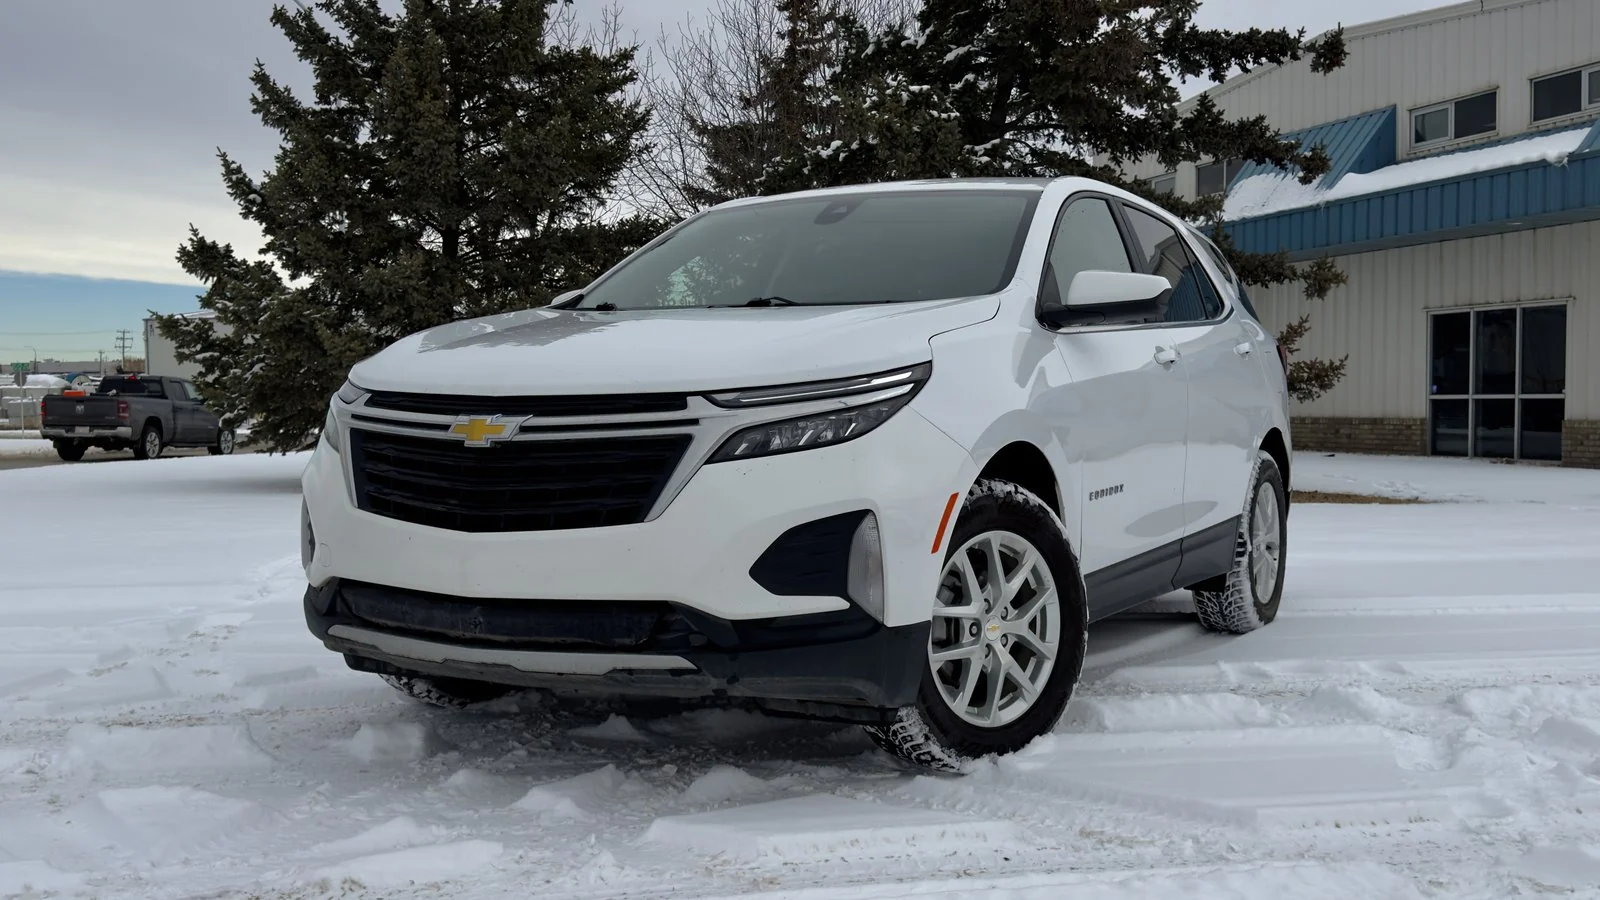
2022 Chevrolet Equinox LT
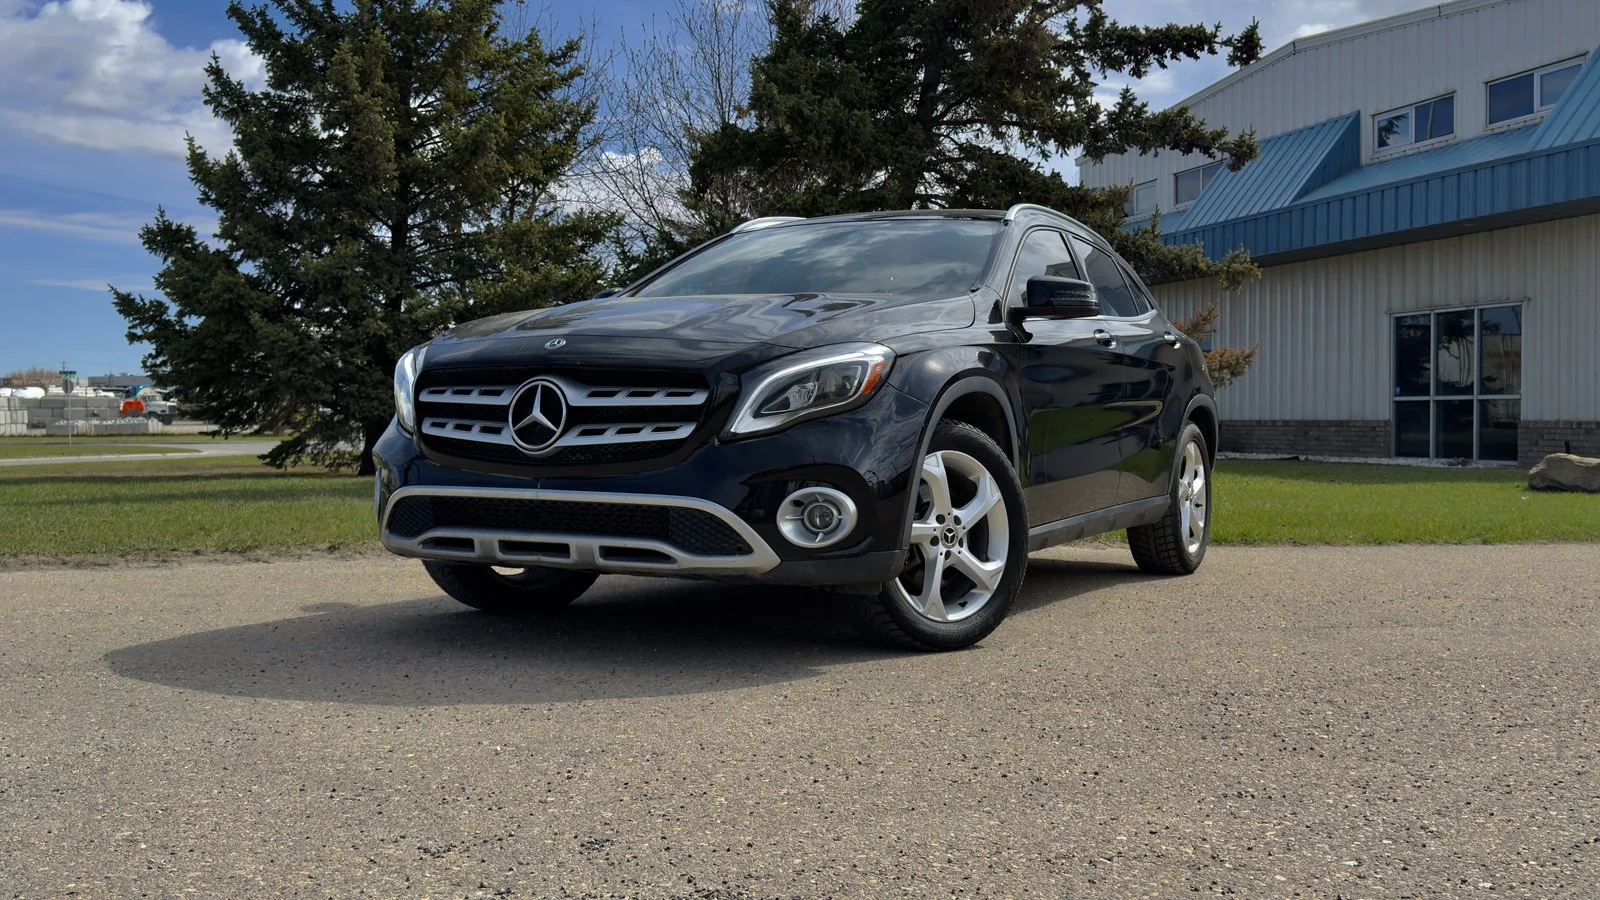
2020 Mercedes-Benz GLA250 4Matic
Not seeing it? We'll find it.
We source through our dealer partner network across Western Canada: 25,000+ vehicles to choose from. Tell us what you want and what works for your budget.
Find my car3 min · no credit impactOAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Related Articles
Ready to Find Your Vehicle?
Browse our inventory or apply for financing. All credit situations welcome.
5.0118+ Google ReviewsAMVIC LicensedFree Delivery 300km