
Deficiency Balance
What is a deficiency balance after a repossession?
A deficiency balance is what you still owe on a car loan after the lender takes the vehicle back and sells it for less than the balance. In Alberta, whether and how the lender can collect it can depend on the contract you signed.
What a deficiency balance is
A licensed insolvency trustee's page puts it this way: “Any deficiency in realizations after the sale of the vehicle is now an unsecured debt you still owe to your car loan lender.” For how lenders read a repossession and any balance still owing, see a car loan after a repossession.
What Alberta law says
Alberta's Personal Property Security Act says: “Unless otherwise agreed, or unless otherwise provided in this or any other Act, the debtor is liable for any deficiency.”
The Government of Alberta lists “property such as vehicles, furniture or a house” among common types of security. It says: “If the value of the security doesn’t cover your debt, the creditor may also sue you for any money left owing, including interest and costs.”
It treats a conditional sales contract separately. “A conditional sales contract is a special type of secured contract.” It adds: “With a conditional sales contract, if you don’t make your payments as agreed, the creditor may either seize the goods that you bought on the conditional sales contract, or sue you to get a judgement for the amount that you owe.”
Which of these applies to you depends on the contract you signed. A lawyer or a licensed insolvency trustee can read yours.
Legal information, not legal advice
Frequently Asked Questions
Can a lender sue me for a deficiency balance in Alberta?
The Government of Alberta says: “If the value of the security doesn’t cover your debt, the creditor may also sue you for any money left owing, including interest and costs.” For a conditional sales contract it says: “With a conditional sales contract, if you don’t make your payments as agreed, the creditor may either seize the goods that you bought on the conditional sales contract, or sue you to get a judgement for the amount that you owe.” Which one applies depends on your contract, so ask a lawyer or a licensed insolvency trustee.
Can a consumer proposal or bankruptcy deal with a deficiency balance?
A licensed insolvency trustee’s page says that after a repossession, “bankruptcy or a consumer proposal can eliminate your responsibility for the remaining car loan balance.” Whether that fits your file is a question for a licensed insolvency trustee.
Cars you could drive home
Browse all inventory →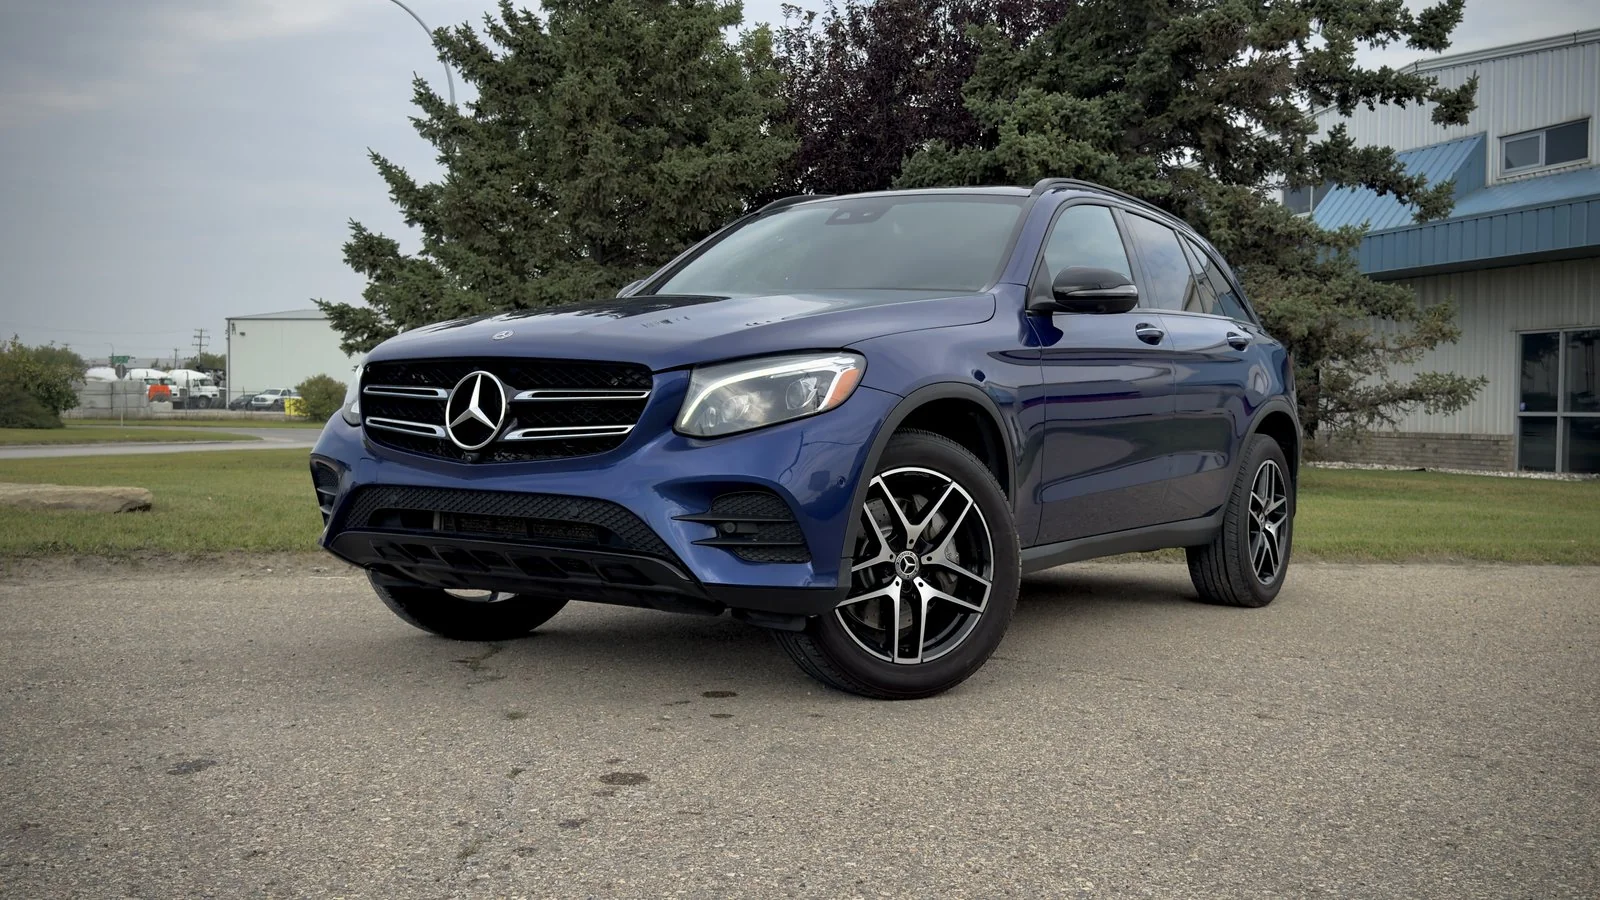
2019 Mercedes-Benz GLC-Class GLC300
$164 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $5,889
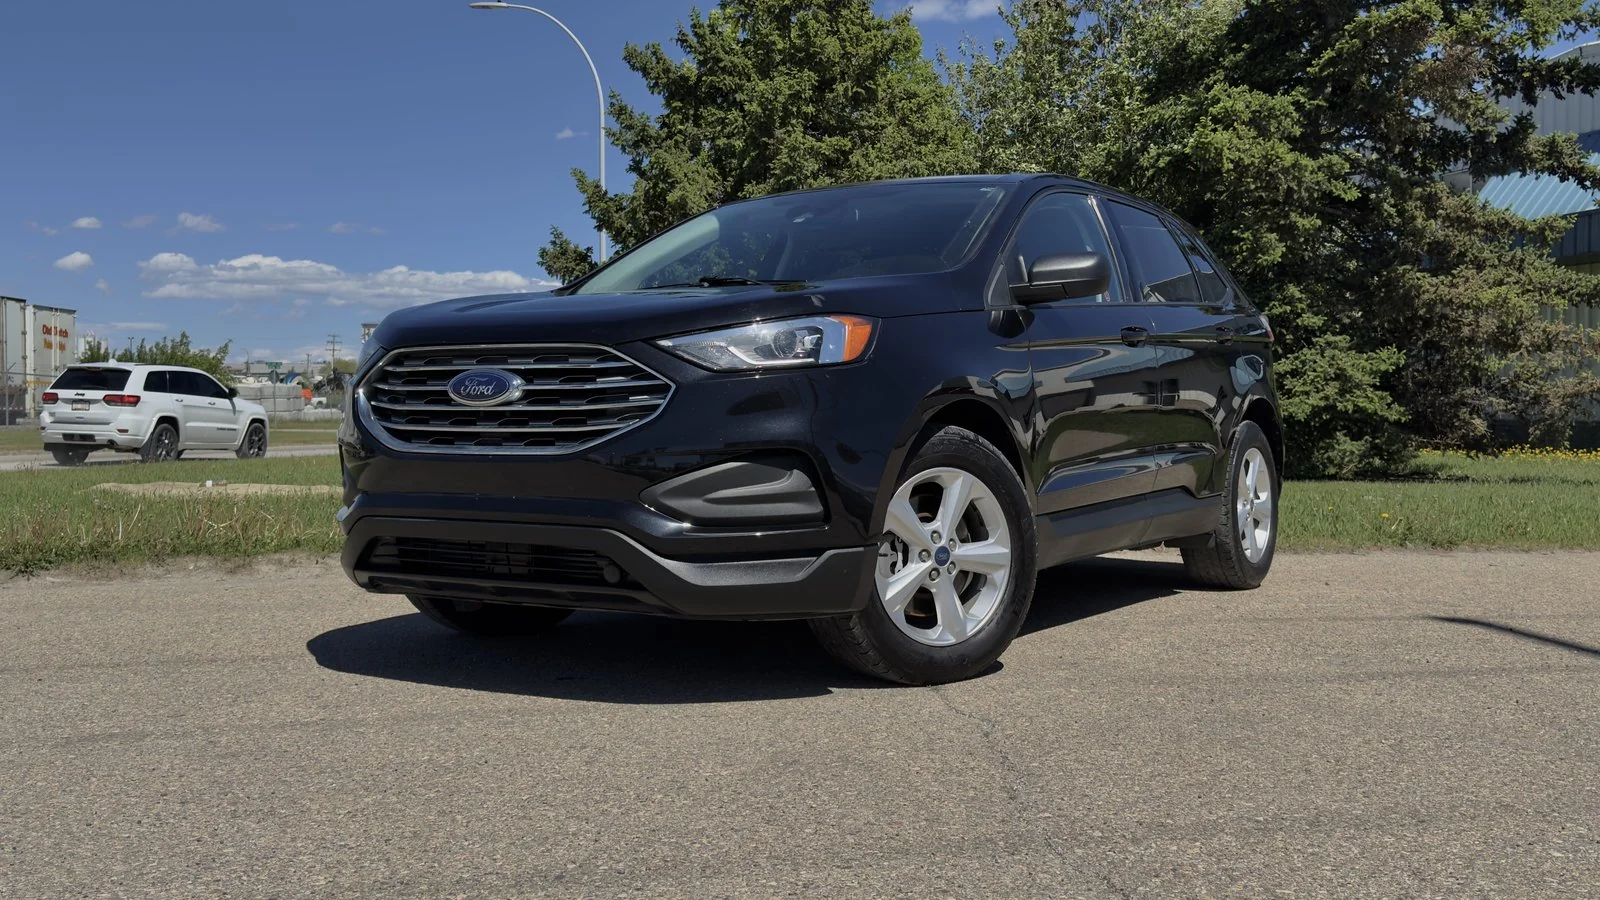
2020 Ford Edge SE
$150 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $5,398
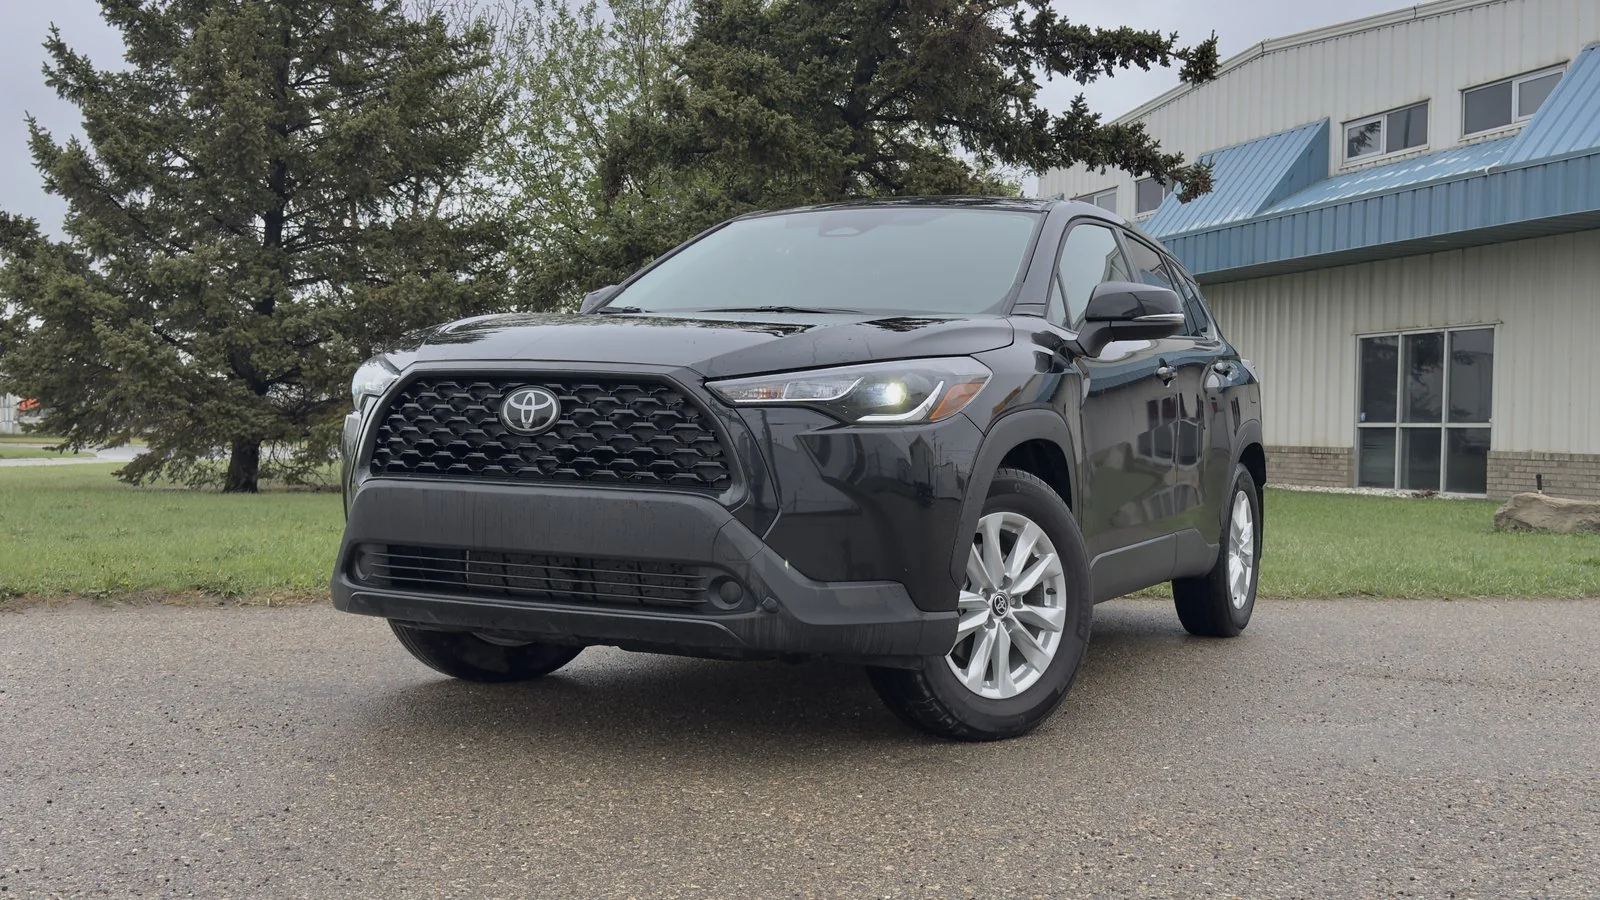
2024 Toyota Corolla Cross LE
$229 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $8,225
OAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Related Terms
Sources (pages opened October 6, 2026): Government of Alberta: Creditors, collection agencies and debt repayment; Alberta King’s Printer: Personal Property Security Act, RSA 2000, c P-7, s. 61(4) (consolidation current as of June 1, 2024); Hoyes Michalos & Associates Inc. (licensed insolvency trustee): Dealing with Car Loan Debt and Vehicle Repossession. These are public pages, quoted as written. Laws change, so check the source before you rely on a detail.
Last reviewed October 2026 by the Shift Happens finance team
Dealing with a repossession?
Tell us about it when you apply. We review every application and call you back.