Subprime Collection Practices in Alberta: Know Your Rights
In this article
- What Are Subprime Auto Lenders Allowed to Do When You Miss Payments in Alberta?
- Alberta's Legal Framework for Debt Collection
- What Collectors Cannot Do Under Alberta Law
- When Repossession Is Actually Legal in Alberta
- Your Right to Request Written-Only Communication
- What Happens to Your Credit During Collection
- Negotiating a Payment Arrangement: What Actually Works
- What to Do If You Think You've Been Treated Unlawfully
- Continue Reading
- When Shift Happens Makes Sense for You
- Frequently Asked Questions
- Can a car loan collector in Alberta call me at work?
- How many days late can I be before a subprime lender in Alberta repossesses?
- What's the difference between a deficiency balance and the original loan?
- Can I dispute a debt that's in collection in Alberta?
- Will settling a collection account for less than the full balance hurt my credit further?
- Compare and Apply
Check Your Options in 3 Minutes
No credit impact. All credit situations welcome.
5.0121+ Google ReviewsAMVIC LicensedFree Delivery 300km
Your subprime auto loan payment is 47 days late. The calls have started — sometimes at 7:45 a.m., sometimes on weekends. A collector told you they'd be "at your door" to repossess the car if you didn't pay today. Here's what Alberta law actually says about what collectors can and cannot do — and the difference between a bluff and a real legal threat.
What Are Subprime Auto Lenders Allowed to Do When You Miss Payments in Alberta?
In Alberta, debt collectors operating under the Consumer Protection Act must not contact you before 7 a.m. or after 10 p.m., threaten action they cannot legally take, or use abusive language. Repossession requires you to be in default per your loan contract — typically 30–90 days late depending on lender. The Financial Consumer Agency of Canada says: "You can ask the collection agency to contact you only in writing."
Alberta's Legal Framework for Debt Collection
Collection activity on subprime auto loans in Alberta falls under two overlapping regimes: the federal Personal Information Protection and Electronic Documents Act (PIPEDA) governs how your data is used, and Alberta's Consumer Protection Act and its Collection and Debt Repayment Practices Regulation govern collector conduct directly.
The Alberta Collection and Debt Repayment Practices Regulation sets hard limits on when, how often, and in what manner collectors can contact you. Violations can be reported to Service Alberta and can support a complaint or civil action. AMVIC-licensed dealers and their partnered lenders must also adhere to AMVIC conduct standards — understanding how your financing agreement works is the first step to knowing when someone's crossing a line.
What Collectors Cannot Do Under Alberta Law
The prohibited practices list is longer than most borrowers realize:
- Time restrictions: a collection agency or collector may not "make any personal call or telephone call for the purpose of collecting or attempting to collect a debt on any day except between 7 a.m. and 10 p.m. in Alberta"
- Frequency cap: a collection agency or collector may not "exceed 3 unsolicited contacts on behalf of the same creditor with a debtor in any period of 7 consecutive days, not including contacts with a third party to locate a debtor, mistaken contact with a third party, or contacts by traditional mail"
- Workplace contact: a collection agency or collector may not "contact the debtor's employer for any purpose other than to confirm the debtor's employment status, business title and the address of the business, in preparation for legal proceedings"
- Threats of action they can't take: A collector cannot threaten criminal charges, police involvement, or immediate seizure unless they have a legal basis to do so at that moment
- Abuse: No profanity, threats of violence, or repeated calls designed to harass
- Misrepresentation: Cannot claim to be a lawyer, a government agency, or a bailiff unless they actually are one
If a collector has violated any of these, document it: date, time, name if given, what was said. That documentation supports a complaint to Service Alberta's consumer protection division.
When Repossession Is Actually Legal in Alberta
This is where borrowers often get confused — a collector threatening "we're coming to get the car today" may be bluffing, or may not. Understanding when repossession is legally permitted removes the panic from those calls.
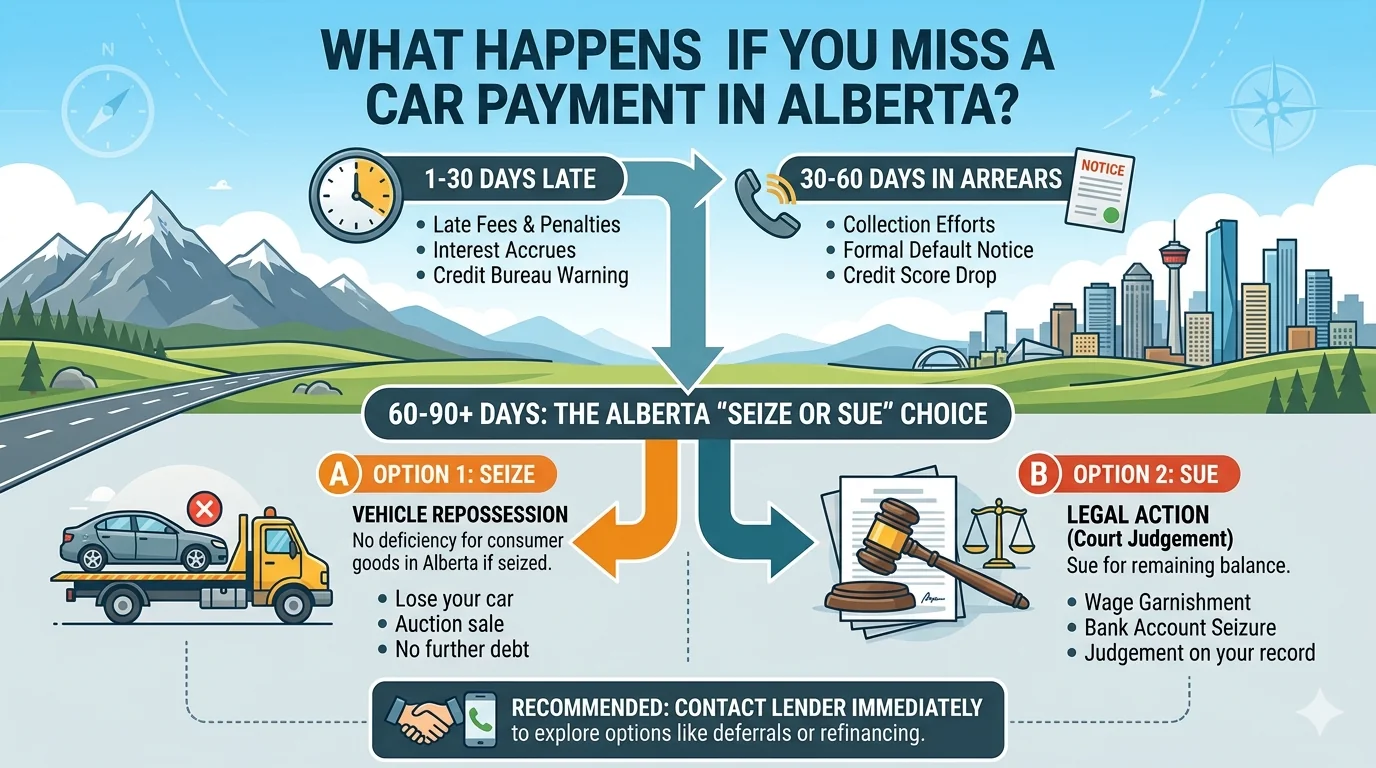
In Alberta, a lender can repossess a vehicle when you are in contractual default — defined in your loan agreement. Most subprime auto loan contracts define default as missing one or more scheduled payments (some say after 30 days past due, others after 60 or 90 days). Read your contract's default clause. After default is established, the lender typically sends a formal demand letter giving you a cure period — usually 10–30 days to bring the account current.
In Alberta, unlike Ontario, there is no mandatory pre-repossession notice period in the general law — the contract governs. However, most institutional subprime lenders (Carfinco, Rifco, Westlake, etc.) use 30-day demand letters as standard practice because it reduces the administrative and legal cost of repossession disputes. Self-help repossession — a lender physically taking the car without a court order — is permitted in Alberta as long as they don't breach the peace doing it.
Know this before missing payments: If you've missed one payment and a collector threatens immediate repossession "today," ask them to state the specific contract clause they're relying on. Most institutional lenders will not actually repossess until 60–90 days past due and after a written demand — the threat on day 35 is almost always a pressure tactic, not an imminent legal action. Get the demand letter in writing.Your Right to Request Written-Only Communication
This is one of the most powerful tools Alberta borrowers have and one of the least used. The Financial Consumer Agency of Canada says: "You can ask the collection agency to contact you only in writing. Ask your legal advisor to send a written request to your creditor by registered mail. Make sure to include an address and phone number where they can reach you."
This doesn't make the debt go away, and it doesn't stop repossession rights — but it eliminates the harassment dynamic and forces everything into a documentation trail.
If you're at this decision point and worried about your situation after a potential repossession, or trying to get ahead of default before it becomes a collection event, talk to a dealership that works with lenders specializing in restructured situations — check what you'd qualify for now before the situation worsens.
What Happens to Your Credit During Collection
The credit damage timeline on a delinquent subprime auto loan follows a standard pattern. At 30 days past due, the lender reports an R2 (late) on your Equifax/TransUnion file. At 60 days: R3. At 90 days: R4 or R5. When the lender writes the account off (typically 120–180 days past due), it's reported as R9 — the worst status short of legal action.
A repossession adds a separate notation. If there's a deficiency balance (the sale of your repossessed vehicle doesn't fully cover the loan), the lender can sue for that balance — which can result in a judgment on your credit file and potentially wage garnishment. This is why proactive communication with your lender before day 30 is always better than going quiet and hoping the calls stop.
If you want to understand exactly what's on your credit file and what the rebuild timeline looks like after a serious delinquency, the credit bureaus' own free disclosure process (not third-party apps — the bureaus themselves) shows you exactly what's been reported.
Negotiating a Payment Arrangement: What Actually Works
Most subprime auto lenders would rather collect 80% of the loan than repossess, auction the car for 60 cents on the dollar, and pursue a deficiency judgment for the gap. That math gives you negotiating leverage you may not realize you have.
When negotiating a payment arrangement, come prepared with: (1) your current income documentation, (2) a specific proposal — not "I need time," but "I can resume $X biweekly payments on [specific date] and pay the arrears $Y over [specific number of payments]," (3) something in writing immediately after any verbal agreement.
Some lenders offer formal deferral products — payment holiday and deferral options exist at several Canadian subprime lenders, though these are contractually defined and must be arranged proactively, not after default has already occurred. If your loan is with a lender who offers this and you're not yet in default, a deferral request made 10 days before a missed payment has a much higher approval rate than one made 40 days after.
What to Do If You Think You've Been Treated Unlawfully
If a collector has violated Alberta's Consumer Protection Act: document everything, then file a complaint with Service Alberta's Consumer Protection and Government Services division. You can also file with the Financial Consumer Agency of Canada (FCAC) if the lender is federally regulated (e.g., a chartered bank's captive finance arm).
For serious violations, a consumer protection lawyer in Alberta can advise on whether a civil claim is viable.
If the collection situation has you worried about your broader credit situation and future vehicle financing, understanding the timeline for credit recovery after a serious delinquency helps set realistic expectations. Subprime lenders who specialize in post-collection financing exist in Alberta — a 90-day delinquency that was subsequently cured is not the same file as an uncured repossession with a judgment.
Continue Reading
Want the next layer of detail? These guides cover the closest-adjacent situations to this one:
- How Credit Unions Beat Banks on Subprime Car Loans in Alberta
- Bad-Credit Car Insurance in Alberta: How We Help You Shop the Market
- Alberta Has No Car Cooling-Off Period: What Buyers Must Know
- High Income, Low Credit Score: Financing the Paradox
- Catalytic Converter Theft Prevention for Alberta Urban Drivers
- Boating Season: Tow Vehicle Setup and Trailer Wiring in Alberta
When Shift Happens Makes Sense for You
Reach out to us if you: (1) are looking for a used vehicle in Alberta, (2) have any credit situation from prime to deep subprime — including accounts in collections or recently resolved delinquencies, (3) want lenders who specialize in complex credit files competing for your business. Not a fit if: new vehicles only, lease-only inventory, or buying outside western Canada.
If you're in this spot, take the lighter first step: run an approval check or start a financing application. Each one is a no-hit-to-credit query until you formally proceed.
Frequently Asked Questions
Can a car loan collector in Alberta call me at work?
Alberta's Collection and Debt Repayment Practices Regulation says a collection agency or collector may not "contact the debtor's employer for any purpose other than to confirm the debtor's employment status, business title and the address of the business, in preparation for legal proceedings".
How many days late can I be before a subprime lender in Alberta repossesses?
Your loan contract governs this, not a universal law. Most institutional subprime lenders (Carfinco, Rifco, etc.) issue a formal demand letter after 30–60 days and repossess after the demand period expires — typically 10–30 more days. Self-help repossession without notice is legally permitted in Alberta but rarely happens at institutional lenders before the 60–90 day mark.
What's the difference between a deficiency balance and the original loan?
After repossession, the lender auctions your vehicle — often for 50–70% of market value at a wholesale auction. The deficiency balance is what you still owe after auction proceeds are applied: original loan balance minus auction recovery. In Alberta, lenders can sue for this balance and obtain a judgment valid for 10 years.
Can I dispute a debt that's in collection in Alberta?
Alberta's Collection and Debt Repayment Practices Regulation says a collection agency or collector may not "refuse to provide sufficient information on request to the debtor to ensure that the debtor is aware of the identity of the original and current creditor of the debt and the details of the debt". The Financial Consumer Agency of Canada says that if you think the debt is someone else's, or that they made a mistake, you should "tell the debt collector" and "contact the creditor to find out what steps you should take to correct the error".
Will settling a collection account for less than the full balance hurt my credit further?
Settling for less than the full balance (a "partial settlement") is reported as R9-settled on your credit file. This is marginally better than an unpaid R9, and significantly better than a deficiency judgment. Equifax says that "the entire collection account would be removed 6 years from the date of first delinquency on the account (typically when it went to collection)" and that "If you pay the collection account before the 6-year period is up, it remains on your Equifax credit report".
Compare and Apply
- Bad Credit Car Loans — Complete Guide — auto loans for all credit situations
- Subprime Auto Financing Explained — subprime auto financing explained
Financing Resources
Cars you could drive home
See all inventory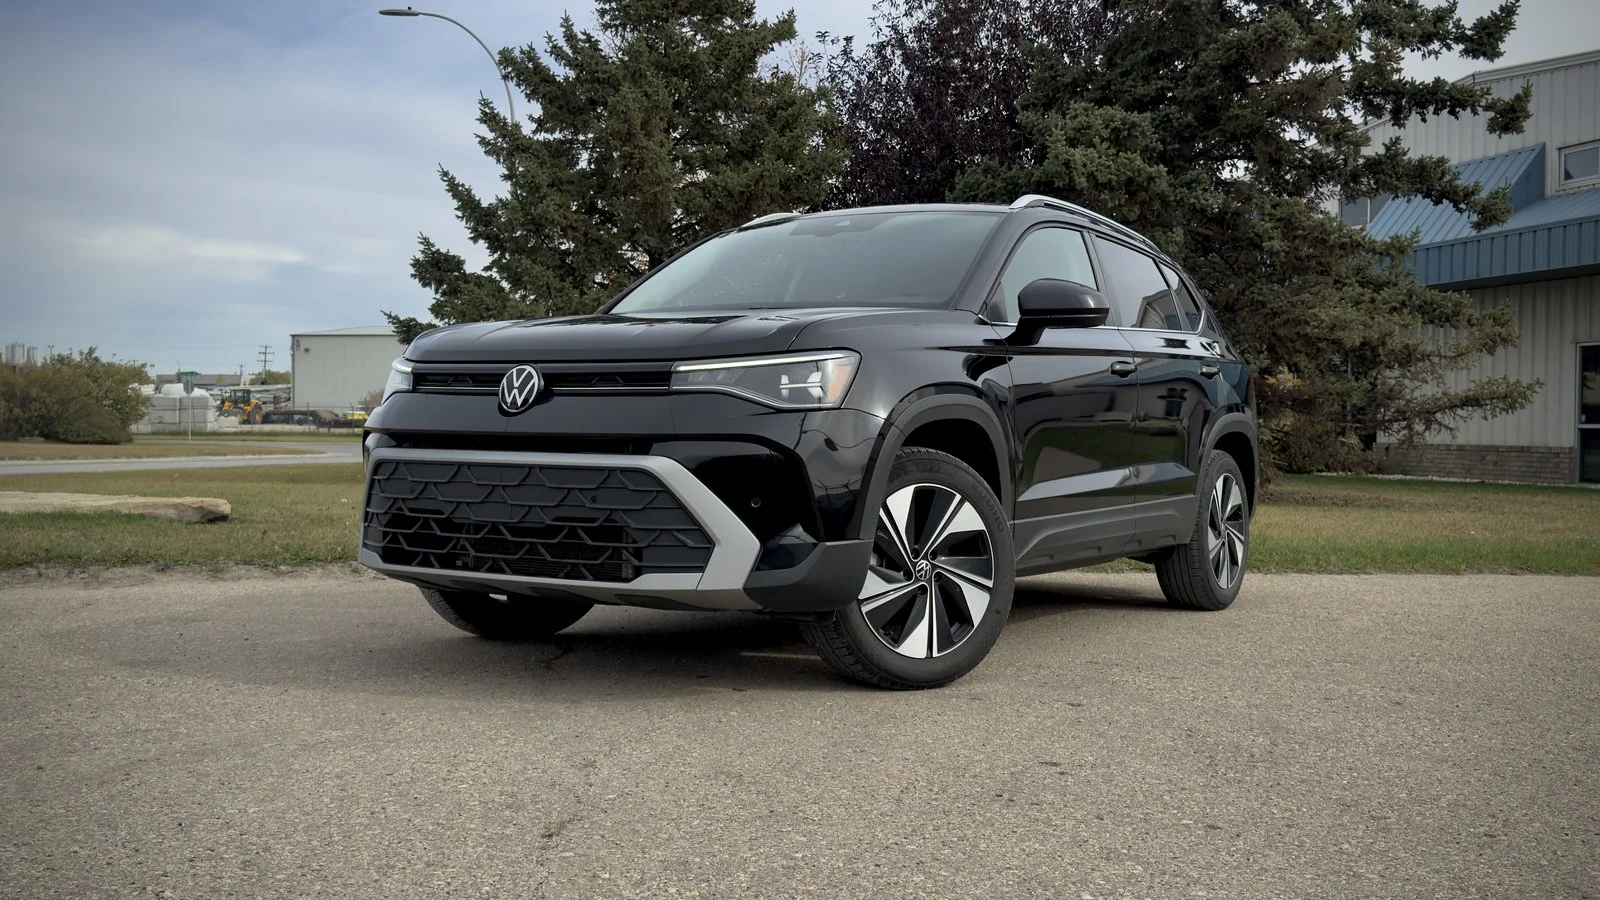
2025 Volkswagen Taos Comfortline
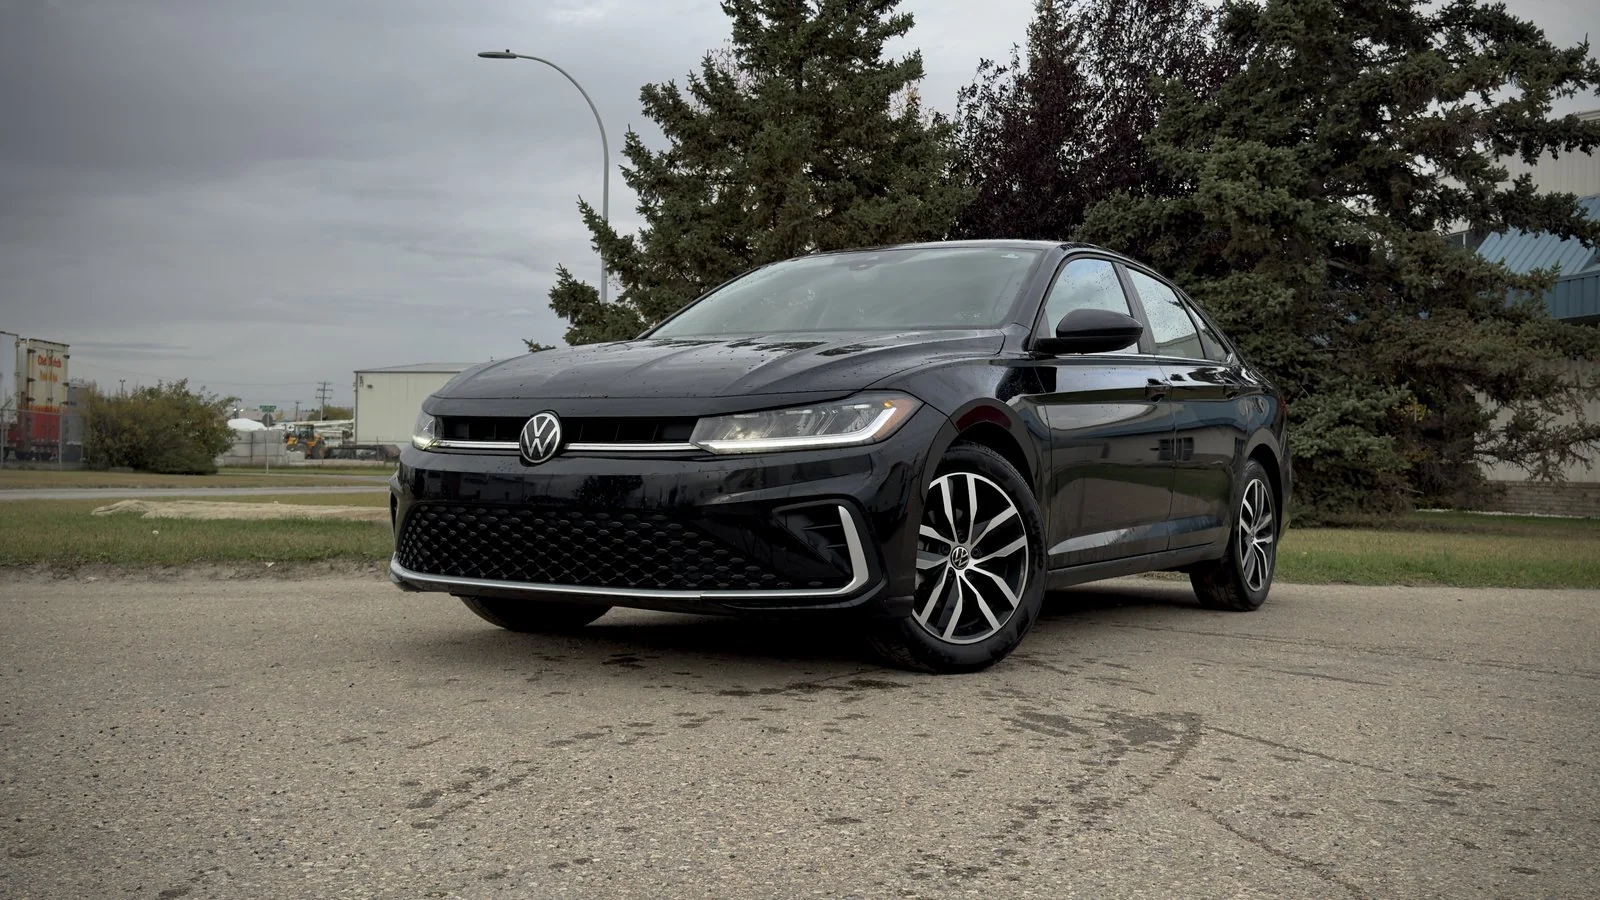
2026 Volkswagen Jetta Comfortline
2025 Kia K4 EX
Not seeing it? We'll find it.
We source through our dealer partner network across Western Canada: 25,000+ vehicles to choose from. Tell us what you want and what works for your budget.
Find my car3 min · no credit impactOAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Related Articles
Ready to Find Your Vehicle?
Browse our inventory or apply for financing. All credit situations welcome.
5.0121+ Google ReviewsAMVIC LicensedFree Delivery 300km