
Car Loan When Your Spouse Is in a Consumer Proposal
Can I get a car loan if my spouse is in a consumer proposal?
A proposal sits on the credit report of the person who filed it, not on yours. Apply alone and a lender reads your file. Apply together and lenders usually check both. Every lender decides each file, so we cannot promise a result. We review every application and call you back.
Who this page is for
- You work, and your pay is steady and easy to show.
- Your spouse or partner is in a consumer proposal, or finished one not long ago.
- You want to know whose name, income and credit a lender reads.
This page is part of our guide to consumer proposal car loans in Alberta. It covers the household side: you are the one buying, and your spouse or partner is the one with the proposal.
General information, not legal or insolvency advice
Key Facts
- Who this is for
- Working, with a spouse or partner in a proposal
- Whose credit report
- Each person has their own
- Apply alone
- A lender reads your file, not your spouse's
- Apply together
- Lenders usually check both files, and both of you are responsible for the loan
- Questions about the proposal
- Ask the licensed insolvency trustee who runs it
- Lender network
- 21+ lenders
See what you pre-qualify for
A few quick answers. No commitment.
Does my spouse’s consumer proposal show up on my credit report?
Not on its own. A credit report belongs to one person. Equifax Canada says your credit report stays separate from your spouse’s, and that one spouse’s poor credit history does not affect the other’s unless you jointly apply for a loan or open a joint account.
The Financial Consumer Agency of Canada describes a consumer proposal as a legal agreement between the person who files and their creditors, set up by a licensed insolvency trustee. So the proposal sits on the filer’s report. The agency says Equifax and TransUnion remove it 3 years after the filer has paid off the debts in the proposal, or 6 years after they sign it, whichever comes first.
One exception is a debt you both signed. A joint account can appear on both credit reports. If you and your spouse share a card or a loan that went into the proposal, read your own report to see how it shows. The federal bankruptcy office says, about bankruptcy, that your debts are your own, but a creditor can pursue your spouse for a joint (co-signed) debt. Your spouse can ask their trustee which debts in the proposal are joint.
Can I apply for a car loan on my own?
Yes. Equifax says being married does not mean you have to apply for credit together. You can apply for a car loan entirely by yourself, and it says that might be the best option when you have the stronger credit file.
Applying alone puts your credit file and your income in front of the lender. Your spouse’s file is not part of it. The catch is that the payment has to fit your income alone. The example below shows what that can look like.
We start with your own application. If adding your spouse would help, we will say so. For the side of a co-signer or co-applicant who is not in a proposal, read do cosigners help with a bad credit car loan.
Should we apply together?
Applying together changes three things.
- Lenders read both files. Equifax says lenders will likely consider both credit profiles, so if one spouse has poor credit or high debt, it can affect the odds of approval and may lead to a higher interest rate.
- Both incomes can count. Two incomes can make the same payment look smaller next to your pay. The example below shows how much.
- Both of you are responsible. The Financial Consumer Agency of Canada says a joint borrower is equally responsible for repaying the unpaid balance. Equifax adds that a joint account can appear on both credit reports, so late or missed payments can hurt both scores.
Which way it nets out depends on the lender and the files. One Alberta lender’s guide says adding a co-signer with good credit can improve your chances of approval and potentially lower your interest rate. Equifax says a spouse with poor credit can work the other way. Both can be true in different files.
We cannot promise what any lender will decide. We review every application and call you back, and every lender decides each file.
Whose income can a lender count?
Many lenders count the income of the people on the application. If your spouse is not on the loan, their pay is usually not part of the file. If you want it counted, your spouse applies with you, and that brings their credit file in too.
Here is one example. You earn $3,800 a month and want a used SUV at $28,000.
Worked example
- Gross pay
- $3,800 a month
- Credit score
- 550–599
- Vehicle
- used SUV, $28,000
- Down payment
- $0
- Amount financed
- $28,000 over 72 months
- Example rate
- 16.9% APR (Subprime example)
Payment: ~$286/bi-weekly (or ~$621/mo)
That is about 16% of gross monthly pay. A common rule of thumb is to keep a car payment under 15% of gross pay.
Example, not an offer. Your rate depends on your file; rates run from 4.99% APR (prime) to 29.9% APR (deep subprime).
Alone, that payment is about 16% of your gross monthly pay. A common rule of thumb is a payment near 15% of gross pay, and this one is a little over it. If your spouse applied with you and $3,000 a month of their pay counted, the same payment would be about 9% of $6,800. That is the case for applying together. The cost is that both credit files, and both signatures, are on the loan. To try your own numbers, use the payment calculator.
What if the person in the proposal is the one applying?
Then the proposal is on the credit file the lender reads. Our guide to car loans during a consumer proposal covers that side.
Before they sign anything, they should talk to their trustee. The federal bankruptcy office gives two reasons.
- A person who files a proposal must give the trustee a complete list of their assets and debts. A new car and a new loan are part of that picture.
- If a person making monthly proposal payments misses three, the proposal is deemed annulled, and creditors can take action to collect what is owed, unless a court orders otherwise or an amendment has been filed. The Bankruptcy and Insolvency Act, section 66.31, sets this rule.
A new car payment should leave room for the proposal payments. They can ask the trustee whether the proposal needs a sign-off for a new loan. We cannot answer that for them.
What should we bring?
Bring what shows who you are and what you earn, for each person on the application.
- Government photo ID.
- Your two most recent pay stubs. If you are self-employed, your latest Notice of Assessment and a few months of bank statements.
- Proof of your address, like a utility bill or a bank statement, and a void cheque.
- If the person in the proposal is on the application, have the proposal paperwork and the trustee’s contact details handy. A lender may ask for them.
For what lenders check about pay, see what car lenders verify when you work. The quickest start is the online application. We review every application and call you back. Or call us at (825) 736-4438.
Example payments are estimates. Not an offer.
Vehicles in stock right now
Browse all inventory →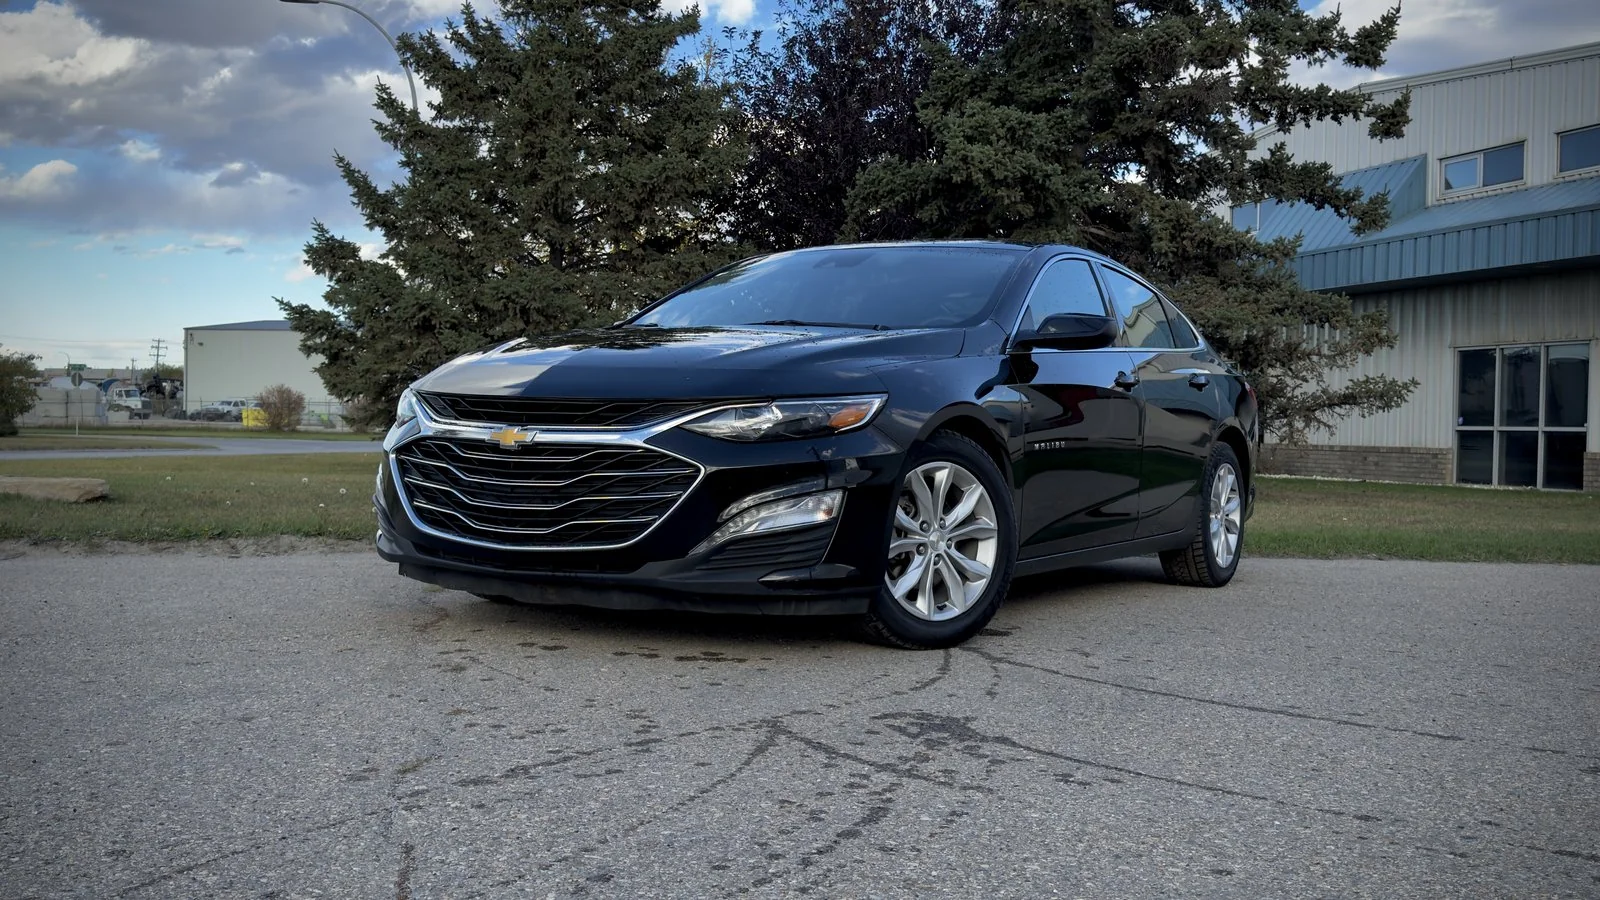
2025 Chevrolet Malibu 1LT
$164 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $5,889
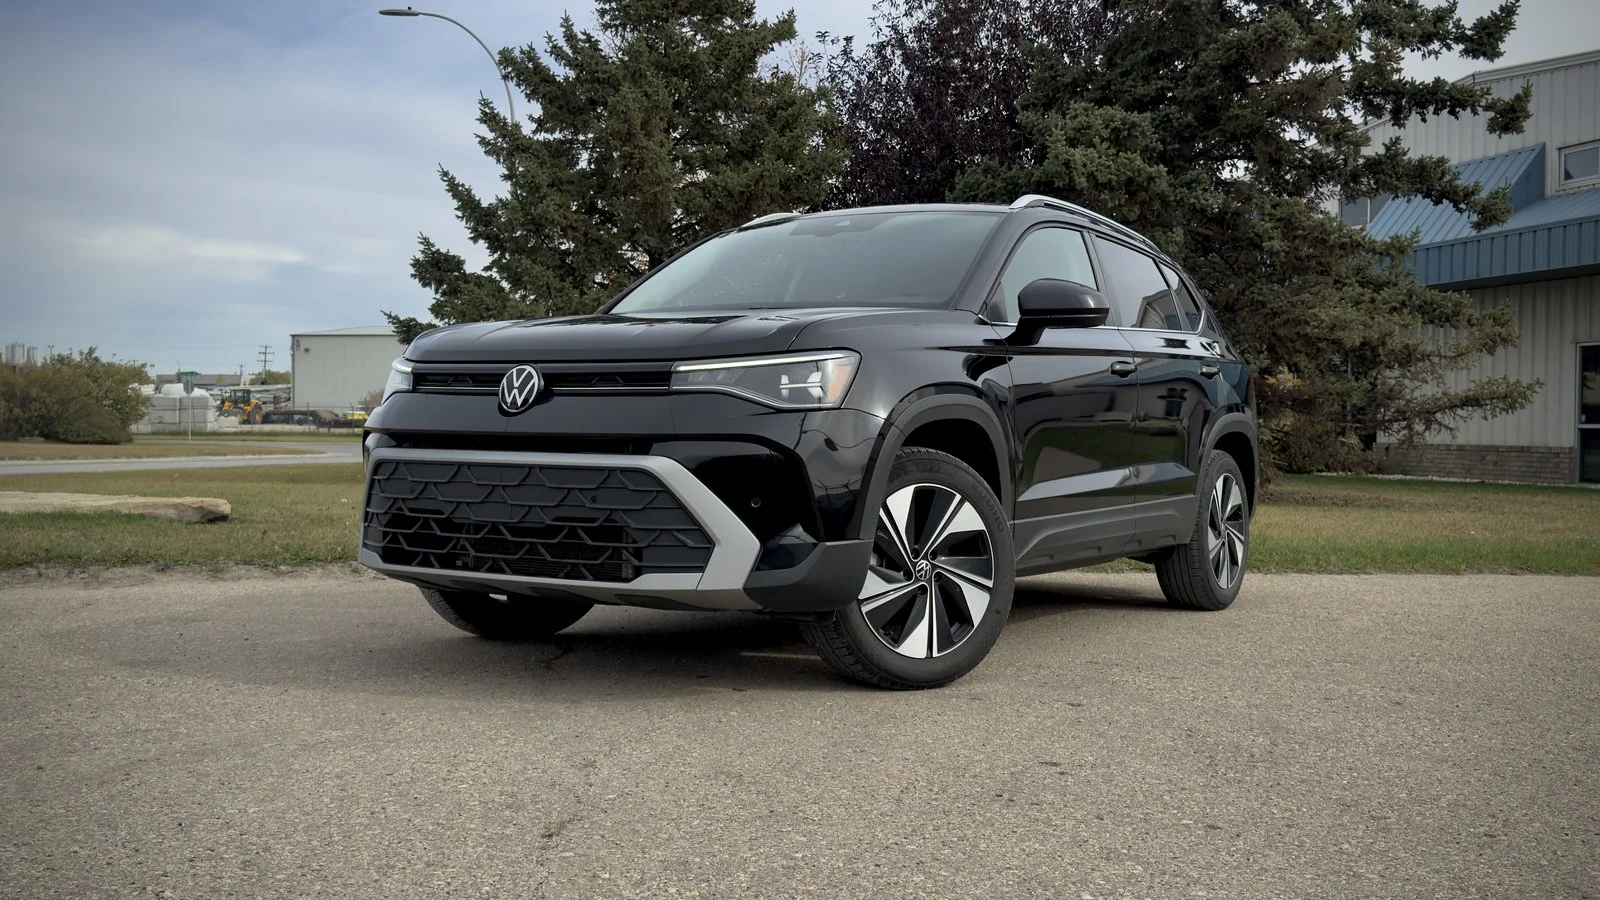
2025 Volkswagen Taos Comfortline
$185 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $6,626
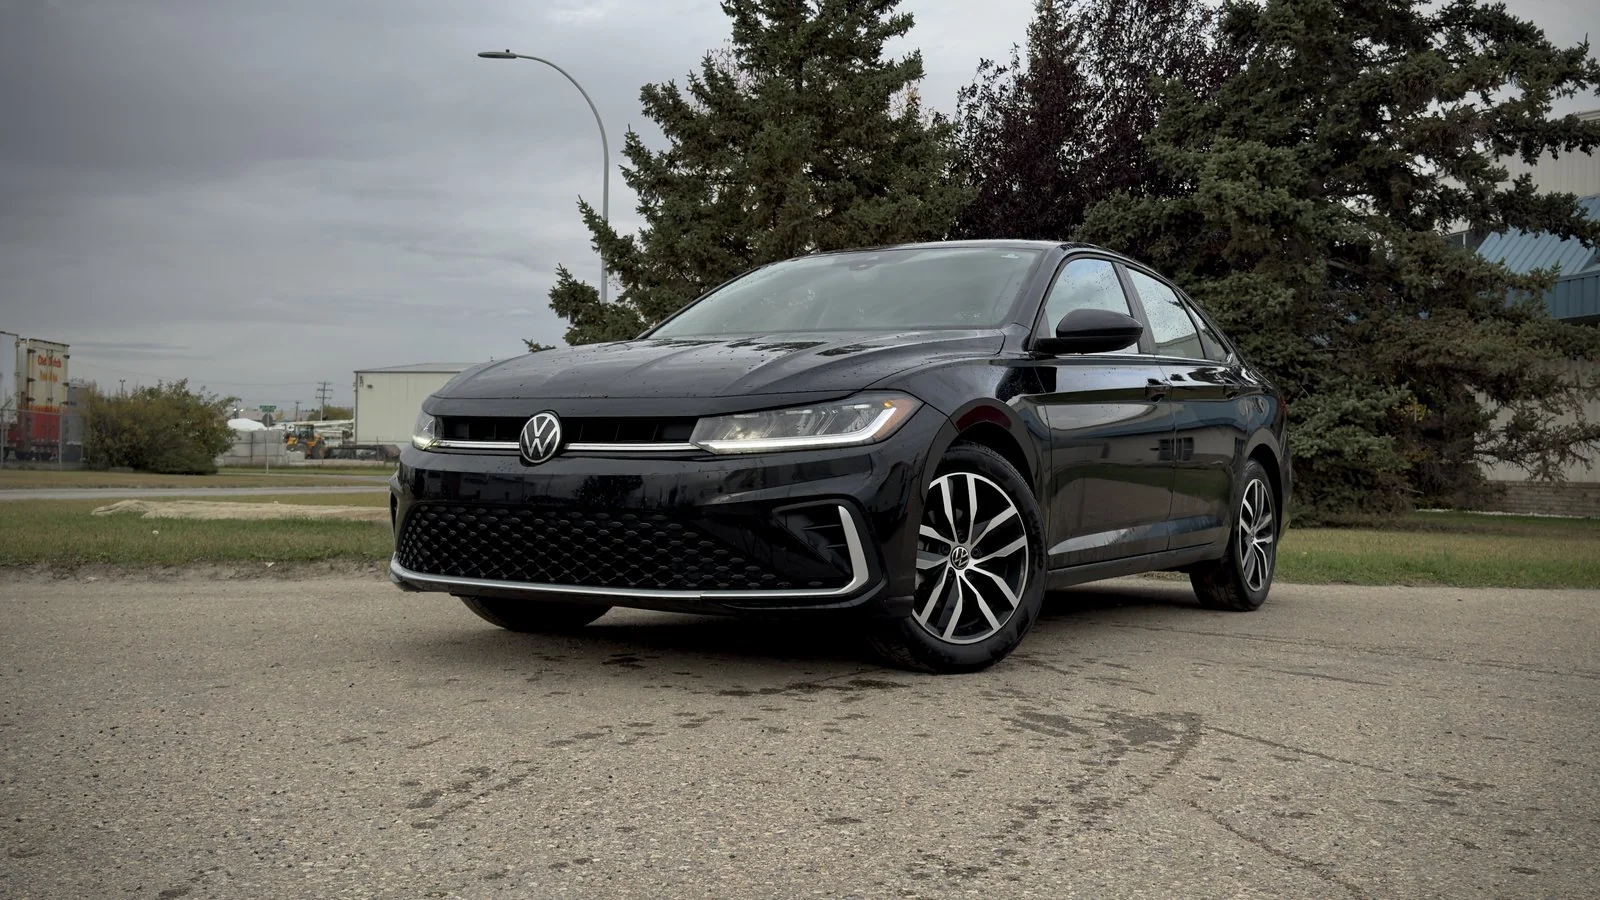
2026 Volkswagen Jetta Comfortline
$195 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $6,996
OAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Spouse in a consumer proposal: common questions
Can I get a car loan if my spouse is in a consumer proposal?
It depends on your own file and income. Your spouse's proposal is on your spouse's credit report, not yours. If you apply alone, a lender reads your file. If you apply together, lenders usually check both. We cannot promise what a lender will decide. We review every application and call you back, and each lender decides each file.
Will my spouse's consumer proposal show on my credit report?
Not on its own. Equifax says each spouse has their own credit report, and one spouse's credit problems do not affect the other's unless you jointly apply for a loan or open a joint account. A debt you both signed can appear on both reports. Read your own report to see what is on it.
Can I use my spouse's income if they are not on the loan?
Many lenders count the income of the people on the application. If your spouse is not on the loan, their pay is usually not part of the file. If you want it counted, your spouse would apply with you, which also brings their credit file in. Ask us before you decide.
If we apply together, does the proposal count against both of us?
The proposal stays on the credit report of the person who filed it. If you apply together, lenders will likely consider both credit profiles, so it can affect the file and may lead to a higher rate. The new loan would be a joint account, which can appear on both reports, so late payments would hurt both of you.
Am I responsible for the debts in my spouse's proposal?
The federal bankruptcy office says, on its bankruptcy page, that your debts are your own, but if you and your spouse have a joint (co-signed) debt, a creditor can pursue your spouse for repayment. So the question is whether you signed any of the debts in the proposal. Your spouse can ask their trustee which ones are joint.
Should my spouse talk to their trustee before we sign a car loan?
If your spouse will sign or co-sign the loan, they should ask their trustee first. Even if only you sign, the household budget still has to cover the proposal payments. The federal bankruptcy office says a person who files a proposal must give the trustee a complete list of their assets and debts. It also says that if monthly payments are missed three times, the proposal is deemed annulled, and creditors can then act to collect unless a court orders otherwise or an amendment has been filed.
Does this apply to a common-law partner?
A credit report is tied to the person, through personal information such as the Social Insurance number, so it stays separate for any two people. Equifax says this about spouses, and the same logic holds for a partner. How the law treats your partner on other questions, such as a joint debt, is a question for your trustee.
Sources (pages opened October 5, 2026): Equifax Canada: What to know about credit and marriage; Equifax Canada: Marriage and credit, myths and facts; Financial Consumer Agency of Canada: How long information stays on your credit report; Financial Consumer Agency of Canada: Disclosure of information to joint borrowers; Office of the Superintendent of Bankruptcy: You owe money, consumer proposals; Office of the Superintendent of Bankruptcy: You owe money, considering bankruptcy; Justice Laws Website: Bankruptcy and Insolvency Act, section 66.31 (current to September 21, 2026); ATB Financial: Navigating car loans in Alberta. These are public pages, quoted to show what they say. Rules and lender practices change, so check the source page and ask the licensed insolvency trustee who runs the proposal about anything that touches it.
Last reviewed October 2026 by the Shift Happens finance team
What Our Customers Say
“Luke was awesome to deal with and made the car buying experience enjoyable again for me and my wife after a few very unpleasant interactions in the past. I would highly recommend.”
“Luke was fantastic with helping us get into a mini van, we are MORE than happy. I highly recommend anyone looking for a vehicle to go check out Shift Happens!”
“I honestly can't thank Luke enough. From start to finish he was patient, respectful, transparent, and genuinely cared about helping me find the right vehicle instead of just making a sale.”
Other Financing Options
See what you pre-qualify for
Apply online. We review every application and call you back.
★★★★★ 118+ Google Reviews · AMVIC Licensed · Free Delivery 300km