
What Car Lenders Verify When You Work
What do car lenders verify when you have a job?
They check that your pay is real and steady. Lenders commonly ask for a recent pay stub or a letter from your employer, and some also want a T4 or bank statements. There is no one number of pay stubs. Every lender sets its own list, and every lender decides each file.
Who this page is for
- You work for an employer and get pay stubs or a T4.
- Your pay moves around: overtime, shift premiums, commission or a bonus.
- Your credit took a hit and you want to know what to bring.
This page is part of our guide to bad credit car loans in Alberta. It covers the pay and job side of an application.
Key Facts
- Who this is for
- Working, with pay you can show
- Lenders commonly ask for
- A recent pay stub or an employer letter; sometimes a T4 or bank statements
- How many pay stubs
- Each lender sets its own list
- Overtime and bonuses
- The lender decides how much counts
- Lender network
- 21+ lenders
See what you pre-qualify for
A few quick answers. No commitment.
How many pay stubs do I need for a car loan?
There is no one number. Every lender sets its own list. Most lender checklists name the kind of proof, not a count. Here is what lenders commonly ask for.
- A recent pay stub. Some lenders ask for your last two.
- A letter from your employer that confirms your position, start date and pay.
- A recent T4, T4A or T1 tax document with your Notice of Assessment.
- Bank statements that show your pay going in.
A practical answer: have your last two pay stubs and your latest T4 on hand. That covers most lenders’ lists, and a lender that wants more or less will say so.
How recent? Lenders ask for a recent one. Use your latest, and if your payroll portal lets you download the newest stub, grab that.
What else counts as proof of income besides a pay stub?
Pay stubs are one way to show your pay. Lenders commonly accept three others.
A letter from your employer. A good letter shows your income, your title or position and your work arrangement: whether you are full-time, part-time or on contract, and when you started.
A T4 or other tax document. A recent T4, T4A or T1 tax document with your Notice of Assessment is accepted as proof of employment by many lenders, sometimes as a second proof next to a pay stub.
Bank statements. They show your pay landing in your account. Have them ready if your lender asks; how many months a lender wants varies by lender.
Income you can prove carries weight with lenders. See how income looked across the car loans we funded.
Do overtime, shift premiums, commission and bonuses count?
It depends on the lender. Each lender decides how much of your extra pay it counts. None of the lender pages we read gives a formula for overtime, shift premiums, commission or bonuses. They list the documents.
A pay stub shows one pay period. If your hours or extras change from one period to the next, a single stub can look high or low. A T4 slip adds up the whole year. The Canada Revenue Agency counts salary, wages, commissions and bonuses as employment income, and it usually shows in box 14 of your T4.
Some lenders ask your employer about overtime and seasonal changes in your pay. If your extras are regular, a letter from your employer that sets out your usual hours and how your pay is made up can show the pattern.
Here is why it matters. One example buyer, one car, one payment.
Worked example
- Gross pay
- $3,800 a month
- Credit score
- 550–599
- Vehicle
- used SUV, $28,000
- Down payment
- $0
- Amount financed
- $28,000 over 72 months
- Example rate
- 16.9% APR (Subprime example)
Payment: ~$286/bi-weekly (or ~$621/mo)
That is about 16% of gross monthly pay. A common rule of thumb is to keep a car payment under 15% of gross pay.
Example, not an offer. Your rate depends on your file; rates run from 4.99% APR (prime) to 29.9% APR (deep subprime).
Now add $700 a month of regular overtime that the lender also counts. The same payment is about 14% of $4,500, not 16% of $3,800. Lenders compare the payment with your income, so the pay a lender counts changes the picture. Lenders also look at more than one ratio, and every lender decides each file.
To try your own numbers, use the payment calculator. For how your score sets the rate, see car loan rates in Alberta, and for how pay and score work together, read good income, bad credit car loans.
Does the lender check with my employer?
Some do. A lender may run an employment and income check, and some contact your employer directly by phone or email instead of asking for a letter. What that looks like on a brand-new job is on our page about how lenders handle a new job or probation.
What if I am on probation or just started a job?
Lenders set their own rules on time on the job. One Canadian auto lender publishes a minimum of three months on the job, with exceptions when you take a new job in the same or a similar field after at least a year at your last one. Some lenders also ask your employer about probation.
Check your offer letter or contract for the length of any probation. Alberta’s Employment Standards use a different line: notice to end a job is not required if employment is 90 days or less.
If you are in your first months, read about starting a new job in Alberta to see how an offer letter, a first pay stub and probation fit into an application. Public sector jobs have their own probation rules: see public sector employee car loans.
What if my pay is not a regular paycheque?
If you invoice clients, drive for an app or run a business, lenders usually look at tax documents more than pay stubs. The usual ask is your T1 General and Notice of Assessment. Our pages on self-employed car financing and gig worker car financing cover what to bring. If write-offs keep your taxable income low, see what else can show your income.
If your work follows the seasons or a rotation, one pay stub may not show your usual pay. See seasonal worker car financing and oilfield worker car loans in Alberta for how to show the full picture. If you work in a school, car loans for teachers and educational assistants explains ten- and twelve-month pay and the summer. If you are paid flat rate or on commission, such as an auto technician or service advisor, see what lenders read when your pay moves with the work.
If part of your pay is garnished, your pay stub shows the smaller amount; see what to bring when part of your pay is garnished.
What should I have ready before I apply?
- Government photo ID, such as a valid Canadian driver’s licence.
- Your last two pay stubs, or a letter from your employer if you have no stubs yet.
- Your latest T4 or Notice of Assessment, if you have one.
- Bank statements, if a lender asks for them.
- A void cheque or a pre-authorized payment form.
Applying with a spouse? Each person brings the same papers. If your spouse is in a consumer proposal, see how that changes what a lender reads.
The quickest start is the online application. We review every application and call you back. Or call us at (825) 736-4438.
Example payments are estimates. Not an offer.
Vehicles in stock right now
Browse all inventory →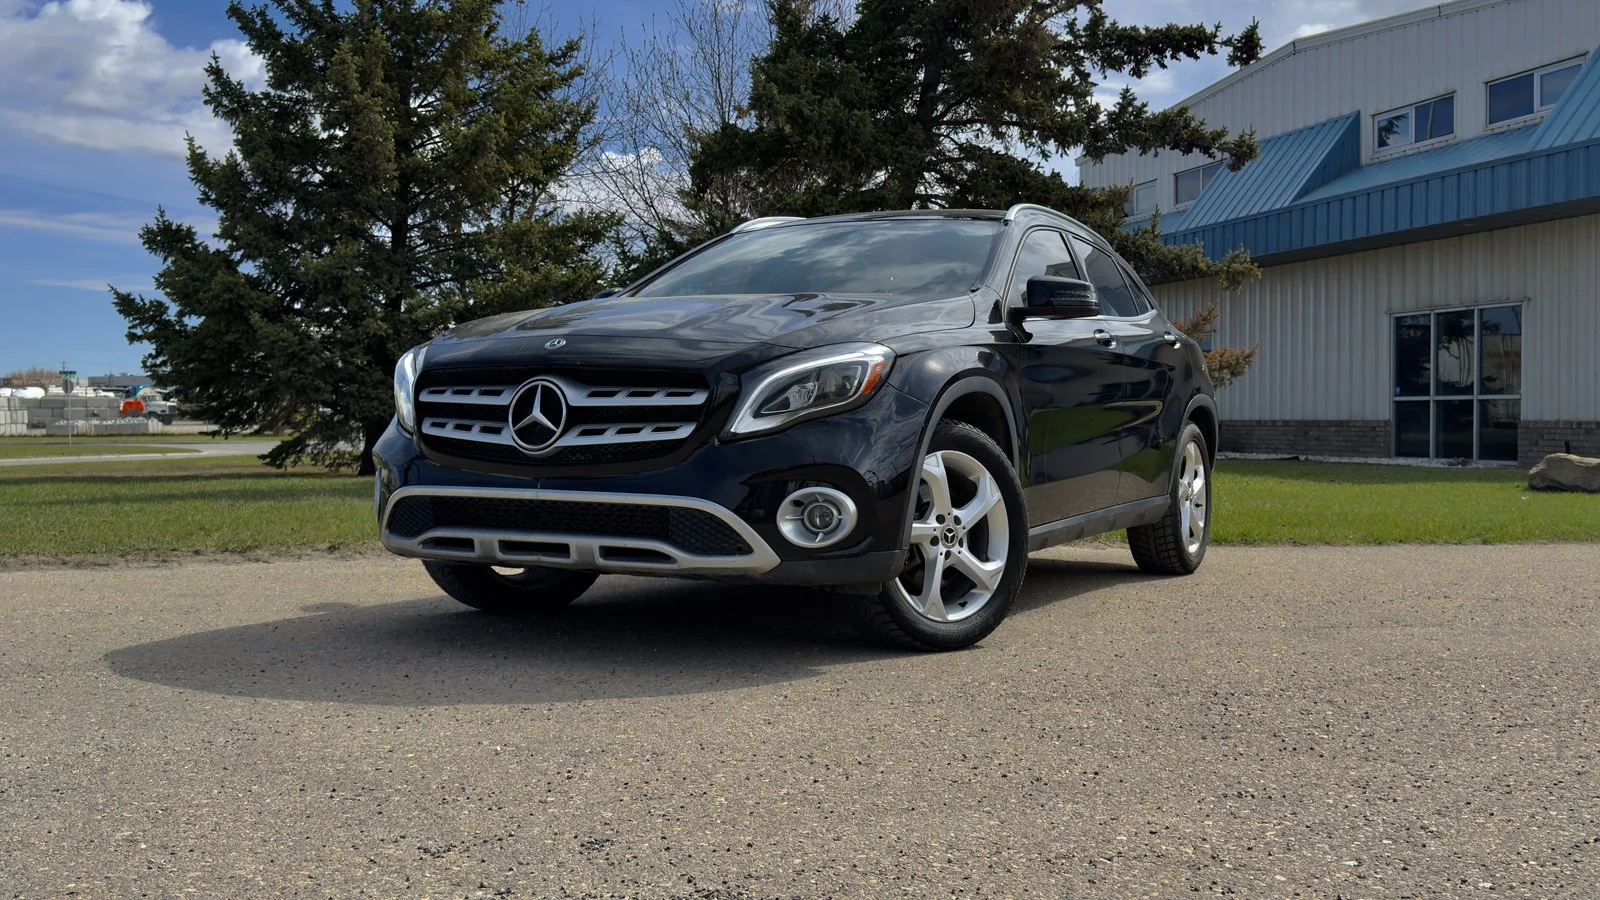
2020 Mercedes-Benz GLA250 4Matic
$150 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $5,398
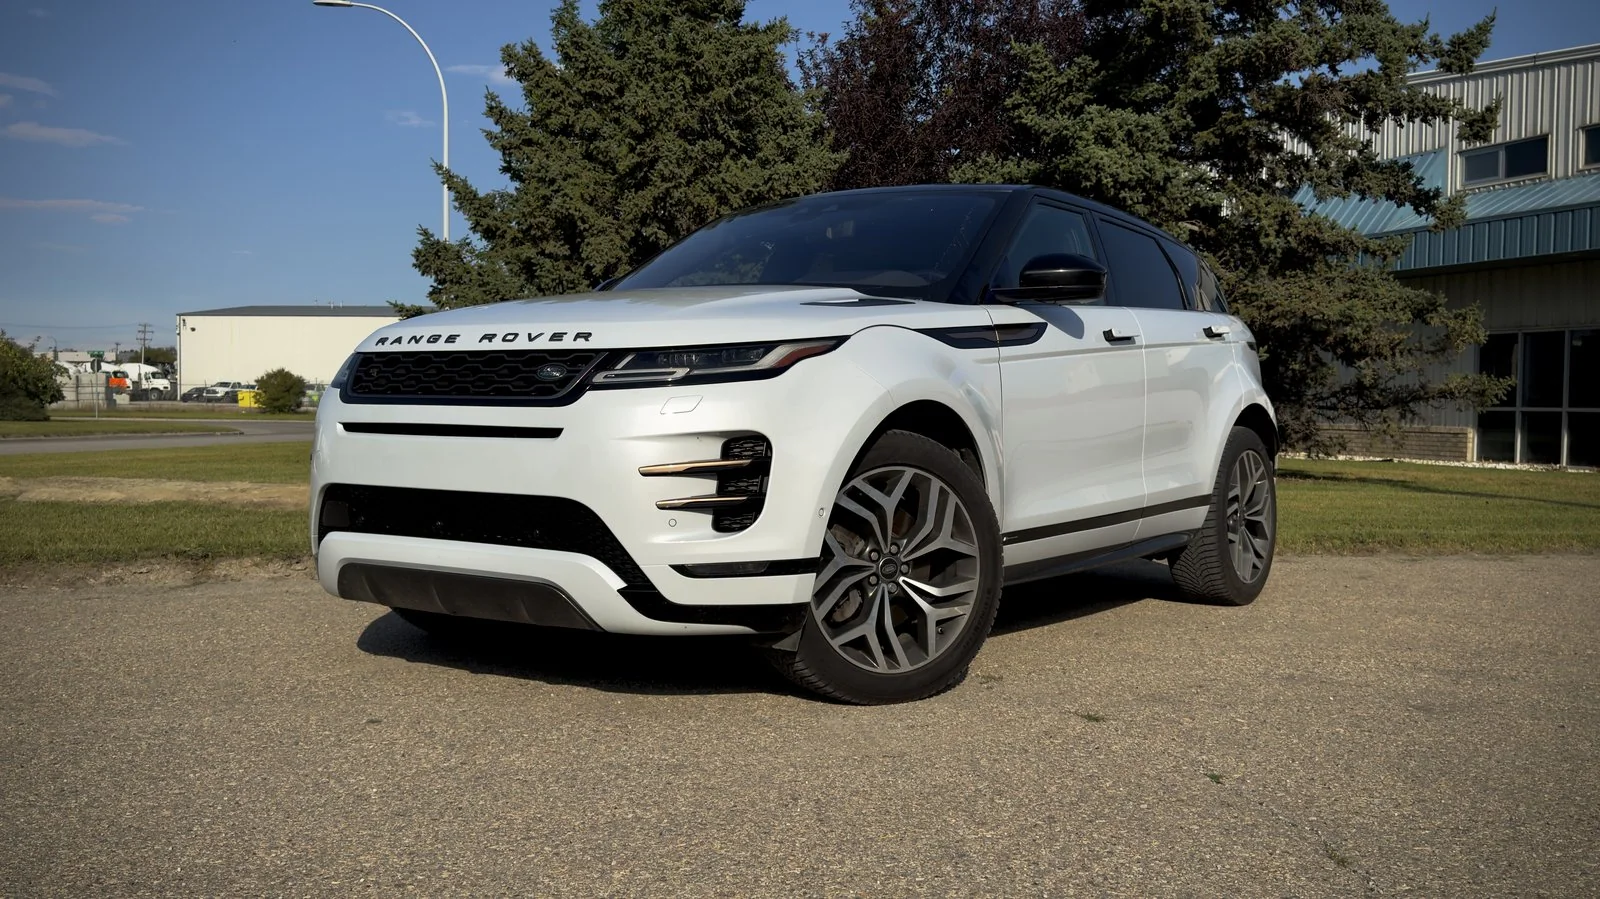
2020 Land Rover Range Rover Evoque P250 First Edition
$178 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $6,381
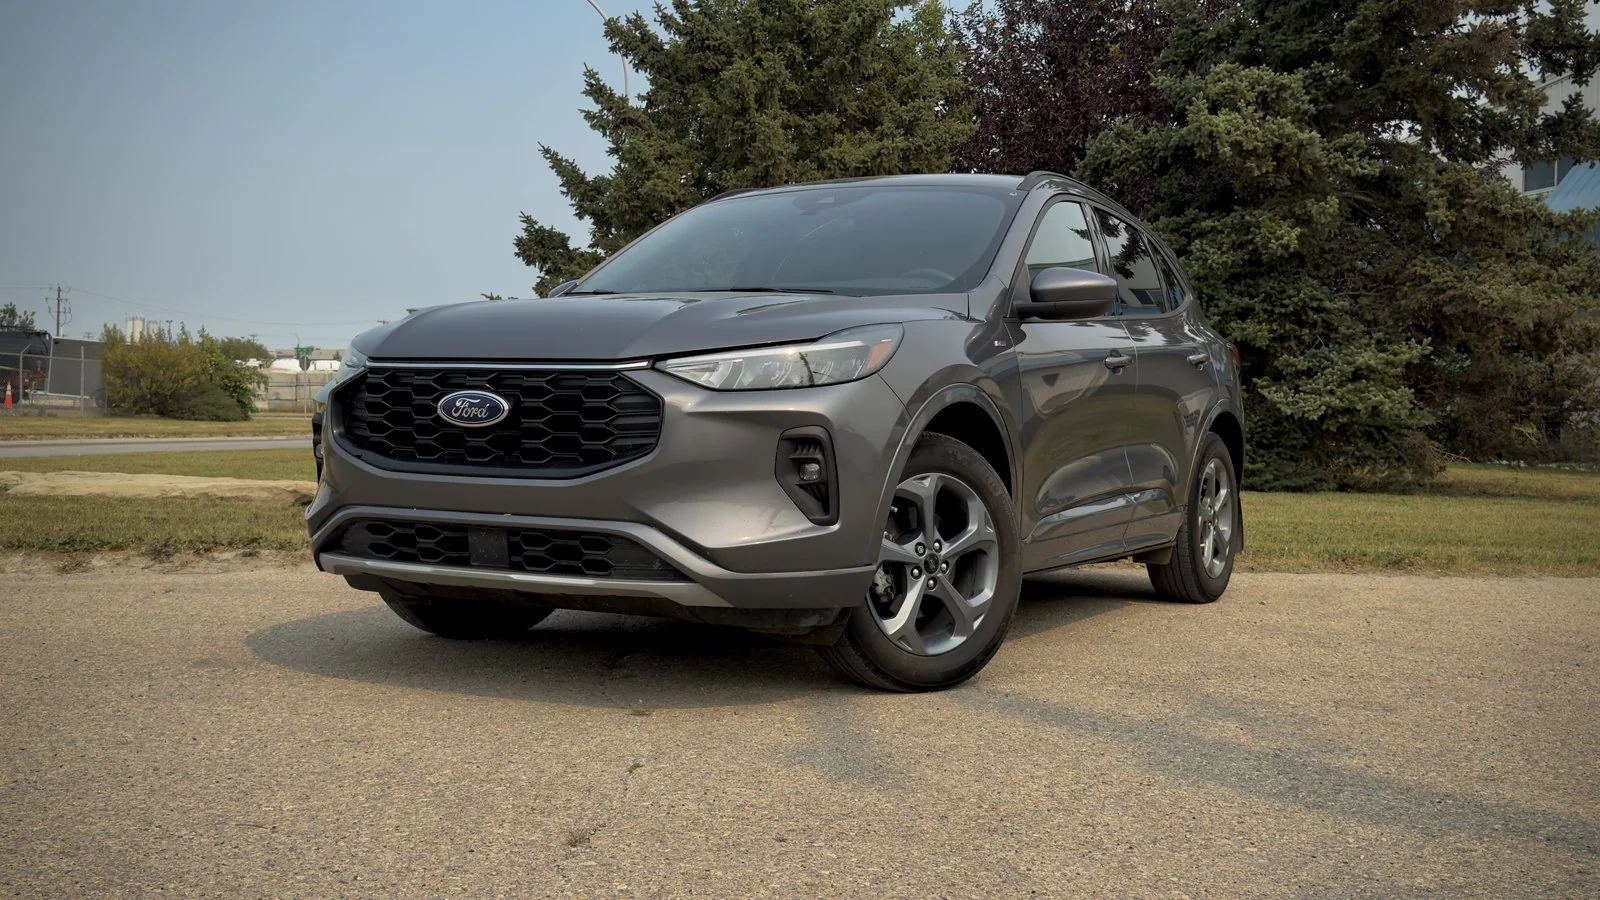
2024 Ford Escape Hybrid ST-Line
$178 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $6,381
OAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Car loan income verification: common questions
How many pay stubs do I need for a car loan?
There is no one number. Every lender sets its own list. Some ask for one proof of employment, others for your last two pay stubs plus a T4 or Notice of Assessment. Having your last two pay stubs and your latest T4 ready covers most lists. Each lender decides each file.
Can I use a letter from my employer instead of pay stubs?
Some lenders accept one. A letter from your employer that confirms your position, start date and pay is on several lenders' lists of proof, while others want pay stubs. Tell us what you have when you apply. We review every application and call you back.
Do overtime and bonus pay count as income?
It depends on the lender. Each lender decides how much of your extra pay it counts. A pay stub shows only one pay period, so a T4 slip, which adds up the year's wages, commissions and bonuses, or a letter from your employer can help show the pattern. Every lender decides each file.
Do car lenders ask for bank statements?
Some do. Bank statements that show your pay going into your account are a common proof of income, and some lenders ask for a few months of them. How many months a lender wants varies, so ask before you pull them.
Does being on probation hurt a car loan application?
Lenders set their own rules on time on the job. One Canadian auto lender publishes a minimum of three months on the job, with exceptions for a similar new job after a year at the last one. Other lenders differ. Tell us your start date and your pay when you apply. We review every application and call you back.
What if I am self-employed or paid by contract?
Lenders usually look at tax documents, such as your T1 and Notice of Assessment, and sometimes bank statements, instead of pay stubs. Our self-employed car financing page explains what to bring. Every lender decides each file, and we review every application and call you back.
Sources (pages opened October 5, 2026): CIBC: Personal Car Loan; ATB: Navigating car loans in Alberta; TD Auto Finance: what to bring; Affinity Credit Union: loans; RBC: how to get a car loan; Santander Consumer Bank (Canada): our loans; Loans Canada: letter of employment; Loans Canada: car loan approval; Canada Revenue Agency: employment income; Government of Alberta: termination and lay-off. These are public pages, quoted to show what lenders publish. Every lender sets its own rules, so check the lender’s own page before you rely on a detail.
Last reviewed October 2026 by the Shift Happens finance team
What Our Customers Say
“Great experience with the team at Shift. The whole experience was easy from start to finish. Wes was quick to respond and answer all my questions. Luke was a dream with the paperwork.”
“The buying experience was handled very professionally. Wes was very attentive and presented everything in an open and honest manner that gave me the reassurance that I made a good purchase.”
“I honestly can't thank Luke enough. From start to finish he was patient, respectful, transparent, and genuinely cared about helping me find the right vehicle instead of just making a sale.”
Other Financing Options
See what you pre-qualify for
Apply online. We review every application and call you back.
★★★★★ 118+ Google Reviews · AMVIC Licensed · Free Delivery 300km