
Car Loan With a Wage Garnishment in Alberta
Can I get a car loan in Alberta with a wage garnishment?
It depends on the file. Lenders usually ask about the pay you keep after the garnishment, the debt behind it and when it ends. Papers that show the end date help. Every lender decides each file, so we cannot promise a result. We review every application and call you back.
Who this page is for
- You work, your pay is steady, and part of it is being garnished now or was in the past.
- You want to know what a lender sees on your file and what to bring.
- You want plain information, not legal advice.
This page is part of our guide to second chance auto financing in Alberta. It covers how a car lender may read a wage garnishment. It is general information, not legal advice.
General information, not legal advice
Key Facts
- Who this is for
- Working, with a garnishment now or in the past
- What lenders usually ask about
- The pay you keep, the debt behind it, when it ends
- A court garnishment in Alberta lasts
- 2 years from the day it is issued, unless the creditor renews it
- What to bring
- Pay stubs, the garnishment papers, proof of where it stands
- Lender network
- 21+ lenders
See what you pre-qualify for
A few quick answers. No commitment.
Can I get a car loan while my wages are being garnished?
It depends on the file. A garnishment means part of each paycheque goes to someone else to pay a debt. A lender reading your file usually wants to know three things.
- How much pay do you keep? The garnishment comes out before the money reaches you, so your deposits are the smaller amount. A car payment has to fit the pay you actually keep.
- What debt is behind it? A garnishment is one way a debt gets collected. A lender will want to know what the debt is, how much is left and whether it is going down.
- When does it end? A garnishment that is nearly finished is a different file from one that has just started. The section on end dates below explains why.
Lenders differ. Some will look at a file with a garnishment still running. Others will want it finished first. We cannot promise what any lender will decide. We review every application and call you back, and every lender decides each file.
If the garnishment followed other credit trouble, our guides to car loans with accounts in collections and getting a car loan after a repossession cover those parts of the file.
What does a garnishment show on my file?
A lender can see a garnishment in three places.
- Your pay stubs. A garnishment usually shows up as its own deduction line, with the pay you keep below it.
- Your bank statements. Your deposits are the pay after the garnishment.
- Your credit report. The Financial Consumer Agency of Canada says a credit report can list court decisions related to your credit and debts sent to collection agencies. If a court judgment is behind your garnishment, it says credit bureaus usually keep the judgment on your report for 6 years, and Equifax says the same.
Other kinds of garnishment, such as for support, fines or taxes, may not show up on a credit report the same way. The way to know is to read your own report. Equifax says you can order a free copy of your credit reports from Equifax or TransUnion, the two main bureaus. Check what is on it before you apply.
How much of my pay can be garnished in Alberta?
It depends on who is collecting. This section covers a garnishment that comes from a court judgment under Alberta’s Civil Enforcement Act. Support payments, government fines and federal debts follow other rules, shown in the next section.
Here is how the Act and its Regulation work. Each month, the garnishment takes only the part of your net pay that is above a protected amount.
- Net pay means your pay after income tax, Canada Pension Plan contributions and unemployment insurance (EI) contributions, and nothing else.
- The protected amount starts at $800, plus $200 for each dependant. It then grows by half of every dollar of net pay above that, up to a ceiling of $2,400, plus $200 for each dependant.
- A dependant includes your spouse or adult interdependent partner and a child under 18 who lives with you.
- A court can change these amounts for a particular case.
For example, with $3,900 of net pay a month and no dependants, the protected amount is $2,350. The garnishment takes the rest, $1,550, and you keep $2,350. This illustrates the formula; it is not legal advice, and your own figures can differ.
Do all garnishments work the same way?
No. The rules depend on what the debt is. Here are four common kinds, from the government pages listed at the foot of this page.
A court judgment
for example, a lender or a business you owe
- Who sends it
- Your employer is served with a garnishee summons.
- How much of your pay
- The part of your net pay above a protected amount (the formula above).
- How long it lasts
- 2 years from the day it is issued. The creditor can renew it, with no limit on renewals. It ends sooner if the debt is paid, the creditor lifts it or a court ends it.
Court-ordered support
child, spousal or partner support, through Alberta's Maintenance Enforcement Program
- Who sends it
- Your employer gets a Support Deduction Notice.
- How much of your pay
- At most 40% of your gross wage, unless you agree to pay a higher amount.
- How long it lasts
- 12 years from the day it is issued.
Unpaid traffic or Criminal Code fines
Traffic Safety Act fines, through Alberta's Fines Enforcement Program
- Who sends it
- Your employer sends part of your wages to the province.
- How much of your pay
- Part of your wages.
- How long it lasts
- Until the debt is paid. Money owed to the Crown has no statute of limitations.
A federal debt
for example, tax owed to the Canada Revenue Agency
- Who sends it
- Your employer gets a requirement to pay or a similar notice.
- How much of your pay
- The amount is set on the notice itself.
- How long it lasts
- Generally 90 days, 1 year or until the debt is paid in full, with some exceptions. The notice says which.
If you are not sure which kind you have, the papers your employer received say who sent them. A lender will usually want to know too.
Why does the end date of a garnishment matter?
Because a lender is reading your pay for the months ahead, not just today. A garnishment with a clear end changes what your pay looks like once it stops. One with no clear end leaves a lender guessing.
For a court garnishment in Alberta, the Act sets an outer limit: a garnishee summons expires 2 years after the day it is issued. But the creditor can renew it, in the 60 days before it expires, for another 2 years. The Regulation says there is no limit on the number of times it can be renewed.
It can also end sooner. The Act says a garnishee summons stays in effect until the earliest of four things:
- it expires;
- your employer has paid the full amount on the summons to the court clerk;
- the creditor tells your employer it is no longer in effect; or
- a court ends the garnishment proceedings.
So a date on the papers tells you when the garnishment ends unless the creditor renews it. What a lender can rely on is proof that it did end: the creditor’s notice that it is no longer in effect, and pay stubs without the deduction line. If the creditor sends or copies that notice to you, keep it. The other kinds in the section above end by their own rules.
What should I bring if my wages are garnished now, or were?
Bring what shows your pay, the garnishment and where it stands. Having it ready saves a lender from chasing it.
- Your last two pay stubs. They show the garnishment line and the pay you keep.
- A copy of the garnishment papers. Your employer received them. The Canada Revenue Agency says it sends the person who owes the debt a copy of any garnishment request. If you do not have a copy, ask your payroll office or whoever is collecting.
- Proof of where it stands: what is still owing and when it should end. A letter from the creditor, the court or the agency collecting is the best proof.
- If it has ended: the notice or letter that says so, plus a recent pay stub without the deduction line.
- The usual papers: government photo ID, proof of address, a void cheque and recent bank statements.
The quickest start is the online application. We review every application and call you back. Or call us at (825) 736-4438. If your pay is not the usual kind, see what car lenders verify when you work.
What can stop or change a garnishment?
This is where legal advice starts, and we do not give it. Here is what the government pages say.
- A court can change it. The Regulation says the Court, on application, may modify the minimum or maximum employment earnings exemption. That is a question for a lawyer.
- A consumer proposal or bankruptcy can stop it for the debts it covers. The federal Office of the Superintendent of Bankruptcy says the stay of proceedings stops most collection actions, including wage garnishment. It also says the stay usually does not apply to secured debts, like a car loan, or to child or spousal support. See car loans during a consumer proposal for the financing side.
- A licensed insolvency trustee can go through your options. The Office says that if you are facing serious financial difficulties, you will want to meet with one, and that trustees typically do not charge for the first meeting.
We cannot give legal advice or negotiate with the creditor. We can look at your file as it stands today.
What would a car payment look like while part of my pay is garnished?
Here is one example, built with the Alberta formula above. The pay is an example: $3,900 of net pay a month and no dependants.
Worked example
- Net pay, before the garnishment
- $3,900 a month
- Protected from the garnishment
- $2,350
- Taken by the garnishment
- $1,550 a month
- Pay you keep
- $2,350 a month
- Vehicle
- used SUV, $22,000
- Example rate
- 16.9% APR (Subprime example)
Payment: ~$488/mo ($22,000 over 72 months)
That is about 21% of the $2,350 you keep while the garnishment runs, and about 13% of $3,900 once it ends.
Example, not an offer. Your rate depends on your file; rates run from 4.99% APR (prime) to 29.9% APR (deep subprime).
The same payment takes a bigger share of what you keep while the garnishment runs. That is one reason lenders ask when it ends, and why a smaller loan or a bigger down payment can matter more when part of your pay is spoken for. To try your own numbers, use the payment calculator. For how pay and credit fit together, see how Alberta car loans work with good income and bad credit.
Example payments are estimates. Not an offer.
Vehicles in stock right now
Browse all inventory →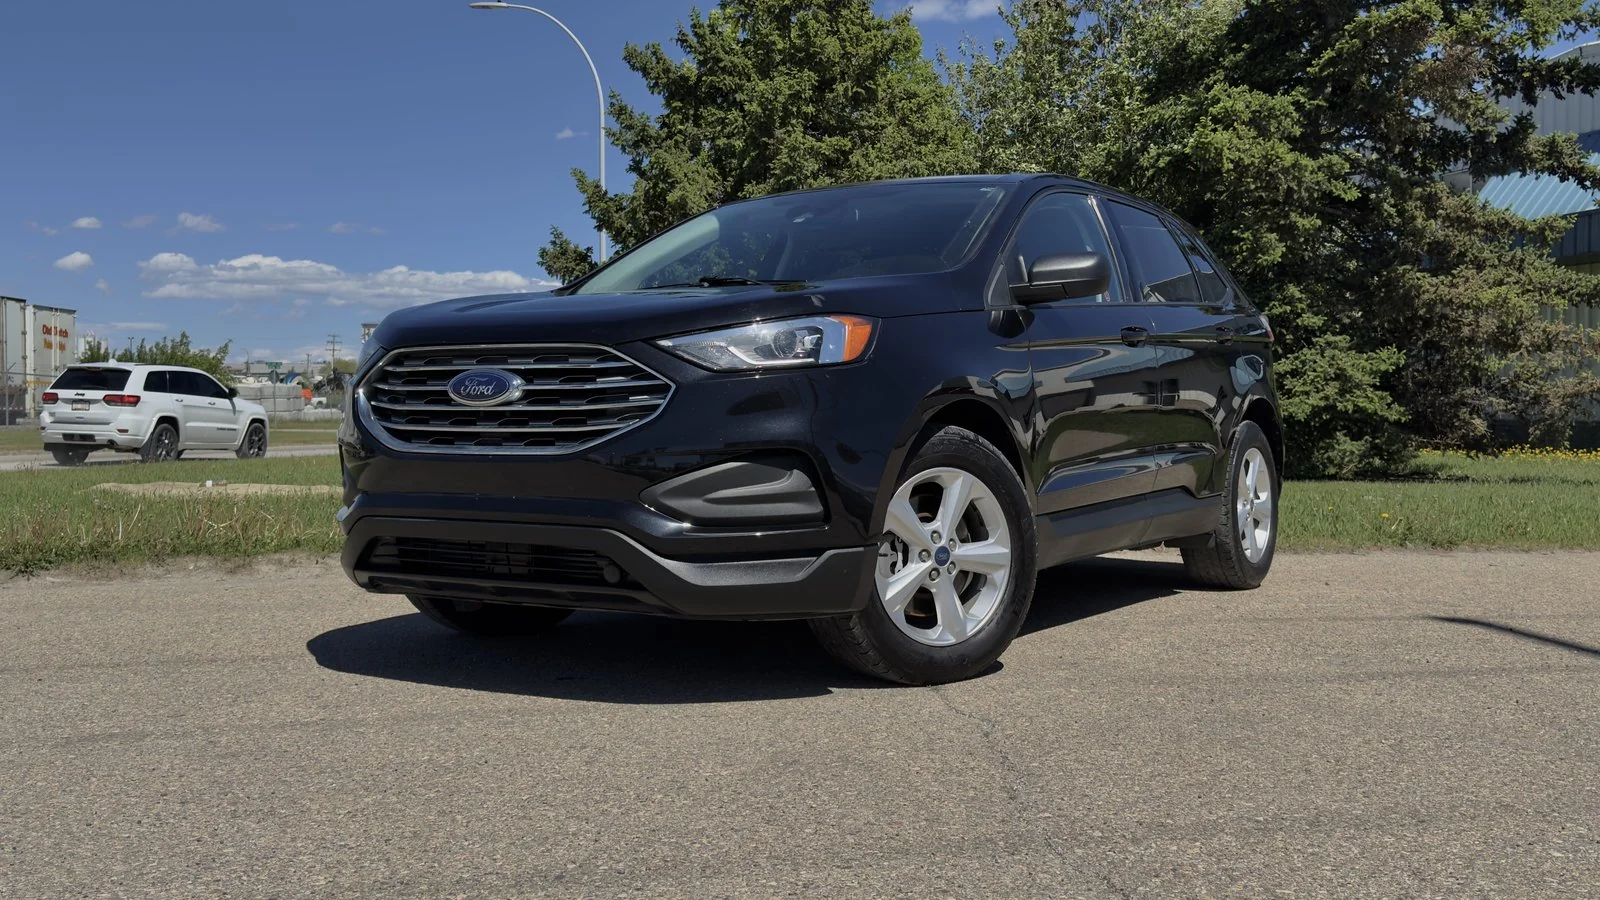
2020 Ford Edge SE
$150 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $5,398
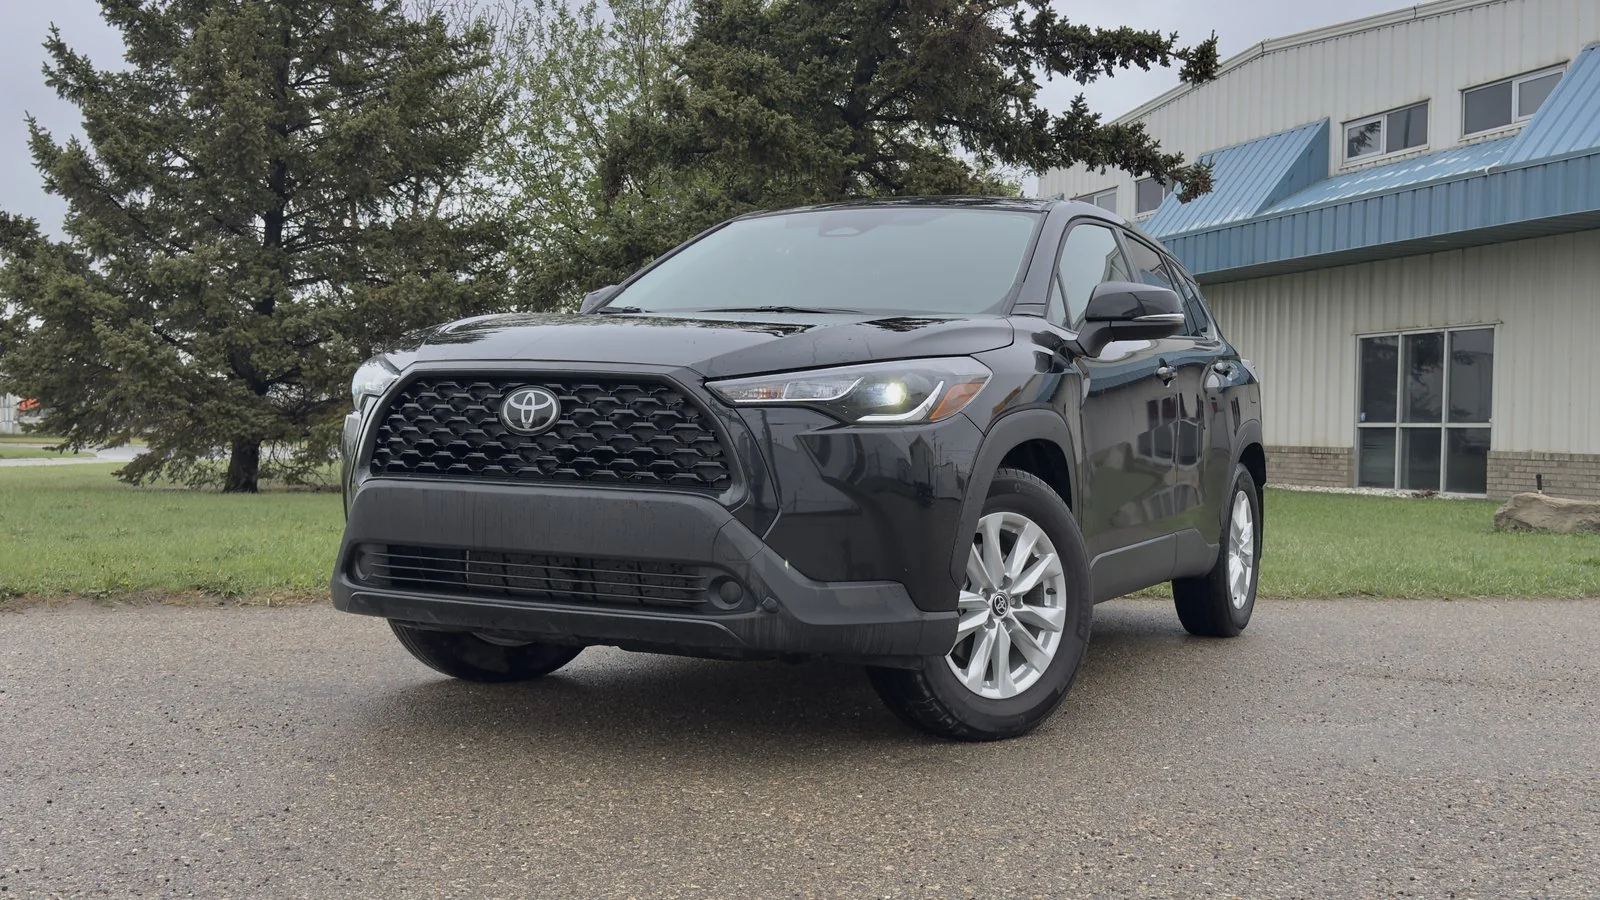
2024 Toyota Corolla Cross LE
$229 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $8,225
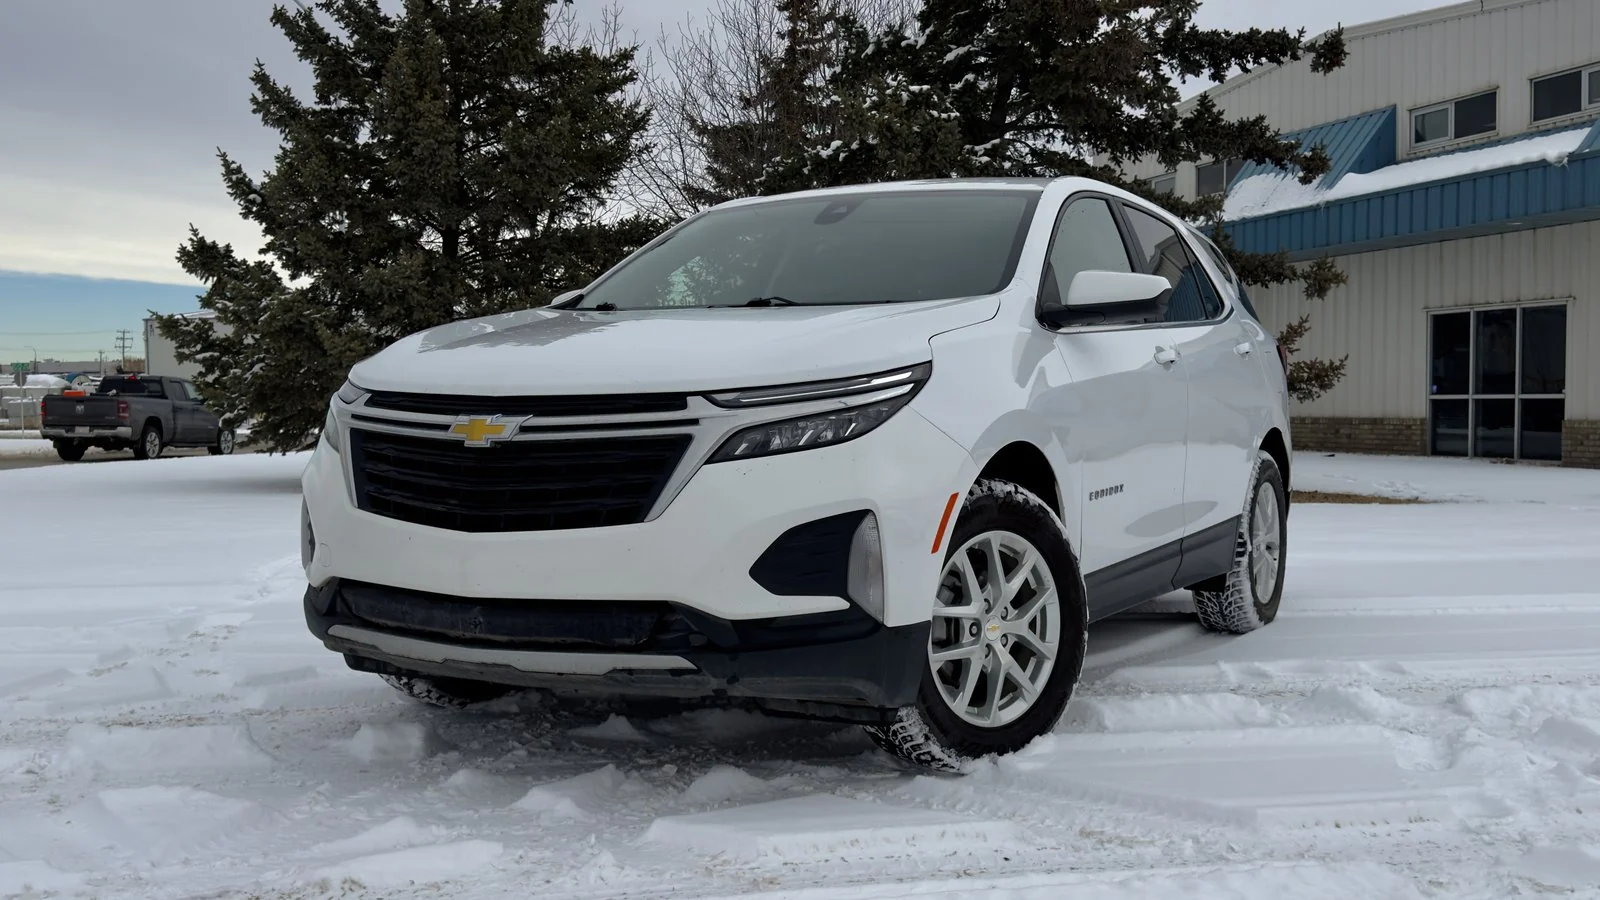
2022 Chevrolet Equinox LT
$157 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $5,644
OAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Car loans with a wage garnishment: common questions
Can I get a car loan with a wage garnishment in Alberta?
It depends on the file. Lenders usually ask about the pay you keep after the garnishment, the debt behind it and when it ends. Papers that show the end date help. We cannot promise what a lender will decide. We review every application and call you back, and each lender decides each file.
Does a wage garnishment show on my credit report?
A credit report can list court decisions related to your credit and debts sent to collection agencies. If a court judgment is behind your garnishment, credit bureaus usually keep the judgment on your report for 6 years. Other kinds of garnishment may not show up the same way, so read your own report. You can ask Equifax and TransUnion for a free copy.
How long does a wage garnishment last in Alberta?
It depends on the kind. A garnishee summons from a court judgment expires 2 years after it is issued, but the creditor can renew it with no limit on renewals, and it ends sooner if the debt is paid, the creditor lifts it or a court ends it. A support deduction notice stays in effect 12 years from the day it is issued. Unpaid fines are collected until they are paid. A federal garnishment is generally valid for 90 days, 1 year or until the debt is paid in full. The notice your employer received says which kind you have.
How much of my pay can be garnished in Alberta?
For a court garnishment under Alberta's Civil Enforcement Act, the garnishment takes only the part of your monthly net pay above a protected amount. The protected amount starts at $800 plus $200 for each dependant, then grows by half of each dollar above that, up to $2,400 plus $200 for each dependant. A court can change the amounts. Support payments, fines and federal debts follow other rules. This is general information, not legal advice.
Can a car lender garnish my wages if I miss payments?
Under Alberta's Civil Enforcement Act, a judgment creditor can ask the court clerk to issue a writ of enforcement on a court judgment, and the Act's garnishment rules are for enforcing a writ. So for this kind of garnishment, a court judgment comes first. What a lender can do about missed payments depends on your contract and your situation. If you are behind, talk to your lender early, and ask a lawyer or a licensed insolvency trustee about your own case.
Would a consumer proposal stop a wage garnishment?
The federal Office of the Superintendent of Bankruptcy says that once a bankruptcy or consumer proposal is filed, a stay of proceedings stops most collection actions, including wage garnishment, for the debts it covers. It also says the stay usually does not apply to secured debts, like a car loan, or to child or spousal support. Whether it fits your situation is a question for a licensed insolvency trustee.
What should I bring to a car loan application if my wages are garnished?
Your last two pay stubs, a copy of the garnishment papers, proof of what is still owing and when it should end, and the creditor's letter if it has ended. Add your photo ID, proof of address, a void cheque and recent bank statements.
Sources (pages opened October 5, 2026): Alberta King's Printer: Civil Enforcement Act (current as of June 1, 2024); Alberta King's Printer: Civil Enforcement Regulation (current as of April 30, 2025); Government of Alberta: Maintenance Enforcement Program; Government of Alberta: Fines Enforcement Program; Canada Revenue Agency: Garnishing your income and accounts; Canada Revenue Agency: How to process a garnishment from the CRA; Office of the Superintendent of Bankruptcy: Creditors contacting you after you file a bankruptcy or a proposal; Office of the Superintendent of Bankruptcy: Consumed by debt? Information for consumers; Financial Consumer Agency of Canada: How long information stays on your credit report; Financial Consumer Agency of Canada: Credit report and score basics; Equifax Canada: How long does information stay on your credit report?. These are public pages, quoted to show what the rules say. Rules change, and a court can change how they apply to you, so check the source page and ask a lawyer or a licensed insolvency trustee about your own case.
Last reviewed October 2026 by the Shift Happens finance team
What Our Customers Say
“I honestly can't thank Luke enough. From start to finish he was patient, respectful, transparent, and genuinely cared about helping me find the right vehicle instead of just making a sale.”
“Luke and Wes were beyond wonderful and helpful to deal with. Luke went above and beyond multiple times to make this purchase happen. Wouldn't hesitate to recommend to anyone I know!”
“Had an amazing experience at this dealership from start to finish. Huge thanks to Luke for being professional, knowledgeable, and genuinely making the whole process stress-free.”
Other Financing Options
See what you pre-qualify for
Apply online. We review every application and call you back.
★★★★★ 118+ Google Reviews · AMVIC Licensed · Free Delivery 300km