
Real Car Loan Approvals in Alberta: Our Funded Deals by Score and Income
December 2025 to September 2026 · from our own records · percentages only
Who actually gets a car loan in Alberta when their credit took a hit?
From December 2025 to September 2026, 64% of the car loans we funded with a credit score on file were for scores under 600. Most had steady pay: 88% of those with an income on file earned $3,800 or more a month. Every lender decides each file.
Who this page is for
- You work, your credit took a hit, and you want to know whether people like you really get financed.
- You would rather see real numbers than a promise.
- You want to know what your score and your pay each do to a car loan.
This page is part of our guide to car loan rates in Alberta, which shows what each credit tier usually pays. Here we show who the loans actually went to, drawn from our own records.
Key Facts
- Period
- December 2025 to September 2026
- Credit score under 600
- 64% of funded deals with a score on file
- Income $3,800+ a month
- 88% of funded deals with an income on file
- Earning $3,800+ with a score under 650
- 76% of those deals
- What we publish
- Percentages only. No names, deal dates, vehicles, lenders, rates or amounts
See what you pre-qualify for
A few quick answers. No commitment.
Funded car loans by credit score
Not every funded deal has a credit score on file, so these shares are out of the deals that do. Thin-file scores are left out, and a band too small to keep anonymous is merged with its neighbour, which is why some bands are wider than others.
| Credit score | Share of funded deals |
|---|---|
| 750+ | 13% |
| 600–749 | 23% |
| 500–599 | 23% |
| 450–499 | 26% |
| 300–449 | 15% |
64% of these deals had a score under 600, and 41% a score under 500. A low score did not stop these loans. To see what each score band usually pays, read car loan rates by credit score, or for a score around 600, a 600 credit score car loan on a steady income.
Funded car loans by monthly income
These shares are out of the funded deals with a gross monthly income on file. Yearly figures are divided by twelve.
| Monthly income | Share of funded deals |
|---|---|
| Under $3,800 | 12% |
| $3,800–$5,200 | 22% |
| $5,200+ | 66% |
66% earned $5,200 or more a month. In our experience, steady pay you can prove is the part of a file that lenders lean on when the score is low. To see what your own pay can carry at each score band, use the car loan size by income and credit grid.
Score and income together
Among the funded deals where the borrower earned $3,800 or more a month and had a credit score on file, 76% had a score under 650. A score under 650 with steady pay was the most common combination we funded.
Combinations with too few deals to keep anonymous are not shown. If steady pay and a bruised score sounds like you, read how car loans work with good income and bad credit.
What these numbers do and do not tell you
They describe loans that went through. They do not count people who applied and were not financed, so they are not an approval rate and they are not a promise for your file.
Not every deal has every number. A credit score or an income is not recorded on every deal, so each share is out of the deals that had that number, not out of every deal we funded.
Your score mostly sets the rate. Rates in our lender programs run 4.99%–29.9% APR, depending on your file. Every lender decides each file, and we review every application and call you back.
How we work it out, and how we keep it anonymous
We take the deals marked funded in our own records for December 2025 to September 2026, then group them by credit score and by monthly income. The numbers here were drawn in October 2026.
We publish percentages only, from groups too large to point to any one person. There are no names, no dates of individual deals, no vehicles, no lenders, no rates and no amounts on this page.
Example payments are estimates. Not an offer.
Vehicles in stock right now
Browse all inventory →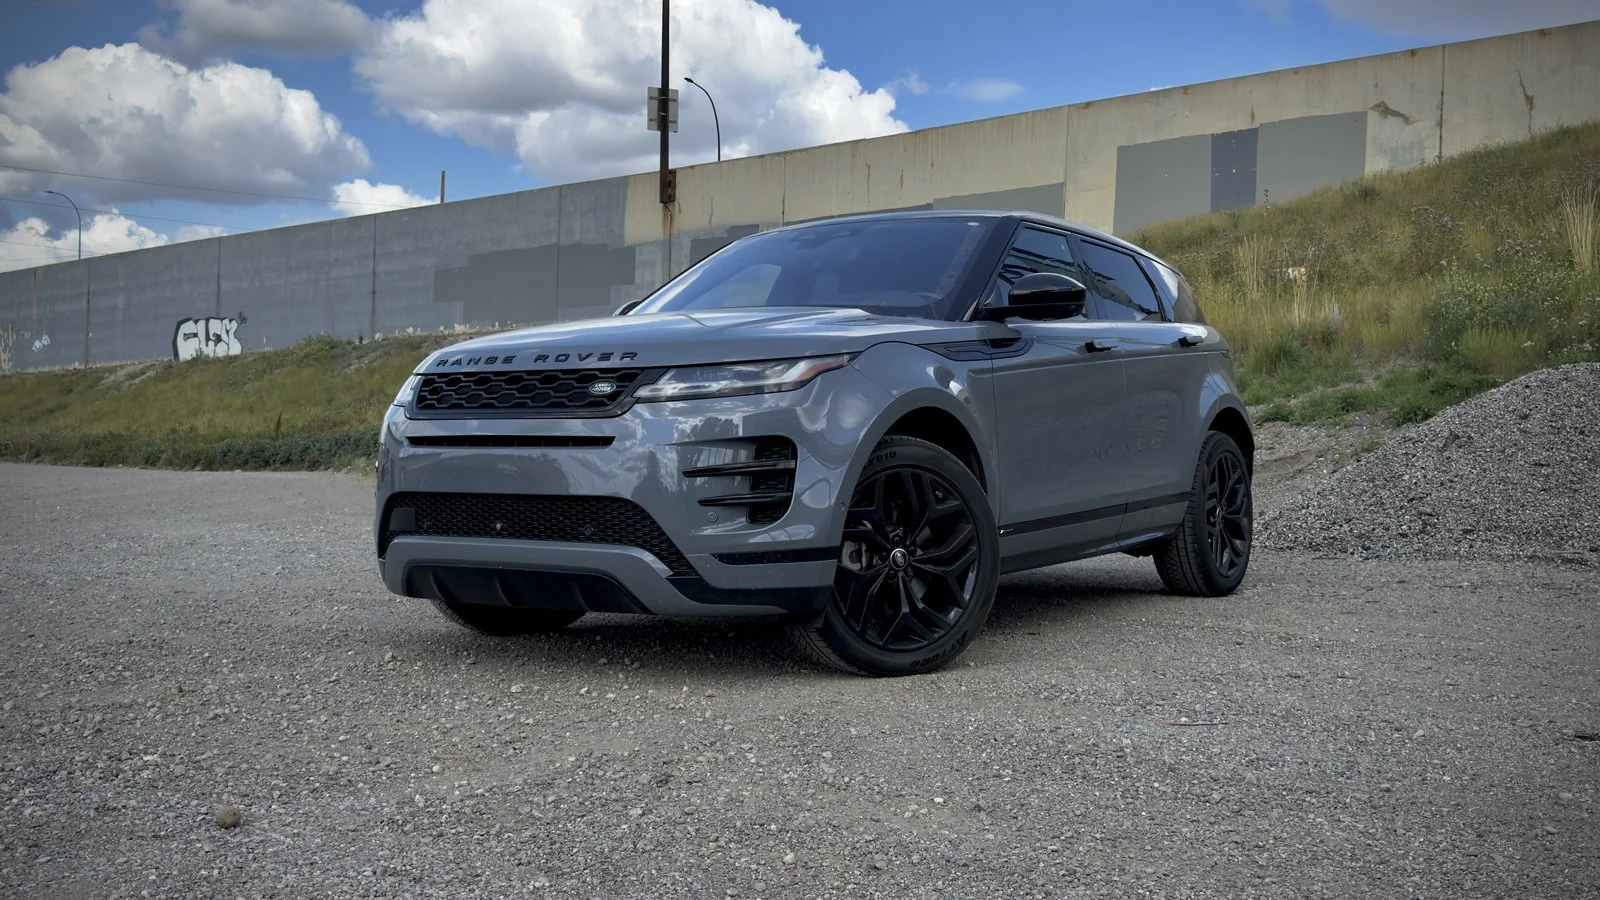
2021 Land Rover Range Rover Evoque R-Dynamic HSE
$212 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $7,609
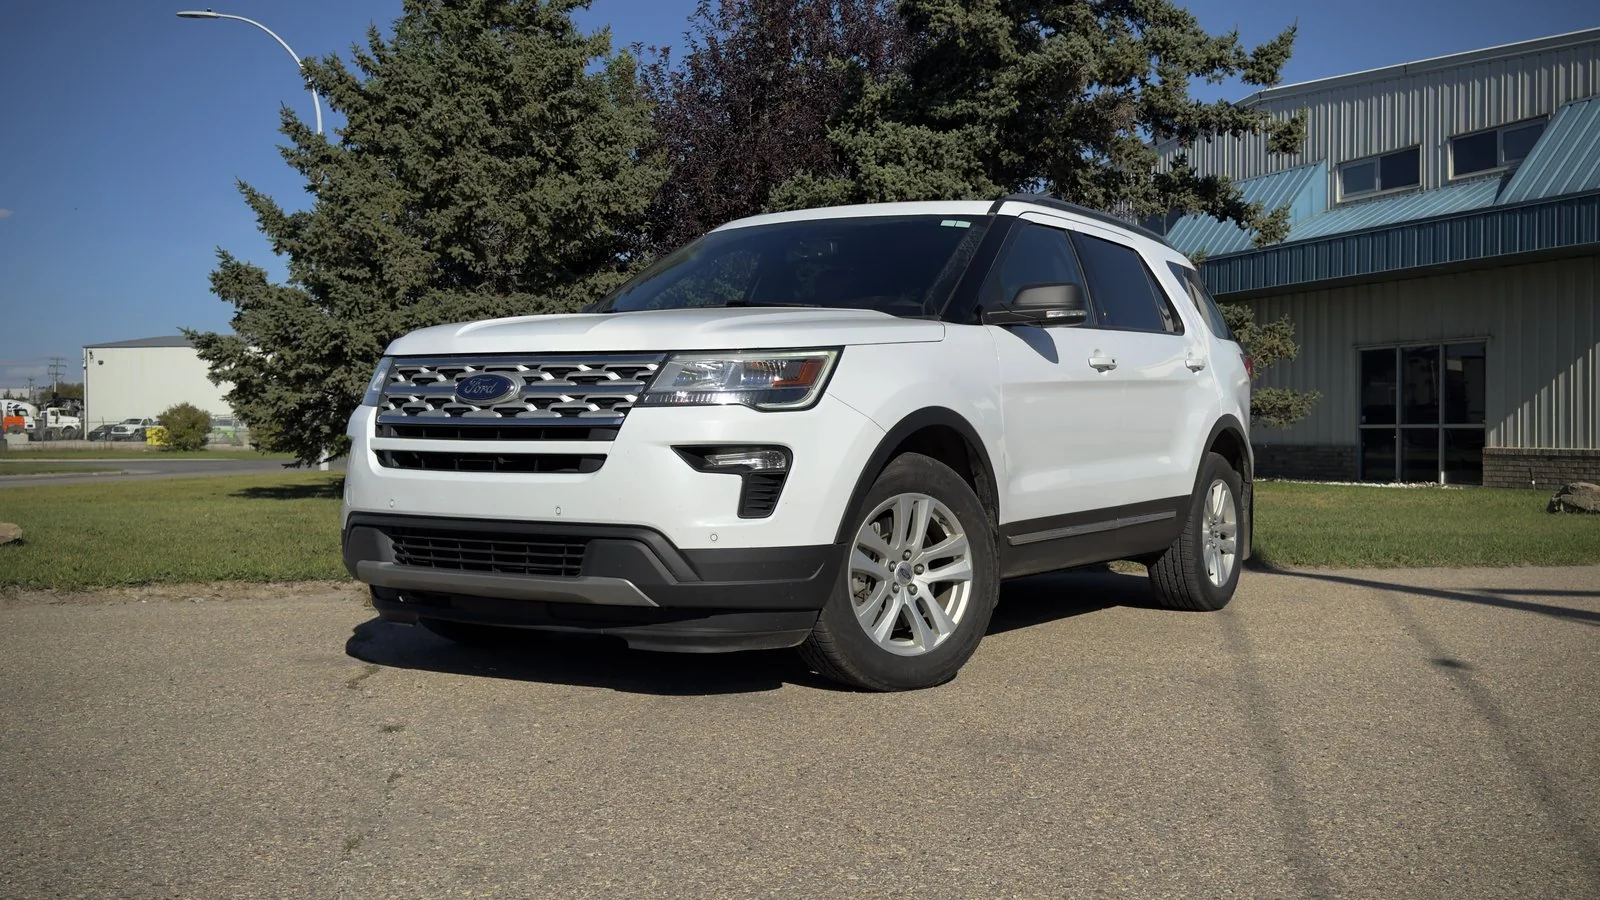
2019 Ford Explorer XLT
$123 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $4,416
 Reconditioning
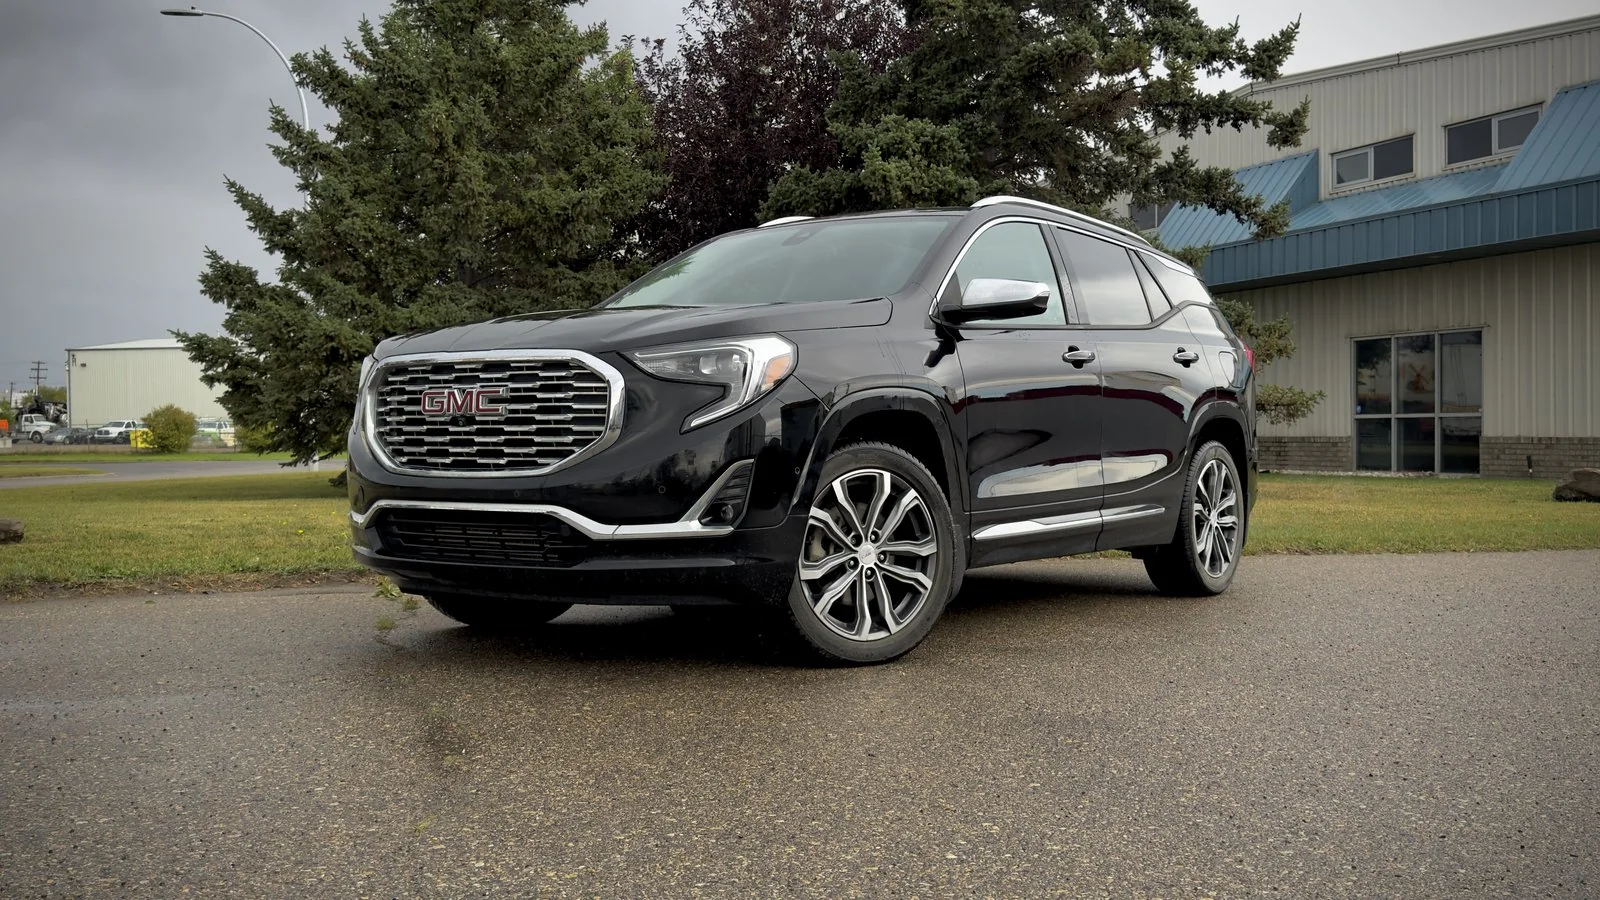
2020 GMC Terrain Denali
$175 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $6,260
OAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Funded car loans: common questions
Is this your approval rate?
No. These are funded deals only: car loans that went through. They cannot show who applied and did not get a loan, so they are not an approval rate. We publish them so you can see the kinds of files that do get financed. Every lender decides each file.
Can you get a car loan in Alberta with a credit score under 500?
Some people do. 41% of the funded deals with a credit score on file were under 500. Lenders look at your income and your job as well as your score, and your score mostly sets the rate (4.99%–29.9% APR depending on your file).
Does income matter more than the credit score?
Both matter. Your score mostly places you in a rate tier; your income shows whether you can carry the payment. In these numbers, 88% of the funded deals with an income on file earned $3,800 or more a month.
Could my own information be in these numbers?
No one can be picked out. We publish percentages only, from groups too large to point to any one person, and never names, dates of individual deals, vehicles, lenders, rates or amounts.
How often are these numbers updated?
From time to time, when we re-run them from our records. The period they cover is shown on this page: December 2025 to September 2026.
Last reviewed October 2026 by the Shift Happens finance team
What Our Customers Say
“The buying experience was handled very professionally. Wes was very attentive and presented everything in an open and honest manner that gave me the reassurance that I made a good purchase.”
“Had an amazing experience at this dealership from start to finish. Huge thanks to Luke for being professional, knowledgeable, and genuinely making the whole process stress-free.”
“Luke and Wes are a fantastic team! I purchased a Lincoln Corsair in pristine condition. They got me the best interest rate for my financing and even helped me find the best insurer.”
Other Financing Options
See what you pre-qualify for
Apply online in about three minutes. We review every application and call you back.
★★★★★ 118+ Google Reviews · AMVIC Licensed · Free Delivery 300km