
Car Loan With a 600 Credit Score on $4,000–$9,000 a Month
Can you get a car loan with a 600 credit score?
Many people do. A 600 score sits in the 600–649 band, where rates in our lender programs run 7.9–14.9%. Your pay and job history matter as much as the score. The table below shows an example loan for each pay from $4,000 up. Example, not an offer. Every lender decides each file.
This page is one column of our car loan grid by income and credit score, which covers every score band. The rates come from our guide to car loan rates in Alberta.
Who this page is for
- Your pay is steady and about $4,000 a month or more: a T4 job, your own business or a steady contract.
- Your score is around 600, in the 600–649 band, after a hit like missed payments or collections.
- You want to know what loan size and payment to expect before you apply.
Your score is lower, or your pay is below $4,000? The full grid covers every score band, from $3,500 a month.
Key Facts
- Score band
- 600 sits in 600–649
- Rates in this band
- 7.9–14.9% (4.99%–29.9% APR across all bands)
- Rate used below
- 11.4% APR, the middle of the band
- Pay shown
- $4,000–$9,000 a month
- Payment used
- 15% of gross monthly pay (a rule of thumb)
- Lender network
- 21+ lenders
What loan can $4,000–$9,000 a month carry with a 600 credit score?
This is the 600–649 column of our grid. Each row shows the payment near 15% of that pay, the most that payment would carry over 72 months at 11.4% APR (the middle of the band's range), and the bi-weekly payment on that loan.
| Gross pay a month | Payment near 15% of pay | Loan up to | Bi-weekly payment |
|---|---|---|---|
| $4,000 | $600/mo | Up to $31,000 | ~$275 |
| $4,500 | $675/mo | Up to $35,000 | ~$310 |
| $5,000 | $750/mo | Up to $38,500 | ~$341 |
| $6,000 | $900/mo | Up to $46,500 | ~$412 |
| $7,000 | $1,050/mo | Up to $54,500 | ~$483 |
| $8,000 | $1,200/mo | Up to $62,000 | ~$550 |
| $9,000 | $1,350/mo | Up to $70,000 | ~$620 |
Estimates only, not offers. Every row assumes a 72-month loan with $0 down. Your own rate depends on your file (4.99%–29.9% APR across all bands). Loan sizes are rounded down to the nearest $500, so a row never overstates. GST, fees and add-ons that you finance come out of the loan size, so the price of the car is lower. Every lender decides each file.
Is your score higher or lower than 600? The full grid for every score band has your column.
See what you pre-qualify for
A few quick answers. No commitment.
What does a lender look at besides a 600 score?
Your score places you in a band, and the band mostly sets the rate. Then the lender looks at the rest of your file.
Is your pay steady? How long you have had this job or business helps. If you changed jobs recently, tell us. See how lenders handle a new job.
Can you prove it? Pay stubs, a Notice of Assessment, or bank statements that show deposits. What car lenders verify when you work lists what to bring.
What do you already owe each month? Credit cards, loans, a consumer proposal payment. The more of your pay is already spoken for, the less room there is for a new payment.
How big is the loan next to the car and your down payment? A bigger down payment means a smaller loan. Read how down payments work. If your pay is a little short for the loan you want, a co-applicant can help; see do cosigners help with a bad credit car loan.
Steady pay carries a lot of weight when credit took a hit. Our guide to good income and bad credit explains why. Every lender decides each file, and we cannot promise what any lender will say.
What would a higher or lower score change?
Take pay of $5,000 a month, a payment of about $750. In the band just below (550–599, 14.9% APR in the example) that payment repays about $35,500. In the 600–649 band it repays about $38,500. In the band just above (650–749, 9.9% APR) it repays about $40,500.
So in this example, moving one band changes the loan by about $2,000 to $3,000. Moving up one pay row, to $6,000 a month, changes it by about $8,000. That is why pay is in the title of this page: it sets the payment you can carry. Your score still sets the rate, and a lower rate is real money over the life of a loan.
Your score can move as your credit rebuilds. See how long it takes to rebuild credit with a car loan, or how every band lines up in what credit score you need to buy a car in Canada.
What does the payment look like on a real car?
Here is one example: a buyer with steady pay and a score in the 600–649 band, looking at a used SUV.
Worked example
- Gross pay
- $5,000 a month
- Credit score
- 600–649
- Vehicle
- used SUV, $30,000
- Down payment
- $0
- Amount financed
- $30,000 over 72 months
- Example rate
- 11.4% APR (the middle of the 600–649 band)
Payment: ~$266/bi-weekly (or ~$577/mo)
That is about 12% of gross monthly pay. A common rule of thumb is to keep a car payment under 15% of gross pay.
Example, not an offer. Your rate depends on your file; rates run from 4.99% APR (prime) to 29.9% APR (deep subprime).
That car sits under the $38,500 ceiling for this pay, so the payment is lower than the rule-of-thumb amount. Your own numbers will be different. Try them in the payment calculator, or call us at (825) 736-4438 and we will go through your options. Shopping for a larger family SUV or minivan? See the income a three-row SUV or minivan loan needs at your score.
Example payments are estimates. Not an offer.
Vehicles in stock right now
Browse all inventory →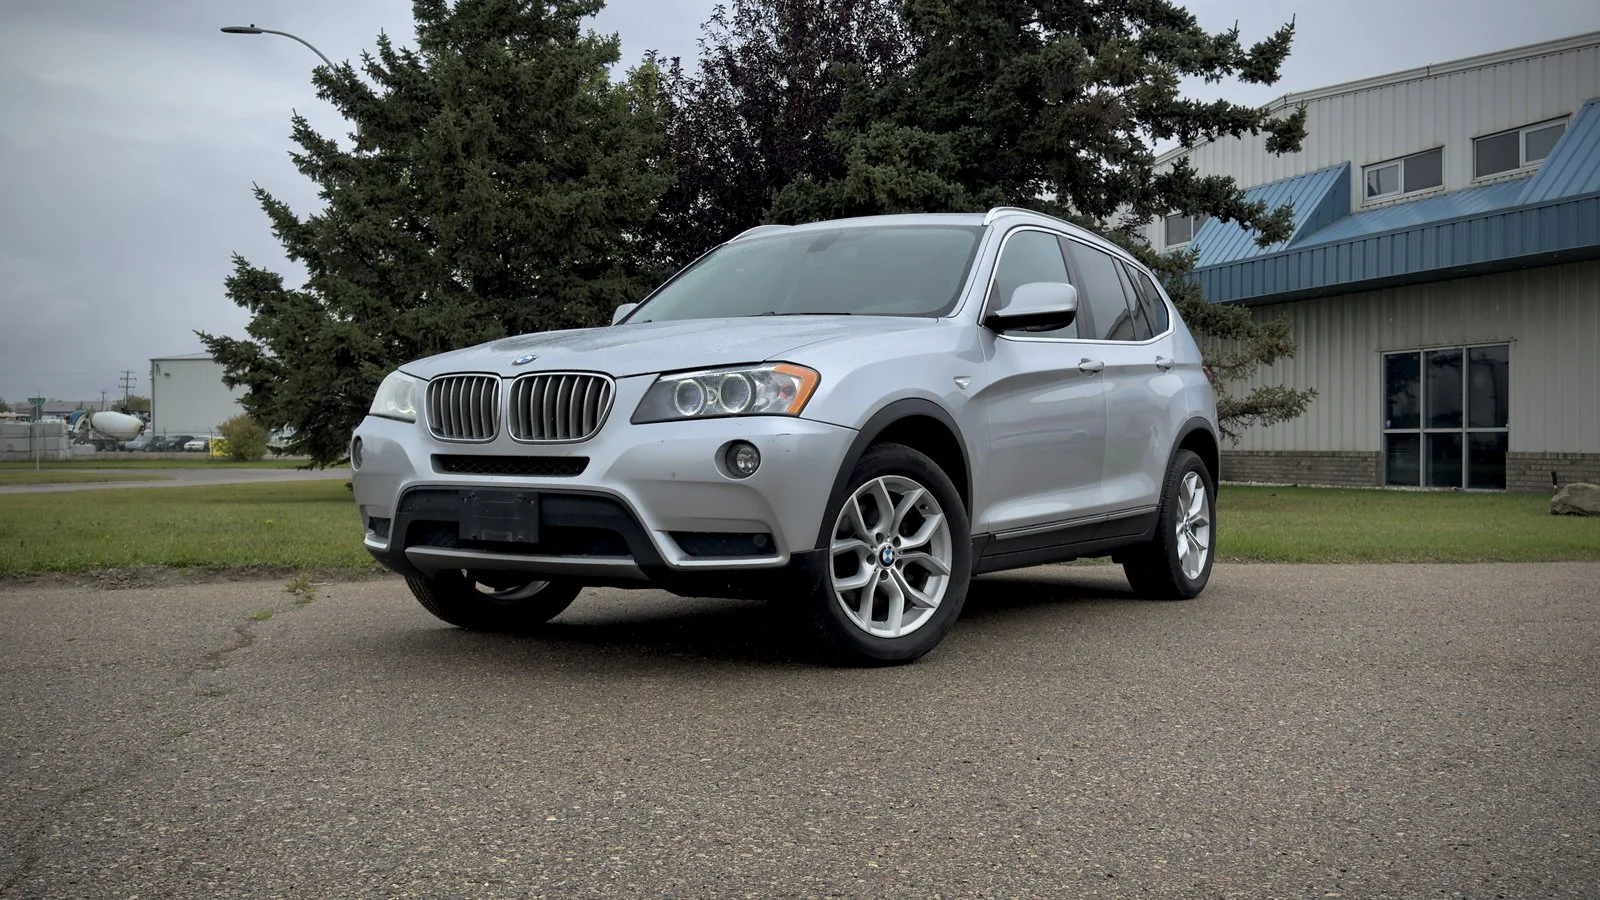
2014 BMW X3 xDrive28i
$75 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $2,698
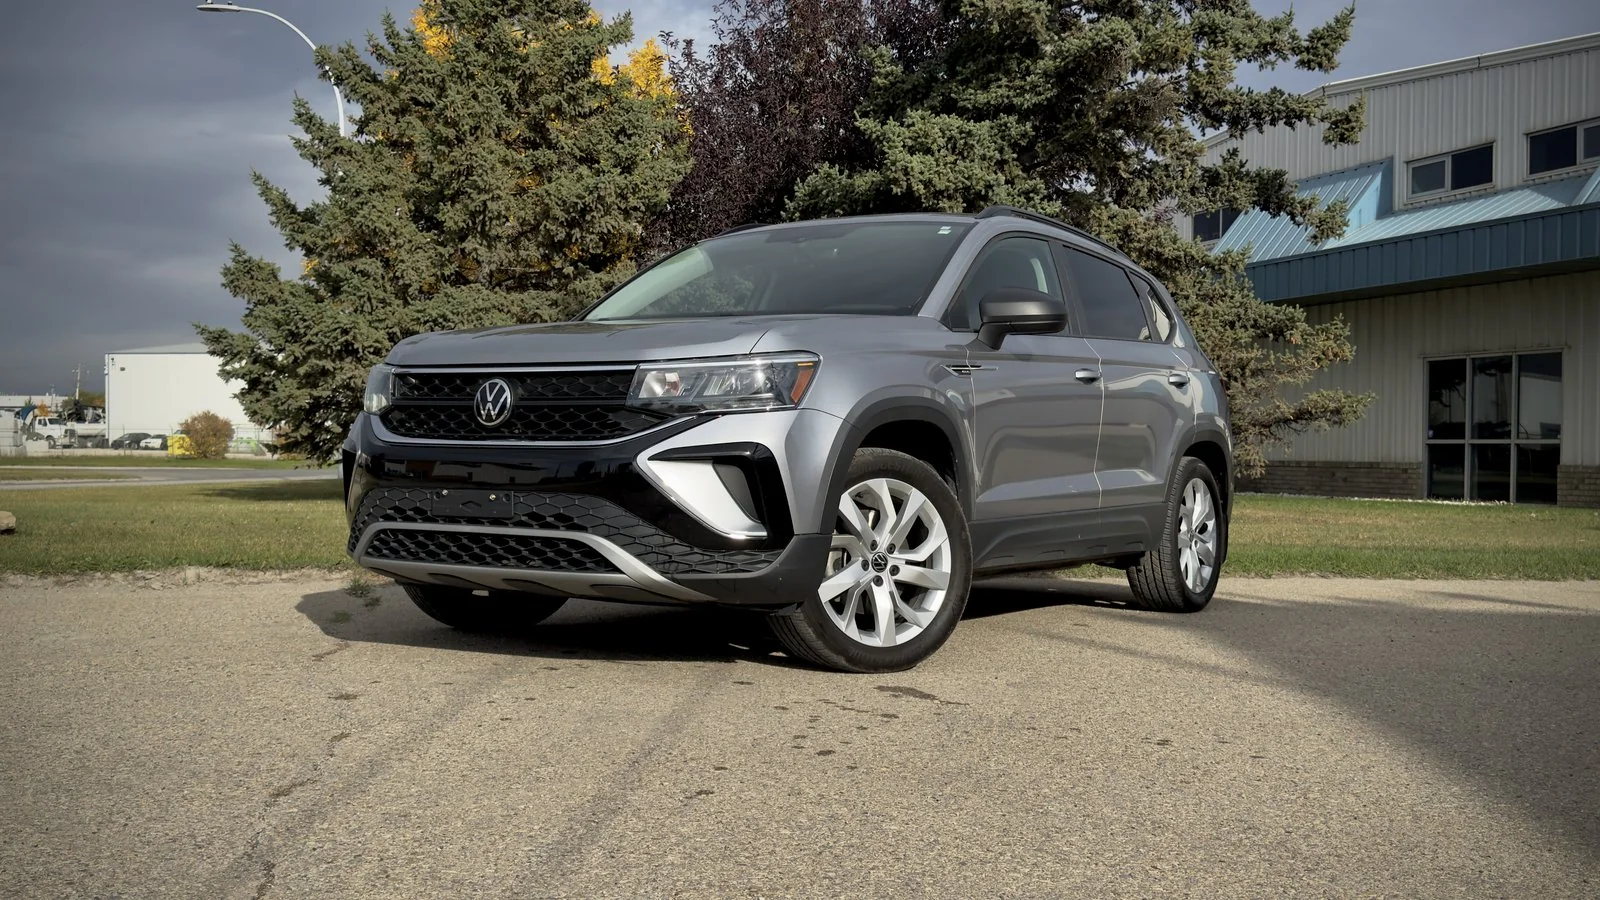
2023 Volkswagen Taos Trendline
$171 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $6,136
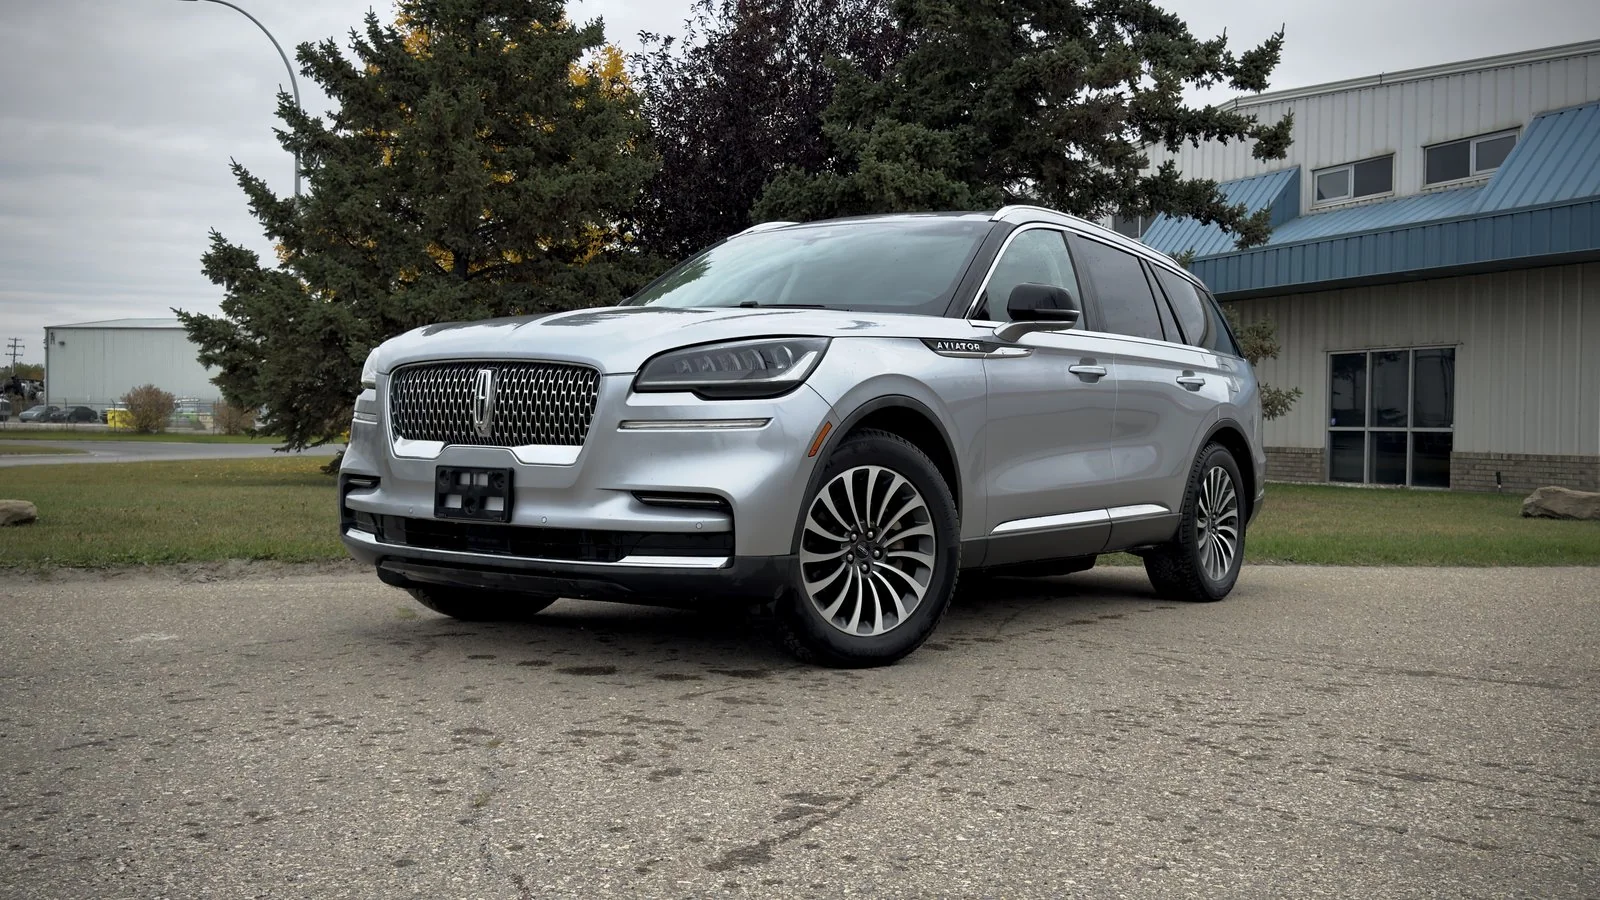
2022 Lincoln Aviator Reserve
$267 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $9,571
OAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
600 credit score car loan: common questions
Can you get a car loan with a 600 credit score?
Many people do. A 600 score sits in the 600–649 band, which is inside the range our lenders price. Your pay, your job history and what you already owe matter as much as the score. We cannot promise what any lender will decide. We review every application and call you back.
What interest rate does a 600 credit score get?
Rates in our lender programs for the 600–649 band run 7.9–14.9%. Where you land in that range depends on your file: your income, your job history, the car and your down payment. The table on this page uses the middle of the band, 11.4%, as an example. It is not a quote.
How much of a car loan can I get with a 600 credit score on $5,000 a month?
A payment near 15% of $5,000 is about $750 a month. Over 72 months at the example rate, that repays about $38,500. That is a ceiling, not a target, and not a lender's limit. A smaller loan means a smaller payment.
Do I need a down payment with a 600 score?
It depends on your file and your lender. A bigger down payment helps: you borrow less, the payment is smaller and the lender sees less risk. Tell us what you can put down and we will go through the options. Each lender decides each file.
Can a co-signer help me get a car loan with a 600 credit score?
It can help in two cases: when your income is a little short for the loan you want, and when you want to move up a band. The co-signer is legally responsible if payments stop, which is a big ask, even for family. Each lender decides each file.
What if I am self-employed or just started a new job?
Lenders can work with pay that is not a regular paycheque if you can show it. Self-employed buyers usually bring a Notice of Assessment and several months of bank statements. If you just started a job, a letter from your employer that shows your pay can help. Tell us your situation and we will say what to bring.
Last reviewed October 2026 by the Shift Happens finance team
What Our Customers Say
“I honestly can't thank Luke enough. From start to finish he was patient, respectful, transparent, and genuinely cared about helping me find the right vehicle instead of just making a sale.”
“Luke was awesome to deal with and made the car buying experience enjoyable again for me and my wife after a few very unpleasant interactions in the past. I would highly recommend.”
“A huge thank you to Wes and Luke for making my vehicle purchase such a great experience. This has been the best experience I've had at a dealership. They were patient, kind, and attentive.”
Other Financing Options
See what you pre-qualify for
Apply online in about three minutes. We review every application and call you back.
★★★★★ 118+ Google Reviews · AMVIC Licensed · Free Delivery 300km