
Refinance, Trade In, or Ride It Out?
Should I refinance my car loan, trade it in, or keep paying?
If your car is worth more than you owe and your credit has improved, refinancing or trading up can lower your rate. If you owe a little more than it is worth, refinancing may still help. If you owe a lot more, a few more months of payments is often cheaper. The tool below shows which side you are on.
Who this page is for
- You have 12 or more on-time payments on your car loan.
- You are working: a T4 job, self-employed or a steady contract.
- Your rate is high because of your credit when you bought, not your income.
This page is about the decision, not the paperwork. The mechanics of refinancing are in our car loan refinancing guide. Leased instead of financed? A lease ends differently; see what to do when a car lease ends.
Key Facts
- Who this is for
- Working Albertans 12+ months into a car loan
- What you enter
- Payout, car value, rate, months left, payment
- What you get
- Equity, an estimated new payment, months to break even
- Rates
- 4.99%–29.9% APR across all credit tiers
- Your result
- An estimate, not an offer
What do my numbers say?
Fill in the boxes with your own numbers. They open on an example, so you see a full result straight away. Your lender's payout figure and a real trade-in quote give the best estimate.
Example result — change the numbers to yours
Trading up could work
Your car is worth about $2,500 more than you owe, and you have 12 or more on-time payments. That value can go toward your next vehicle.
- Car value minus what you owe
- +$2,500
- Estimated payment if refinanced
- ~$285 bi-weekly
At 16.9% over your 48 months left. Your payment today: $327 bi-weekly. That could be about $42 less on each payment.
We review every application and call you back.
The refinance rate is an illustration: the Subprime example rate from our rate tables, one tier better than your loan sits in today (Deep Subprime), because your credit has improved and you have 12 or more on-time payments. Months to break even assumes the car loses about 15% of its value a year. That is our assumption, not a market figure.
Estimates only — not an offer. Your actual rate depends on your full application.
This tool assumes you have a current car loan and a steady income. If you're not working right now, the honest answer is usually to keep making payments — talk to us first at (825) 736-4438.
See what you pre-qualify for
A few quick answers. No commitment.
What do the three answers mean?
The tool sorts your numbers into one of three answers. The cut-offs are the tool's own, a rule of thumb we may adjust as we learn from real files. They are not a lender rule.
Trading up could work
Your car is worth at least $2,000 more than you owe, and you have 12 or more on-time payments. The extra value, your equity, can go toward your next vehicle. Start with a trade-in appraisal, then a full application.
Refinancing may lower your payment
You owe close to what the car is worth (within $2,000 either way) and a lower rate would save at least $25 on each payment. A new lender prices the loan on your credit today, so this works best when your credit has moved up since you signed. How long to wait is in our guide to refinancing a bad credit car loan.
Riding it out is likely cheaper for now
You owe $2,000 or more over what the car is worth, you have fewer than 12 on-time payments, or a refinance would save under $25 a payment. Keep paying, and the tool shows how many months until you owe less than the car is worth. The section on owing more than your car is worth, further down, covers your options.
Every result is an estimate. Your actual rate depends on your full application, and every lender decides each file.
What does a real example look like?
Take a buyer who earns $5,200 a month, owes $21,500 on a 2021 SUV worth about $24,000, and has 48 months left at 24.9% (the Deep Subprime example rate on our rate tables). They have made 24 or more on-time payments and their credit has improved since they signed. This is what the tool opens on.
Worked example
- Car value minus what you owe
- +$2,500
- Payment today
- ~$327 bi-weekly
- If refinanced at 16.9% (Subprime example rate)
- ~$285 bi-weekly
- Difference
- About $42 less on each payment
Result: Trading up could work
Refinanced, the payment is about 12% of $5,200 gross monthly pay. A common rule of thumb is to keep a car payment under 15% of gross pay.
Example, not an offer. Estimates only — not an offer. Your actual rate depends on your full application. Rates run from 4.99% APR (prime) to 29.9% APR (deep subprime).
In the tool, use your own regular payment from your contract or statement, and your own rate and months left.
How do I get my exact payout amount?
Your payout is not the balance on your last statement. It is what your lender needs to be paid to close the loan on a given day. Call your lender, or sign in to your account, and ask for a payout letter or quote.
Ask for the figure on the exact day the money will reach them. One Canadian lender's payment FAQ puts it this way: “you want to be quoted the payout on the exact date we will receive the funds as there could be a daily per-diem charge until the account is paid in full.”
Put that number in the tool, not the statement balance. A dealer will ask for it too. If you trade in, Alberta rules say the bill of sale must list the balance of any outstanding loan that is included in the cost of the vehicle, so the payout figure ends up in your paperwork. If you do decide to trade, our guide to the payout, the lien and your equity walks through each step.
How do I check for a lien before I trade?
A lien is a lender's registered claim on a car. In Alberta you can search the Personal Property Registry by serial number, which for a car is the VIN, at any registry agent office.
The Government of Alberta describes the search as a way to “check if any liens are registered against the property.” It is written for people buying a used car, and the search is by serial number, so you can run it on your own VIN too.
Bring the VIN. It is usually on the dashboard by the windshield, inside the driver's door frame and on your registration. Fees vary by agent: in October 2026, one Alberta registry agent listed a lien search at $10.00 and another at $15.00 plus disbursements.
Your own lender's lien is expected, and the payout above is what clears it. If a lien shows up that you did not expect, sort it out with that lender before you trade.
Why can a trade-in lower the GST I pay?
When a dealer takes your car in trade, GST is charged on the price after the trade-in comes off. The Canada Revenue Agency says that for used goods a dealer accepts in trade from a person who does not have to charge the GST (usually a person who is not registered for the GST/HST), the dealer charges the GST “on the net amount (the price of the goods you sell or lease minus the amount you allow for the trade-in).” The rule is in section 153(4) of the Excise Tax Act.
The CRA's own example is a $25,000 car with a $10,000 trade-in. GST is charged on $15,000, which is $750 at 5%, instead of $1,250 on the full price. That is $500 less.
The tool does not include GST. When you price your next car, count it: the trade-in allowance on your bill of sale is what comes off before GST is added.
What if I owe more than my car is worth?
That gap is called negative equity. You have three ways through it: pay the gap in cash, keep paying until you owe less than the car is worth (the tool shows how many months that could take), or in some cases roll it into your next loan. Rolling it in makes the new loan bigger, and you start that loan already owing more than the car is worth.
Alberta's rules cover how it has to be shown. The Government of Alberta lists “balance of any outstanding loan that is included into the cost of the vehicle” as mandatory content on a dealer's bill of sale. AMVIC, which licenses Alberta dealers, says: “Inflating the vehicle price, adding fees or other products to account for negative equity is an unfair practice.” If you roll it in, you should be able to point to it on your bill of sale.
For the options and the real cost, read what happens to what you still owe when you trade in and our negative equity car financing guide.
Sources (checked October 2026): Excise Tax Act, s. 153(4), CRA: GST/HST in special cases, Government of Alberta: comprehensive bill of sale, AMVIC: document accuracy, Government of Alberta: personal property liens, find a registration, Accu-Search Registries: lien search, CNN Corporate Services: personal property fees, Santander Consumer Canada: payment FAQs, FCAC: credit report and score basics. Fees and wording are as each source showed them on the day we checked. The break-even month assumes a car loses about 15% of its value a year, which is our assumption, not a market figure.
Example payments are estimates. Not an offer.
Vehicles in stock right now
Browse all inventory →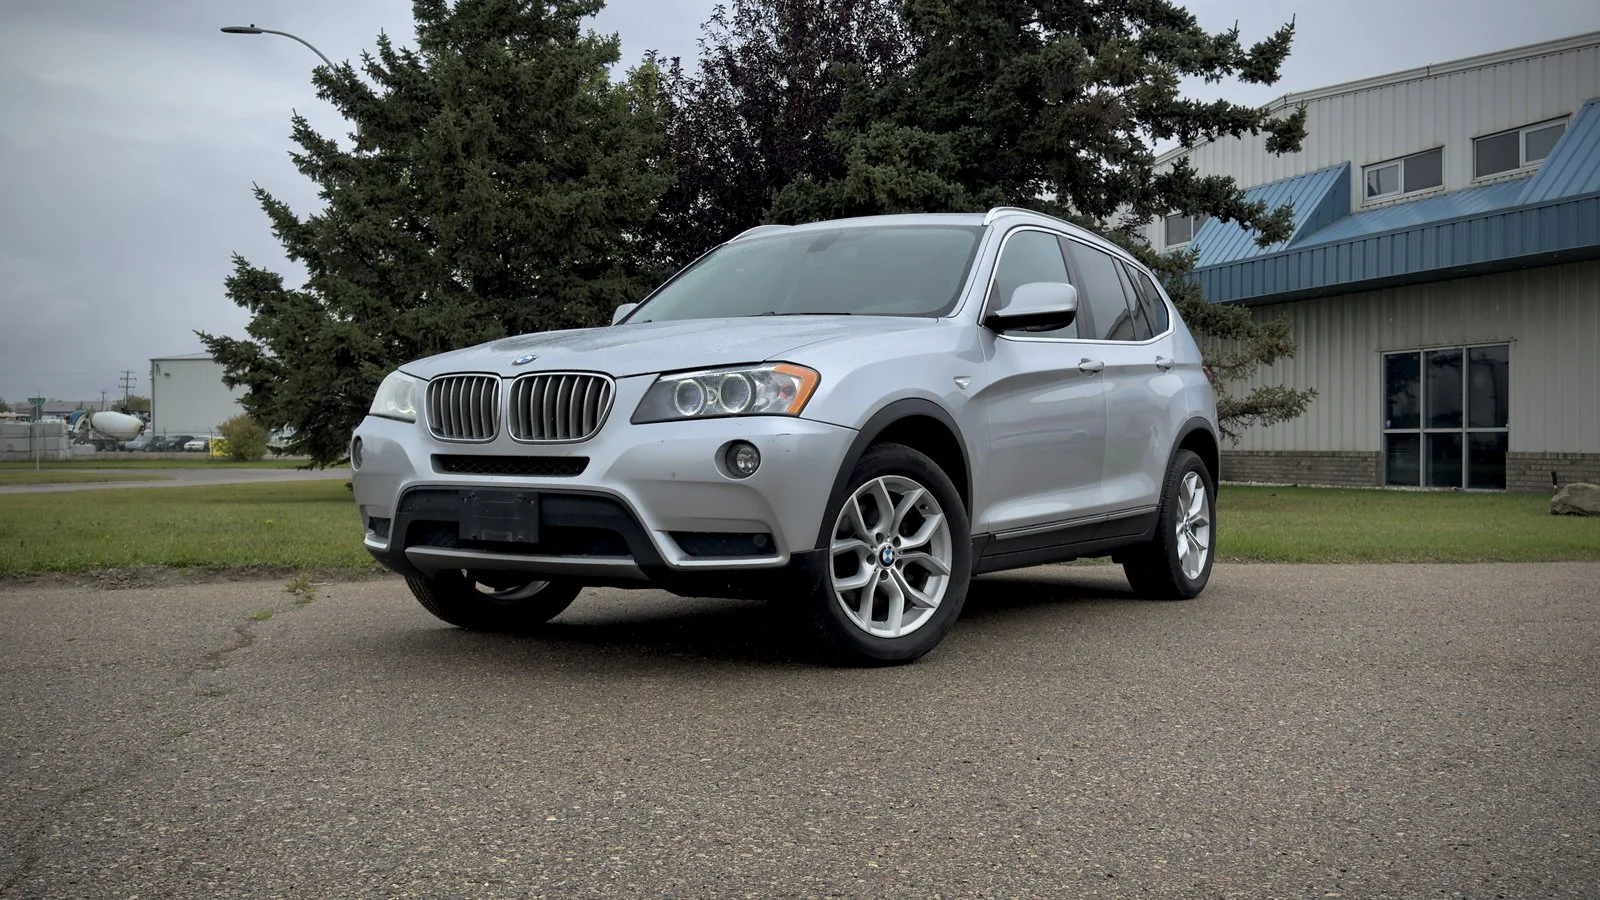
2014 BMW X3 xDrive28i
$75 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $2,698
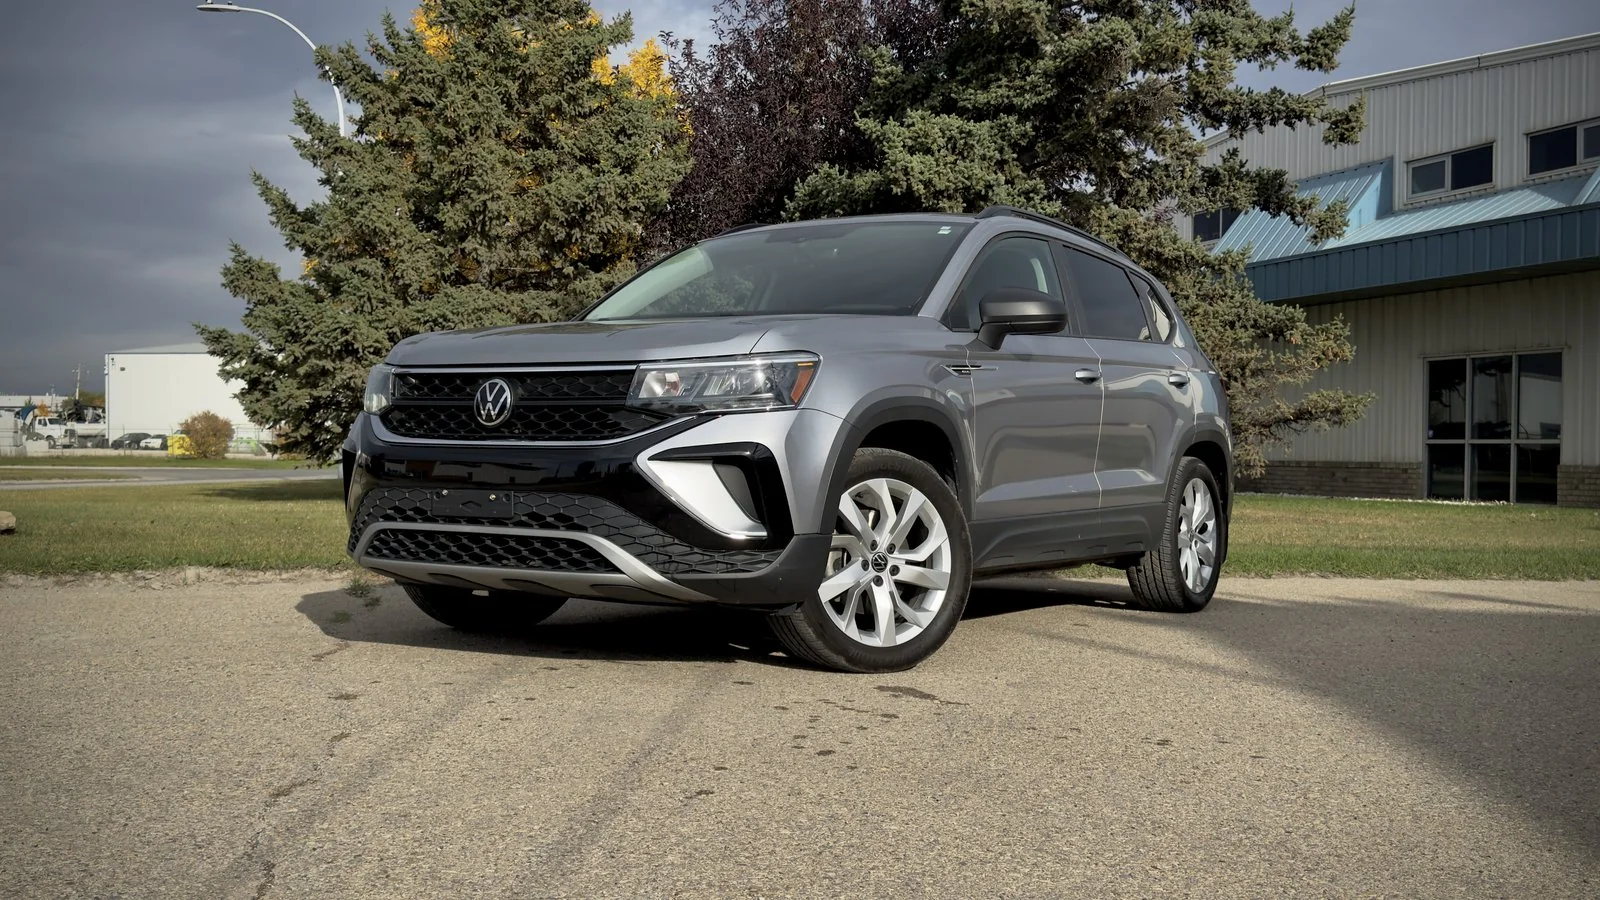
2023 Volkswagen Taos Trendline
$171 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $6,136
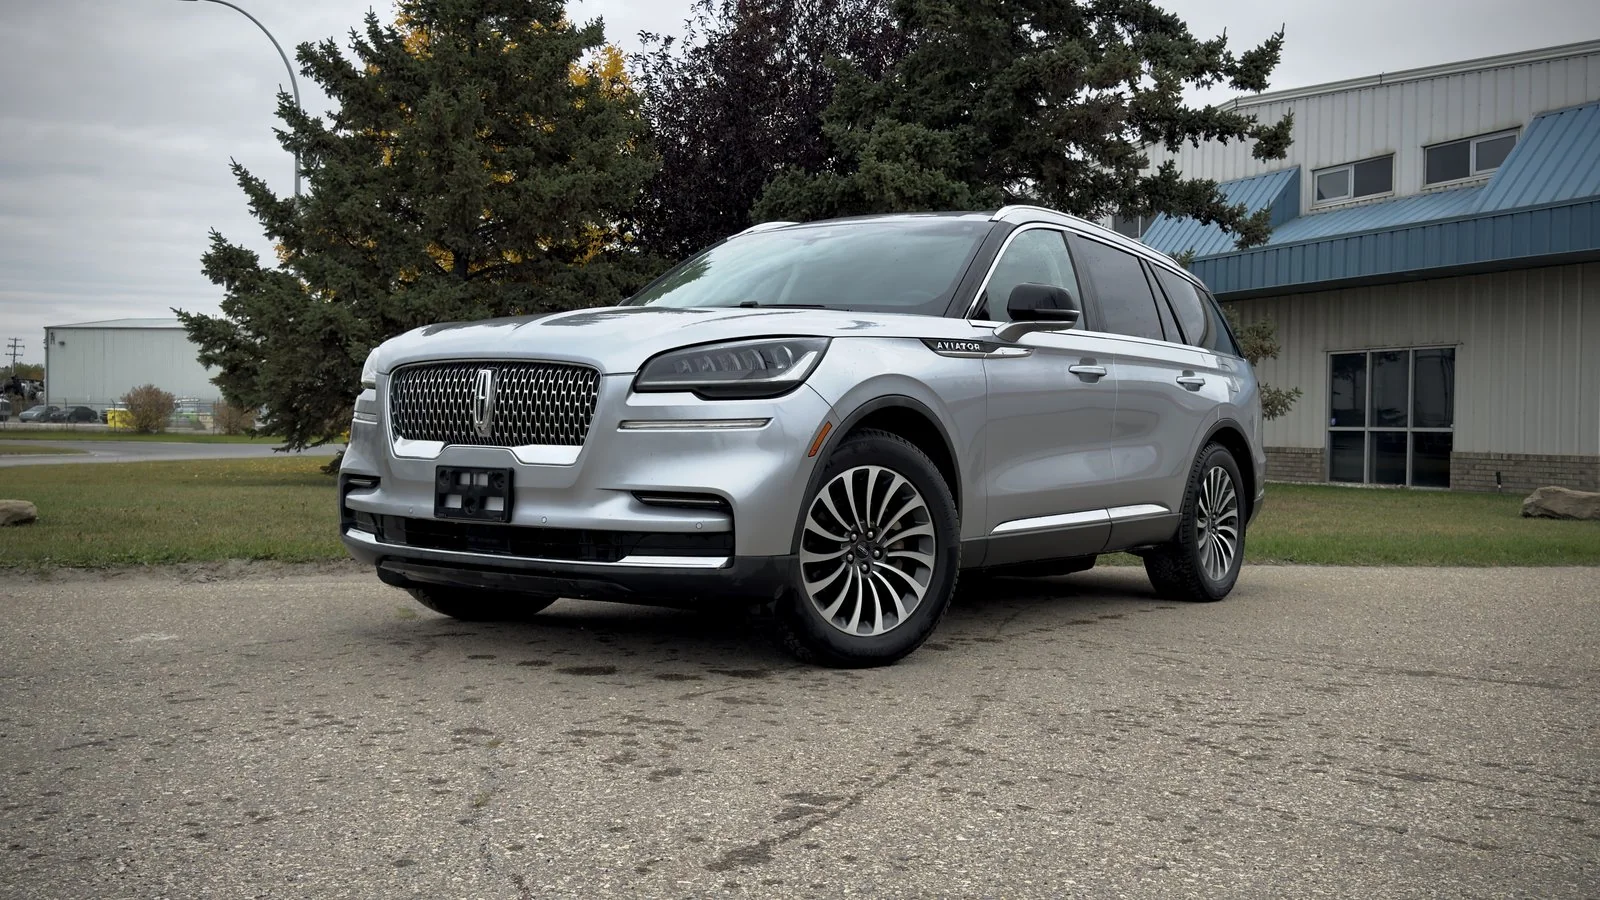
2022 Lincoln Aviator Reserve
$267 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $9,571
OAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Refinance or trade in: common questions
Can I refinance a car loan with bad credit in Alberta?
Often, yes, once you have a record of on-time payments and your credit has improved since you signed. A new lender prices the loan on your credit today, so a refinance helps most when your score has moved up a tier. Every lender decides each file, and we cannot promise a result. Our refinancing guide explains the steps.
How long should I wait before refinancing?
This tool looks for at least 12 on-time payments before it points you to a new loan, and 24 or more is a stronger record. A track record gives a new lender something to price your loan on. Waiting also lowers the balance, which matters if you owe more than the car is worth. Run your numbers, then talk to us.
Does trading in a car I still owe on hurt my credit?
Your credit report records your loans, your payments and each time a lender checks your credit. The Financial Consumer Agency of Canada says a score goes up when you pay bills on time and down when you miss payments or carry too much debt. Trading in means paying out one loan and starting another, so how you pay the new one is what your report shows from then on. We cannot say what it will do to your score.
What if my car is worth less than I owe?
That gap is called negative equity. You can pay it in cash, keep paying until you owe less than the car is worth, or in some cases roll it into the next loan, which makes that loan bigger. In Alberta, a dealer's bill of sale must list the balance of any outstanding loan included in the cost of the vehicle. Our negative equity guide covers each option.
Will a refinance lower my payment or just stretch the term?
It depends on the rate and the number of months. A lower rate over the same months lowers the payment and the interest you pay. Stretching to more months can lower the payment while costing more interest overall. This tool keeps your months left the same, so any saving it shows comes from the rate alone.
Last reviewed October 2026 by the Shift Happens finance team
What Our Customers Say
“Amazing service. Wes was very helpful. Got me a great deal and made everything happen very quickly and stress free. Love my vehicle and much lower payments. Highly recommend!”
“Luke and Wes are a fantastic team! I purchased a Lincoln Corsair in pristine condition. They got me the best interest rate for my financing and even helped me find the best insurer.”
“These guys made sure everything was exactly what I wanted. Shahdeen and Luke offered me a great trade in price and I got to ride away on my dream bike. I would highly recommend.”
Other Financing Options
See what you pre-qualify for
Apply online in about three minutes. We review every application and call you back.
★★★★★ 118+ Google Reviews · AMVIC Licensed · Free Delivery 300km