
Trading In a Car You Still Owe On
Can I trade in a car I still owe money on in Alberta?
Yes. Your lender gives you a payout figure for a set day, the dealer pays it, and the lien comes off. If the car is worth more than the payout, the extra goes toward your next car. If it is worth less, the gap is paid in cash or, if a lender allows it, added to the new loan.
Who this page is for
- You have a loan on the car you want to trade in.
- You are working: a T4 job, self-employed or a steady contract.
- You want to know what you owe, what the car is worth and what happens to the difference.
Want a number for your car first? Start with our trade-in value form. This page covers the loan side of a trade: the payout, the lien and your equity. A leased car is a different case: you do not own it until you buy it out. See what to do when your lease ends.
Key Facts
- Who this is for
- Working Albertans with a loan on the car they trade in
- What you need first
- A payout quote dated for the day your lender is paid
- Equity
- What the car is worth to the dealer, minus your payout
- If you owe more than it is worth
- Paid in cash or, where a lender allows it, added to the new loan
- GST
- Charged on the price after your trade-in value comes off
How much equity do I have?
The boxes open on an example, so you see a full result right away. Swap in your own numbers: a real trade-in quote and your lender's payout figure give the closest estimate. Add the price of the car you want to see what you would finance. For a payment on your own terms, use the payment calculator.
Example result — change the numbers to yours
Worth more than you owe
Equity: +$3,500
Your car is worth about $3,500 more than you owe. After your lender is paid, that $3,500 comes off the price of your next car, like a down payment.
- Price of the car you want
- $28,000
- Minus your equity
- -$3,500
- Plus GST (5% of $12,000, the price after your trade-in value comes off)
- +$600
- Amount you would finance
- $25,100
That is about $257 bi-weekly at the Subprime example rate (16.9%) over 72 months. It leaves out registration, other fees and any down payment.
We review every application and call you back. Every lender decides each file.
Estimates only — not an offer. Your actual rate depends on your full application.
This page assumes you have a car loan and a steady income. In our experience, lenders typically look for about $2,800 a month in income you can prove, from all sources combined. If you are under that, or not working right now, talk to us first at (825) 736-4438.
See what you pre-qualify for
A few quick answers. No commitment.
How does a trade-in with a loan work?
- Get your payout quote. It is the amount that closes your loan on a set day, so ask for the day the money will reach your lender.
- Get a trade-in value. The value a dealer allows is the number that goes on your bill of sale, so a real quote beats a guess.
- Subtract. Trade-in value minus payout is your equity: money toward your next car, nothing, or a gap.
- The dealer pays your lender. When the loan is paid in full the lien comes off, and your equity or your gap carries into the next purchase.
How do I get my payout quote?
Your payout is the amount your lender needs to close your loan on one particular day. It is not simply the balance on your last statement. Interest is added every day until the lender is paid in full, so the later the money arrives, the higher the figure.
Call your lender, or sign in to your account, and ask for a payout quote. Ask for it dated for the day the dealer's payment will reach them. One Canadian lender's payment FAQ tells customers the same thing: have the payout quoted for the exact date the funds will arrive, because a daily per-diem charge can apply until the account is paid in full.
Bring these when you trade:
- Your payout quote, with its date on it.
- Your registration. It shows your VIN, the number a lien search is run on.
- Government photo ID. Alberta's bill of sale records the buyer's ID number.
- Your lender's name and your account number, if you do not have a quote yet.
What happens to the lien when I trade in?
A lien is a lender's claim for repayment, registered against your car. It stays registered until the loan is paid in full. That is why a trade-in with a loan includes a payout: your lender has to be paid before the lien can come off.
When the debt is paid, the registration is discharged, which means it is removed from the Alberta registry. Alberta's rules push dealers to pay off liens quickly: AMVIC, which licenses Alberta dealers, tells consumers that licensed businesses must pay out all liens on a vehicle within seven days after it is sold to a consumer. On a trade, ask the dealer when your lender will be paid, and check with your lender afterward that your loan shows as closed.
You can also check for a lien yourself. A registry agent can search the Alberta Personal Property Registry by serial number, which for a car is the VIN, at any registry agent office in Alberta. A fee applies: one Alberta agent listed $10.00 for a lien search in October 2026. A lien from your own lender is expected, and your payout is what clears it. If you did not expect a lien, sort it out with that lender before you trade.
Read your bill of sale before you sign. Alberta's comprehensive bill of sale must list the value of your trade-in and the balance of any outstanding loan that is included in the cost of the vehicle.
What happens to my equity: more than I owe, even, or less?
Equity is what your car is worth to the dealer minus your payout. Here is one payout, $12,500, and one next car, $28,000, with three different trade-in values.
Worth more than you owe
Trade-in value $16,000. Payout $12,500.
Equity: +$3,500
You would finance $25,100 on a $28,000 car.
$28,000 - $3,500 equity + $600 GST
About $257 bi-weekly at the Subprime example rate over 72 months.
After your lender is paid, the $3,500 left comes off the next car, like a down payment.
About even
Trade-in value $12,500. Payout $12,500.
Equity: $0
You would finance $28,775 on a $28,000 car.
$28,000 + $775 GST
About $294 bi-weekly at the Subprime example rate over 72 months.
The trade-in value pays your lender in full. Nothing is left over and nothing is added to the new loan.
Worth less than you owe
Trade-in value $9,500. Payout $12,500.
Equity: -$3,000
You would finance $31,925 on a $28,000 car.
$28,000 + $3,000 gap + $925 GST
About $326 bi-weekly at the Subprime example rate over 72 months.
The $3,000 gap is paid in cash or, if a lender allows it, added to the loan on your next car, and the balance of your old loan has to be listed on your bill of sale. AMVIC says to ask for any negative equity to be outlined in all your financing and purchasing documents, and our guide to what happens to what you still owe covers your options.
Each total is before registration, other fees and any down payment. The payments use the Subprime example rate over 72 months. Estimates only — not an offer. Your actual rate depends on your full application.
Does a trade-in lower the GST I pay?
For most people, yes. When a dealer takes your car in trade and you are not a GST registrant, which is usually the case for a car you use yourself, the dealer charges GST on the price after your trade-in value comes off, not on the full price. The rule is in section 153(4) of the Excise Tax Act, and the Canada Revenue Agency shows it with an example on its page about GST/HST in special cases.
In the first example above, GST at 5% is worked out on $12,000, not $28,000: $600 instead of $1,400, so $800 less. The calculator does this for you. A higher trade-in value on your bill of sale means less GST, and a lower one means more.
What else should I look at before I trade?
Not sure you should trade at all? Refinance, trade in or ride it out compares your options using your own numbers. Want a better trade-in value? See how to preserve your trade-in value. Rather sell the car outright? See selling your car to us. If you owe more than the car is worth, the negative equity car financing guide covers what rolling it into your next loan costs.
Example payments are estimates. Not an offer.
Vehicles in stock right now
Browse all inventory →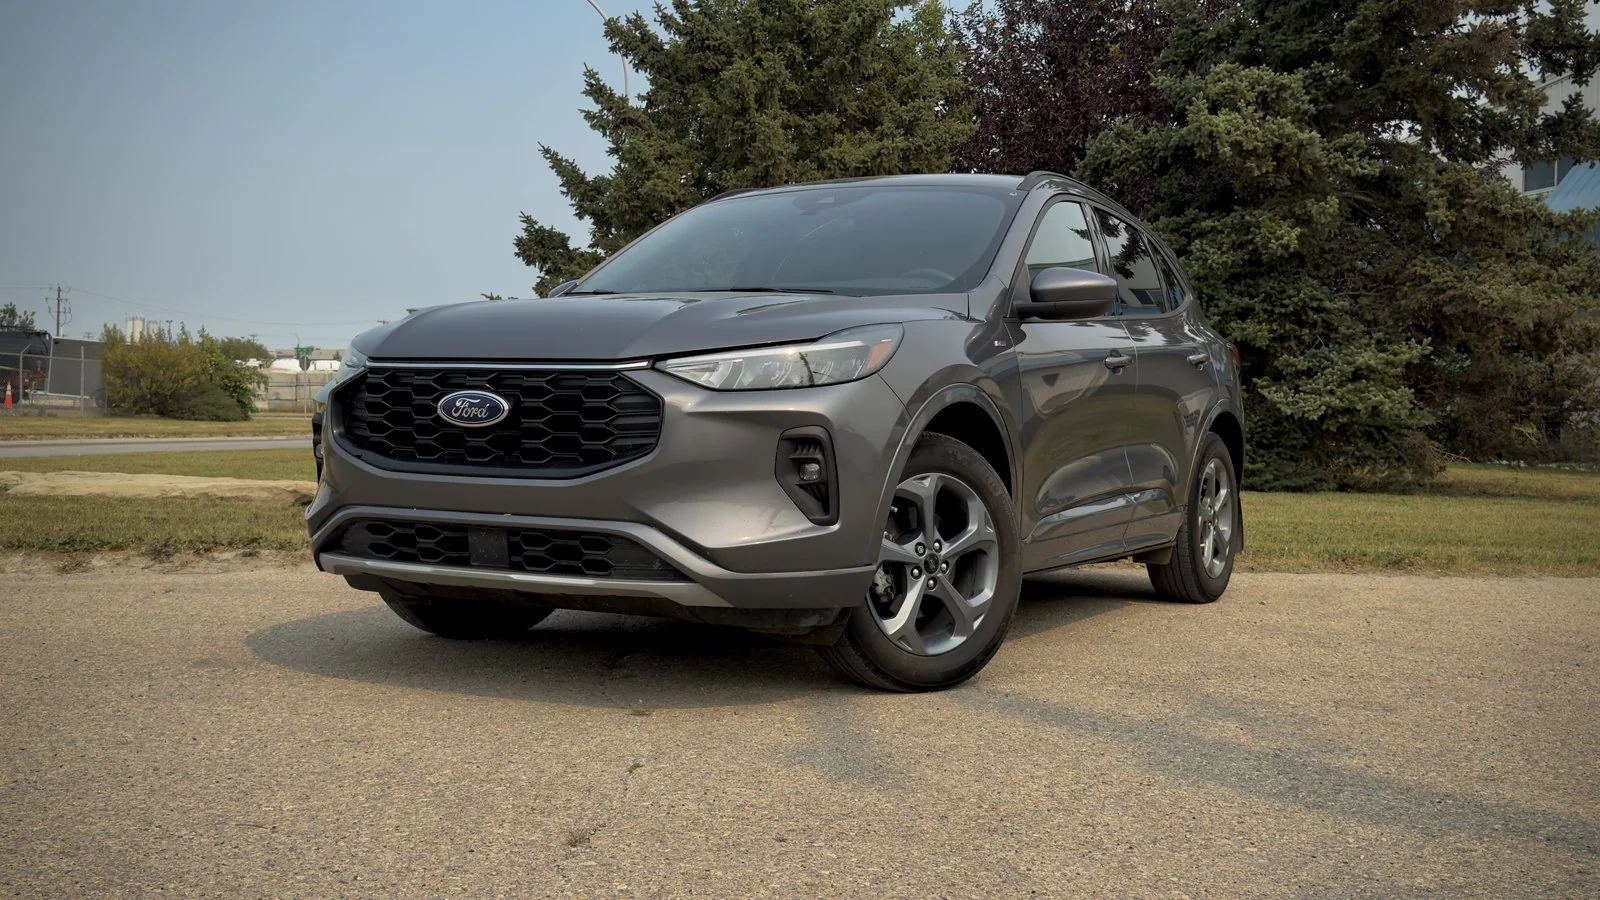
2024 Ford Escape Hybrid ST-Line
$178 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $6,381
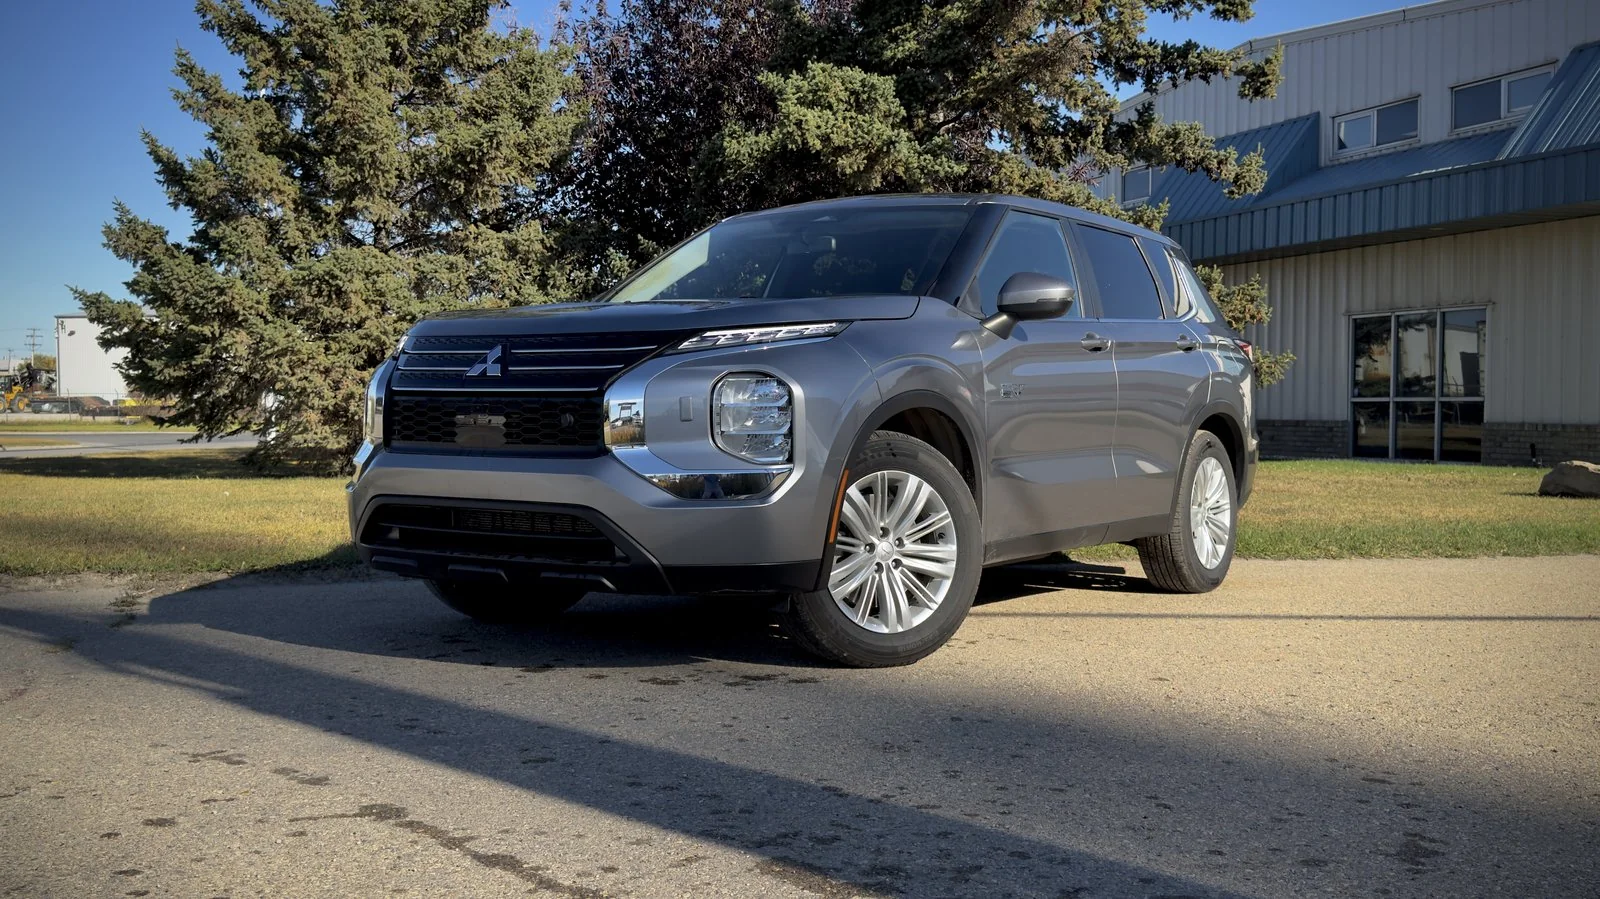
2023 Mitsubishi Outlander ES PHEV
$192 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $6,872
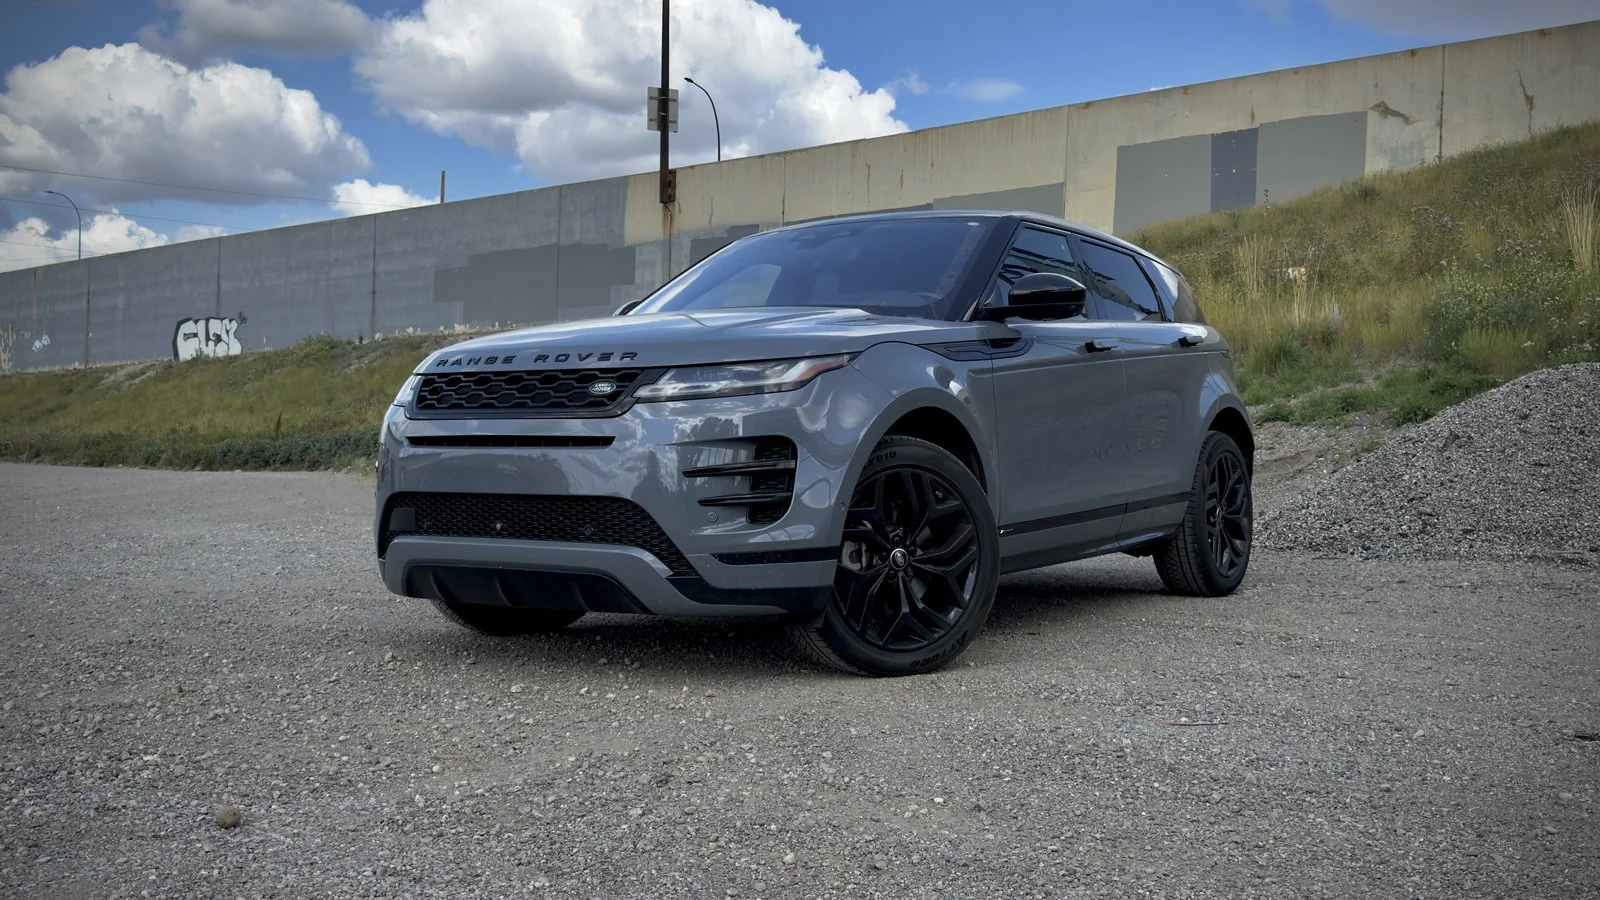
2021 Land Rover Range Rover Evoque R-Dynamic HSE
$212 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $7,609
OAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Trading in a financed car: common questions
Can you trade in a car you still owe money on?
Yes. A dealer can take your car in trade while a loan is still on it. Your lender gives a payout figure, the dealer pays it, and the lien comes off once the loan is paid in full. If the car is worth more than you owe, the extra goes toward your next car. If it is worth less, the gap is paid in cash or, if a lender allows it, added to the new loan.
Can I trade in my car if I owe $20,000 on it?
Yes, owing money does not stop a trade-in by itself. What matters is how your payout compares with what the car is worth. Take the payout away from the trade-in value: if the car is worth more, you have equity, and if it is worth less, you have a gap. Every lender decides each file, so put your own numbers in the calculator above and talk to us.
What is a payout quote, and how do I get one?
A payout quote is the amount your lender needs to close your loan on a set day. It is not just the balance on your last statement, because interest is added every day until the lender is paid. Call your lender or sign in to your account, and ask for the quote dated for the day the dealer's payment will reach them.
How do I check whether my car has a lien?
Ask a registry agent to search the Alberta Personal Property Registry by VIN. Your VIN is on your registration, and a fee applies. If you have a car loan, a lien from your lender is expected, and your payout is what clears it. If a lien shows up that you did not expect, sort it out with that lender before you trade.
Who pays off my loan when I trade in my car?
The payout is built into the trade deal. It is paid to your lender, and the balance of the old loan that is included in the cost of the vehicle has to be listed on the bill of sale. AMVIC tells consumers that licensed dealers must pay out all liens on a vehicle within seven days after it is sold to a consumer. Ask when your lender will be paid.
Does a trade-in lower the GST on my next car?
For most people, yes. When a dealer takes your car in trade and you are not a GST registrant, GST is charged on the price after your trade-in value comes off, not on the full price. The Canada Revenue Agency explains the rule on its page about GST/HST in special cases. The trade-in value and the GST both show on your bill of sale.
What should I bring to trade in a car with a loan?
Bring your payout quote with its date on it, your registration, which shows your VIN, and government photo ID. If you do not have a quote yet, bring your lender's name and your account number. The payout quote matters most, because your equity and the amount you finance both depend on it.
Sources (pages opened October 5, 2026): Santander Consumer Canada: payment FAQs; Financial Consumer Agency of Canada: risks associated with car liens; Government of Alberta: personal property liens, find a registration; Government of Alberta: personal property liens, change an interest; Accu-Search Registries: lien search; AMVIC: buying used (liens); Government of Alberta: comprehensive bill of sale; AMVIC: negative equity on vehicles; Canada Revenue Agency: GST/HST in special cases. Wording and fees are as each page showed them that day. Every lender sets its own payout rules, so check yours with your lender.
Last reviewed October 2026 by the Shift Happens finance team
What Our Customers Say
“These guys made sure everything was exactly what I wanted. Shahdeen and Luke offered me a great trade in price and I got to ride away on my dream bike. I would highly recommend.”
“Simply amazing! Finding an affordable car these days is almost impossible, but Shahdeen and Luke made the entire process so smooth and stress-free. Knowledgeable, honest, and no pressure.”
“I honestly can't thank Luke enough. From start to finish he was patient, respectful, transparent, and genuinely cared about helping me find the right vehicle instead of just making a sale.”
Other Financing Options
See what you pre-qualify for
Apply online in about three minutes. We review every application and call you back.
★★★★★ 118+ Google Reviews · AMVIC Licensed · Free Delivery 300km