
What Income Do You Need for a 3-Row SUV or Minivan Loan in Alberta?
What income do I need for a 3-row SUV or minivan loan in Alberta?
On a payment near 15% of gross monthly pay, a $30,000 family SUV or minivan loan needs about $4,300 a month in pay at a 550–599 score, and a $45,000 loan about $6,400. A stronger score needs less, a lower score more. Example, not an offer. Every lender decides each file.
This ladder is part of our guide to how much car loan you can get by income and credit score. That grid starts from your pay. This ladder starts from the loan: pick a loan size and read the pay it needs.
Who this page is for
- You have steady pay you can show, and you are shopping for a family SUV or minivan.
- Your credit took a hit, and you want to know what the loan needs before you fall for a vehicle.
- You would rather see the numbers than guess.
The smallest pay on this page is $3,500 a month, at the strongest score band. If you earn less, or your pay is not steady yet, talk to us first. A smaller vehicle, a co-applicant, a bigger down payment or a few months of income history can change the picture.
Key Facts
- Who this is for
- Steady pay, a family-size vehicle
- Loans shown
- $30,000 to $45,000, in $5,000 steps
- Payment used
- 15% of gross monthly pay (a rule of thumb)
- Loan used
- 72 months, $0 down
- Rate used
- The middle of each score band's range (4.99%–29.9% APR across all bands)
- Lender network
- 21+ lenders
See what you pre-qualify for
A few quick answers. No commitment.
How much income do I need for a $30,000 to $45,000 SUV or minivan loan?
Find the loan you would finance down the side and your credit score across the top. Each box shows two numbers. The first is the gross monthly pay (your pay before tax) at which a payment near 15% of pay would repay that loan. The second is the monthly payment on that loan.
Slide the table sideways to see every score band.
| Loan to finance | Prime | Near-Prime | Subprime | Deep Subprime | |||
|---|---|---|---|---|---|---|---|
| 750+6.95% APR | 650–7499.9% APR | 600–64911.4% APR | 550–59914.9% APR | 500–54919.9% APR | 450–49924.9% APR | 300–44927.4% APR | |
| $30,000 | ~$3,500/mo~$511 payment | ~$3,700/mo~$554 payment | ~$3,900/mo~$577 payment | ~$4,300/mo~$633 payment | ~$4,800/mo~$717 payment | ~$5,400/mo~$806 payment | ~$5,700/mo~$853 payment |
| $35,000 | ~$4,000/mo~$596 payment | ~$4,400/mo~$647 payment | ~$4,500/mo~$673 payment | ~$5,000/mo~$738 payment | ~$5,600/mo~$836 payment | ~$6,300/mo~$941 payment | ~$6,700/mo~$995 payment |
| $40,000 | ~$4,600/mo~$681 payment | ~$5,000/mo~$739 payment | ~$5,200/mo~$770 payment | ~$5,700/mo~$844 payment | ~$6,400/mo~$956 payment | ~$7,200/mo~$1,075 payment | ~$7,600/mo~$1,137 payment |
| $45,000 | ~$5,200/mo~$766 payment | ~$5,600/mo~$831 payment | ~$5,800/mo~$866 payment | ~$6,400/mo~$949 payment | ~$7,200/mo~$1,075 payment | ~$8,100/mo~$1,209 payment | ~$8,600/mo~$1,279 payment |
Estimates only, not offers. Every box assumes a 72-month loan with $0 down and the rate shown under the score: the middle of that band's range (4.99%–29.9% APR across all bands). The pay is rounded up to the next $100, so a box never understates what the rule of thumb needs. The loan to finance is what you borrow: the price of the vehicle plus GST and any fees you finance, less a down payment or a trade-in. Your own rate depends on your file. Every lender decides each file.
How do I read the ladder?
Start with the loan, not the sticker price. The loan is what you borrow: the price of the vehicle, plus GST and any fees you finance, less a down payment or a trade-in. If your loan sits between two rows, read the bigger one.
Find your credit score. Not sure of it? You can check your credit score for free. If your score sits on the edge of two bands, read both columns.
Read the box. The bold number is the gross monthly pay at which a payment near 15% of pay carries that loan. The grey number is the payment itself. If your pay is at or above the bold number, the rule of thumb carries the loan. If it is below, look one row up for a smaller loan, or call us at (825) 736-4438 and we will go through your options.
What counts as a 3-row SUV or minivan? Any family-size SUV or minivan with a third row of seats. The maths does not care about the badge on the back. It only cares how much you borrow, so use the same ladder for any vehicle in this loan range.
To start from your pay instead, use the grid linked at the top of this page. To try your own price, term and rate, use the payment calculator, and for a budget read how much car you can afford.
How much does my credit score change the pay I need?
Your pay sets the payment you can carry. Your score sets the rate on that loan. A higher rate means more of each payment goes to interest, so the same loan needs a bigger payment, and a bigger payment needs more pay.
Take a $40,000 loan. At a 750+ score it needs about $4,600 a month in pay. At 550–599 it needs about $5,700. At 300–449 it needs about $7,600. Same loan, same 72 months. The gap is the price of the rate, not a verdict on you.
That gap shrinks as your credit rebuilds, because the rate you are offered can move up a band. The car loan rates by credit score sit behind every column. If your score is around 600, a 600 credit score car loan on a steady income shows that band in full.
What is the monthly payment on a $30,000 SUV or minivan loan?
Over 72 months with $0 down, a $30,000 loan is about $511 a month at a 750+ score, about $633 at 550–599 and about $853 at 300–449. Paid bi-weekly, the 550–599 payment is ~$291/bi-weekly.
Each $5,000 you borrow on top adds roughly $105 a month to the payment at 550–599. Example payments, not offers: your own rate depends on your file.
Does a longer loan or a down payment lower the pay I need?
Yes to both, and each has a cost. A longer loan spreads the same amount over more payments. A down payment makes the loan smaller. Here is the same $40,000 loan at a 600–649 score over four terms.
| Term | Monthly payment | Gross pay needed | Total interest |
|---|---|---|---|
| 60 months | ~$878 | ~$5,900 | ~$12,660 |
| 72 months | ~$770 | ~$5,200 | ~$15,410 |
| 84 months | ~$693 | ~$4,700 | ~$18,240 |
| 96 months | ~$637 | ~$4,300 | ~$21,150 |
Going from 72 to 96 months lowers the pay needed from about $5,200 to about $4,300, and adds about $5,740 in interest. Going the other way, 60 months costs about $2,750 less in interest but needs about $5,900 in pay. The Financial Consumer Agency of Canada makes the same point: the longer the loan term, the lower your payments and the more interest you pay, so it suggests choosing the shortest term you can afford. It also warns that it takes longer to get out of negative equity on a long loan, which means owing more than the vehicle is worth. Every lender sets its own longest term.
A down payment, or a trade-in with value, lowers the loan. On the ladder, every $5,000 off the loan moves you up one row: at 550–599, going from the $40,000 row to the $35,000 row lowers the pay needed from about $5,700 to about $5,000. Read how down payments work or see how a trade-in works when you still owe on your car.
What does one family SUV look like in real money?
Here is one example: a buyer with steady pay and a score in the 600–649 band, looking at a used three-row SUV advertised at $36,000. GST at 5% on a dealer sale adds $1,800, so the loan is $37,800 with $0 down.
Worked example
- Gross pay
- $6,000 a month
- Credit score
- 600–649
- Vehicle
- used 3-row SUV ($36,000 plus GST), $37,800
- Down payment
- $0
- Amount financed
- $37,800 over 72 months
- Example rate
- 11.4% APR (the middle of the 600–649 band)
Payment: ~$335/bi-weekly (or ~$727/mo)
That is about 12% of gross monthly pay. A common rule of thumb is to keep a car payment under 15% of gross pay.
Example, not an offer. Your rate depends on your file; rates run from 4.99% APR (prime) to 29.9% APR (deep subprime).
On the ladder, that loan sits between the $35,000 and $40,000 rows at 600–649, which need about $4,500 and $5,200 a month in pay. This buyer's $6,000 clears both. You do not have to borrow the most the rule of thumb carries: a smaller loan means a smaller payment.
What if I have other debts, a co-applicant or a trade-in?
Other debts. Lenders add up what you already owe each month: credit cards, loans, a consumer proposal payment. The more of your pay is already spoken for, the less room there is for a new payment, so the loan one lender will consider can be smaller than the ladder shows. What car lenders check is covered in what car lenders verify when you work.
A co-applicant. A second person with income can raise the payment a lender will consider. Be clear on what you are asking: a co-applicant is legally responsible for the loan. Read do cosigners help with a bad credit car loan before you decide.
Is this what a lender will approve? No. It is an example of what the rule of thumb carries, not a lender's limit. Every lender decides each file. We cannot promise what any lender will say. What we do is review your application, match it to lenders that fit your situation, and call you back. For how your pay and score combine, see how a steady income helps a bad credit car loan.
Example payments are estimates. Not an offer.
Family SUVs and minivans in stock right now
Browse all inventory →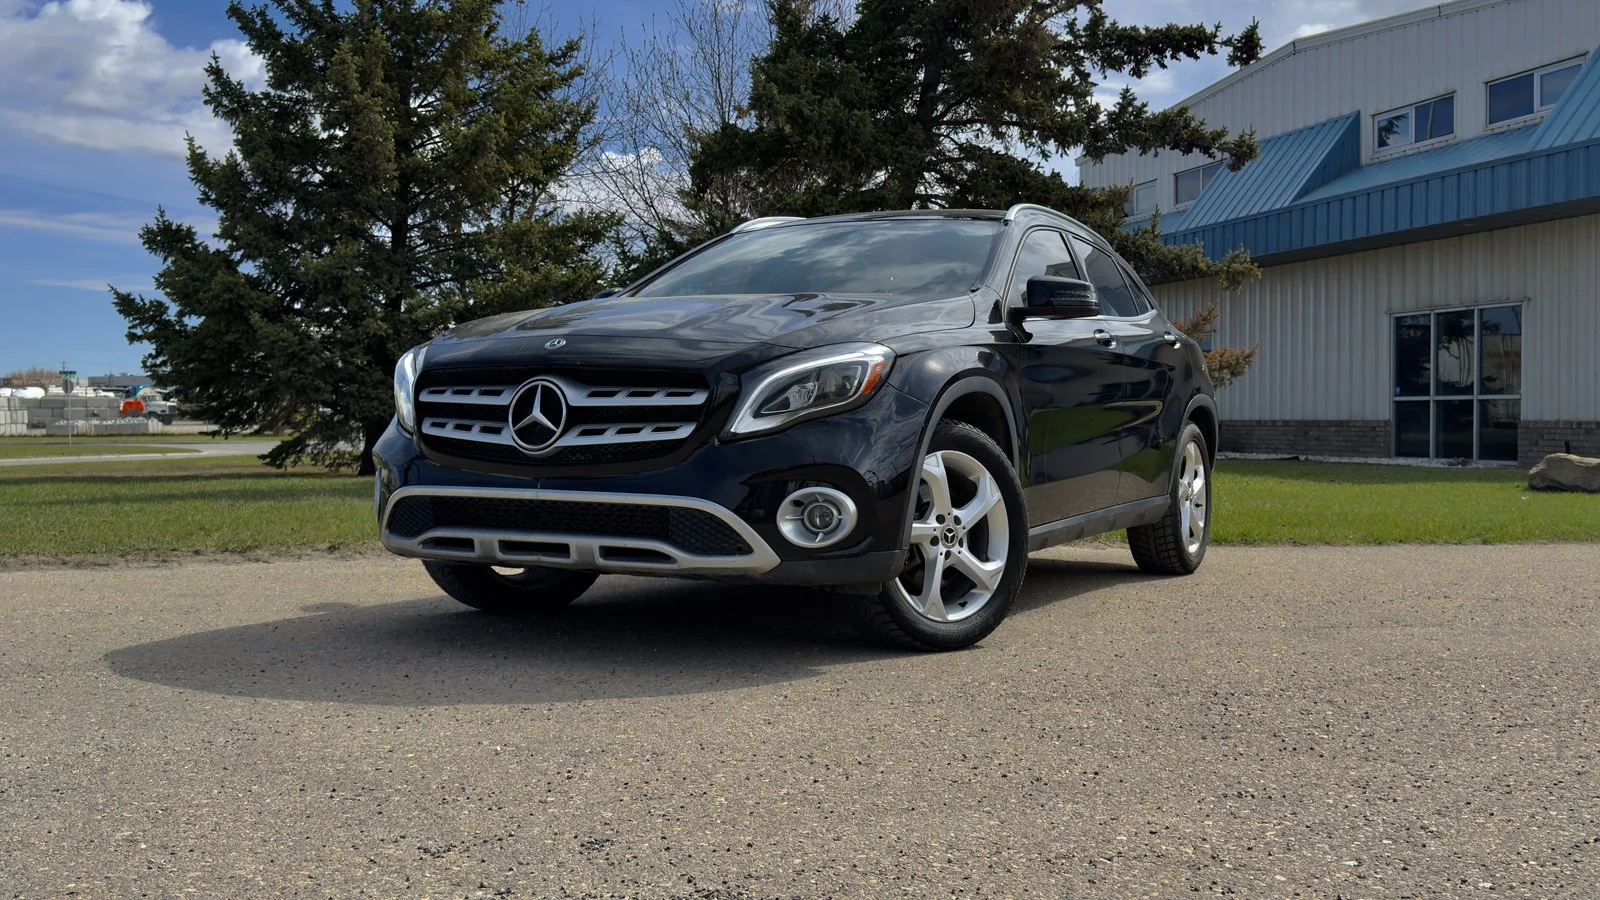
2020 Mercedes-Benz GLA250 4Matic
$150 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $5,398
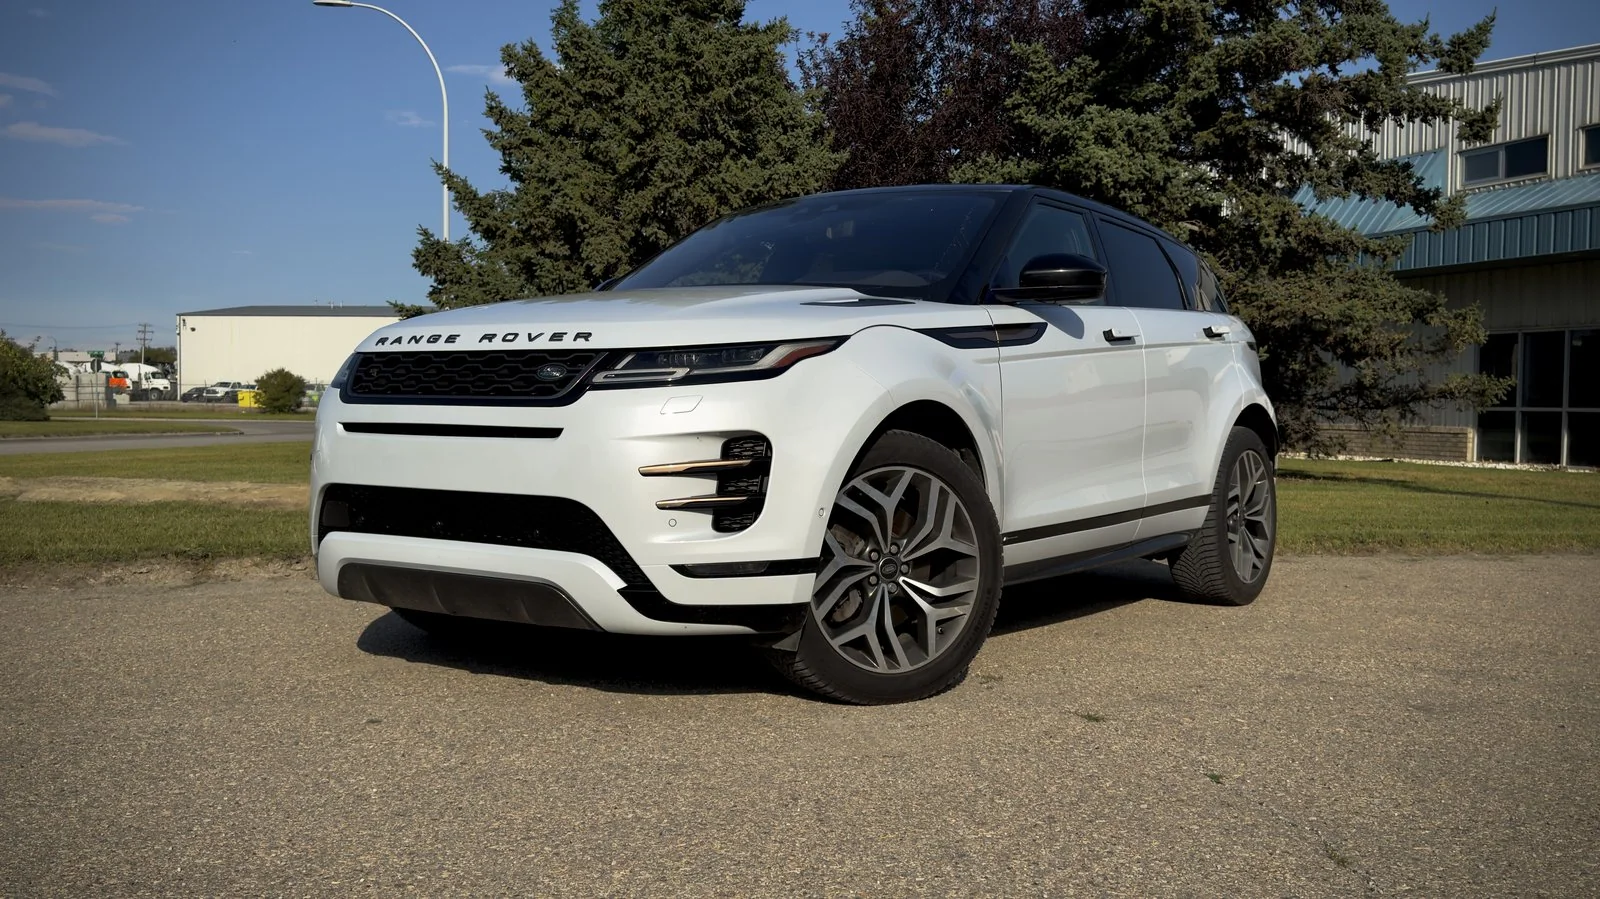
2020 Land Rover Range Rover Evoque P250 First Edition
$178 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $6,381
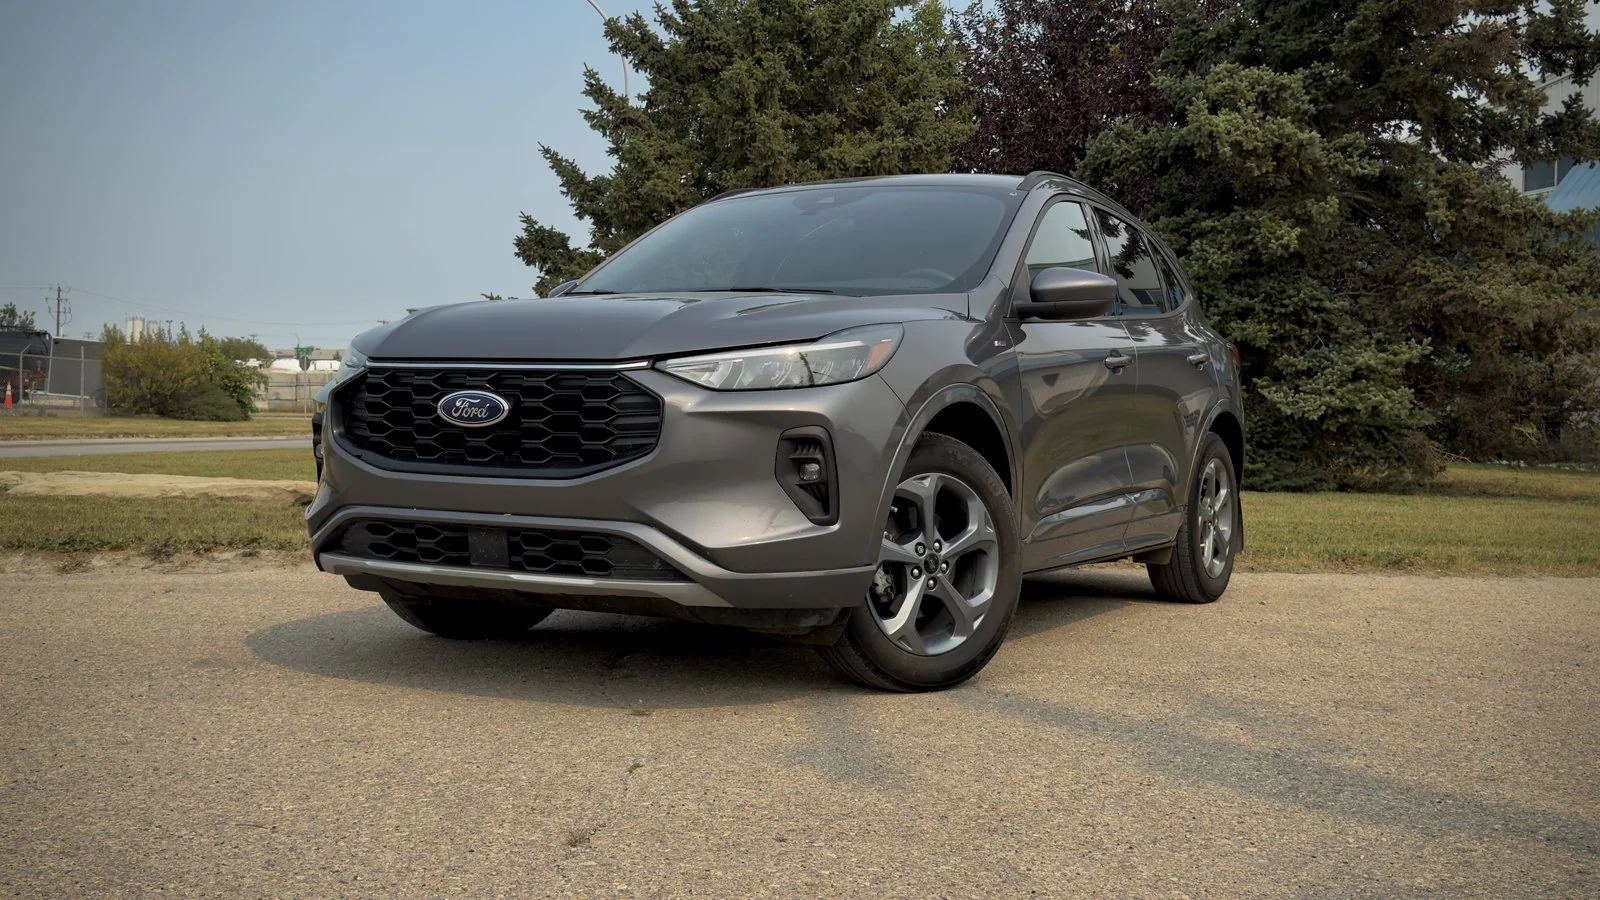
2024 Ford Escape Hybrid ST-Line
$178 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $6,381
OAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Income for an SUV or minivan loan: common questions
How much income do I need for a $40,000 SUV loan?
On a payment near 15% of gross monthly pay, over 72 months with $0 down, a $40,000 loan needs about $5,700 a month in pay at a 550–599 score, about $4,600 at 750+ and about $7,600 at 300–449. It is a guide, not a lender rule. Every lender decides each file.
How much income do I need for a minivan loan?
The same as an SUV loan of the same size. The loan, not the body style, sets the pay a payment needs. A $35,000 minivan loan needs about $5,000 a month in pay at a 550–599 score on this page's rule of thumb. Read the row for your loan and the column for your score.
What is the monthly payment on a $30,000 car loan?
Over 72 months with $0 down, about $511 a month at a 750+ score, about $633 at 550–599 and about $853 at 300–449. Your score sets the rate, and the rate sets the payment. Example, not an offer.
Does a longer loan lower the income I need?
Yes. On a $40,000 loan at a 600–649 score, 96 months needs about $4,300 a month in pay, against about $5,200 over 72. It also adds about $5,740 in interest. The Financial Consumer Agency of Canada suggests choosing the shortest term you can afford.
Does a down payment lower the income I need?
Yes, because it lowers the loan. At a 550–599 score, a $5,000 smaller loan moves you from the $40,000 row (about $5,700 a month in pay) to the $35,000 row (about $5,000). A trade-in with value works the same way.
Can a co-applicant's income count?
It can. A co-applicant with income can raise the payment a lender will consider. A co-applicant is also legally responsible for the loan, so if the payments stop, the lender can go to them. That is a big ask, even for family. Each lender decides each file.
Is 15% of my pay a lender rule?
No. It is a rule of thumb that keeps a payment in a comfortable range. Lenders look at all your monthly debts together, so the loan one lender will consider can be smaller or larger than the ladder shows. Use it to pick a price range, then let the application tell you more.
Sources (pages opened October 5, 2026): Financial Consumer Agency of Canada: financial risks when buying a car; Financial Consumer Agency of Canada: shopping around for auto-financing; Financial Consumer Agency of Canada: how much car can you truly afford?; AMVIC: all-in pricing is the law. The loan sizes, rates, pay and payments above are our own examples, worked out from the maths on this page; they are not from those sources.
Last reviewed October 2026 by the Shift Happens finance team
What Our Customers Say
“Luke was fantastic with helping us get into a mini van, we are MORE than happy. I highly recommend anyone looking for a vehicle to go check out Shift Happens!”
“Simply amazing! Finding an affordable car these days is almost impossible, but Shahdeen and Luke made the entire process so smooth and stress-free. Knowledgeable, honest, and no pressure.”
“Luke was awesome to deal with and made the car buying experience enjoyable again for me and my wife after a few very unpleasant interactions in the past. I would highly recommend.”
Other Financing Options
See what you pre-qualify for
Apply online in about three minutes. We review every application and call you back.
★★★★★ 118+ Google Reviews · AMVIC Licensed · Free Delivery 300km