
Car Loans for Flat-Rate Technicians and Commission Earners in Alberta
How do car lenders read flat-rate or commission pay?
One pay stub can look high or low when your pay moves with the work. Lenders generally ask for a pay stub or a T4, and may ask for more when pay varies. Bring several recent stubs, your year-end stub or T4, and a letter from your employer that explains how you are paid. Every lender decides each file.
This page is part of our guide to what car lenders verify when you work. It covers pay that moves, such as flat-rate and commission pay.
Who this page is for
- You are paid by the job (flat rate) or partly on commission, so your pay moves with the work.
- You are an auto technician, a service advisor or in a similar trade, and your credit took a hit.
- You want to know what to bring so a lender can see your real pay.
Key Facts
- Who this is for
- Flat-rate, commission or other pay that moves
- Lenders generally ask for
- A T4 or a pay stub, and more when pay varies
- What shows the pattern
- Several stubs, a year-end stub or T4, an employer letter
- A lender formula for flat-rate or commission pay
- None published on the pages we read
- Lender network
- 21+ lenders
See what you pre-qualify for
A few quick answers. No commitment.
How does a car lender read pay that changes every pay period?
A lender wants to see what your pay usually is, and that it will keep coming. A pay stub is one pay period. When your pay moves with the work, one stub can look high or low. One bank’s credit-granting page puts the second half this way: “Based on your employment history, it must appear reasonable that your income will continue into the future.”
The same page says: “A T4 slip or a pay stub is generally required as minimum proof of income. Depending on the type of income you earn (for example, if you are self-employed or a contracted employee) and the type of loan you require, more information may be requested.” In other words, a T4 or a pay stub is the usual minimum, and some kinds of income get more questions.
None of the lender or loan-guide pages listed at the foot of this page gives a formula for flat-rate or commission pay. They list documents. How much of your variable pay a lender counts is each lender’s call, and we cannot give you a formula. For overtime, shift premiums and bonuses, see what car lenders verify when you work.
Which papers show pay that moves with the work?
Five papers do most of the work. Each one shows a different piece of the picture.
| Paper | What it shows | Why it helps when pay moves |
|---|---|---|
| Several recent pay stubs | Your pay for each pay period | Shows how far your pay moves from one period to the next. |
| Your year-end pay stub or T4 | Your pay added up in one figure | A T4 counts commissions as part of employment income (see below), so it shows the total, not one pay period. |
| A letter from your employer | How you are paid, and since when | Explains the pay plan, which a stub does not. |
| Bank statements | Your pay landing in your account | Shows the deposits behind the stubs. |
| A Notice of Assessment | Your year as filed with the Canada Revenue Agency | Some lenders accept a tax document as proof of employment. |
The T4 counts commissions. The Canada Revenue Agency says: “Employment income consists of amounts that you receive as salary, wages, commissions (see line 10120), bonuses, tips, gratuities, and honoraria.” “Employment income is usually shown in box 14 of your T4 slip.” On commissions it adds: “Report on line 10120 of your return the total commissions shown in box 42 of all your T4 slips received as an employee. This amount is already included in your income on line 10100 of your return.” So if part of your pay is commission, your T4 can show that part on its own line, in box 42.
Lenders list their own papers. One credit union’s page asks for “Two sources of income verification.” and says: “If you’re a salaried employee, this would be your last two paystubs or a letter from your employer and either your most recent T4, Notice of Assessment (NOA) or the previous year end paystub.” A bank’s car-loan guide lists “Proof of income and employment (Pay Stubs, Employment Verification Letter, Tax Returns, Bank Statements)”. Another bank’s page lists “A recent T4, T4A or T1 tax document with notice of assessment” as one way to show proof of employment.
Missing a stub? Alberta’s Employment Standards page says employers must “provide employees with a statement of earnings for each pay period” and “keep employment records for 3 years”. If you need an older stub, ask your payroll office.
How many pay stubs should I bring?
There is no one number, and every lender sets its own list. One lender asks for two sources of income verification, another for one proof of employment. When your pay moves, bring more than the minimum so a lender can see the pattern without guessing.
- Your last two pay stubs.
- A longer run of recent stubs. One loan guide says: “Be sure that you have records going back at least three months.”
- Your year-end pay stub, or your latest T4.
- A letter from your employer (next section).
- Bank statements that show your pay going in, if a lender asks.
What should my employer’s letter say?
It should explain the pay plan. A loan guide says: “One of the most essential parts of any letter from your employer is your salary information and pay/compensation structure.” For a flat-rate or commission job, ask your payroll office or manager for a letter on company letterhead that gives:
- Your job title and your start date.
- How you are paid: flat rate, hourly, commission, or a mix.
- If there is a base amount or a minimum number of paid hours, what it is.
- Your pay for the last year, or your usual range.
Some lenders contact your employer directly instead of asking for a letter. Give your manager a heads-up so the call goes smoothly.
What if my last few months were slow?
Here is why one stub can mislead. The twelve months below are example pay for a technician whose pay moves with the work.
Worked example
- Jan
- $4,600
- Feb
- $4,100
- Mar
- $5,300
- Apr
- $5,700
- May
- $4,900
- Jun
- $4,300
- Jul
- $3,300
- Aug
- $5,100
- Sep
- $5,600
- Oct
- $4,800
- Nov
- $3,900
- Dec
- $4,400
Gross pay a month. Lowest $3,300, highest $5,700, average $4,667.
Payment: ~$533/mo ($24,000 used SUV, 72 months at 16.9% APR, Subprime example)
| Measured against | Gross pay | The payment is about |
|---|---|---|
| The slowest month | $3,300 a month | 16% of gross pay |
| The 12-month average | $4,667 a month | 11% of gross pay |
| The best month | $5,700 a month | 9% of gross pay |
Example, not an offer. The pay figures are examples. Your rate depends on your file; rates run from 4.99% APR (prime) to 29.9% APR (deep subprime).
The payment does not change, but the picture does: it is about 9% of the best month and 16% of the slowest. A lender may look at one stub, a few months or your T4, and we do not know any lender’s formula. The example only shows why the longer record helps.
A common rule of thumb is a payment near 15% of gross pay. In the slowest month this payment is a little over that line. That is one reason to size the payment against a slower month, not your best one.
How do I pick a payment when my pay moves?
Check it against a slower month, not your best. That is our suggestion, not a lender rule. If the payment still fits a slow month, a busy one is a bonus.
To try your own numbers, use the payment calculator. To see what your pay can carry at each score band, read the loan size your pay can carry. For how pay and credit work together, see good income, bad credit car loans.
What if I just changed shops or pay plans?
A recent change means a shorter pay history. Bring your offer letter, or a letter that describes the new pay plan, with your first stubs. How lenders handle a new job is on our page about starting a new job in Alberta. Other pay that moves is covered on oilfield worker car loans, seasonal worker car financing and gig worker car financing.
The quickest start is the online application. Tell us how you are paid. We review every application and call you back. Or call us at (825) 736-4438. If you run your own shop, see self-employed car financing.
Example payments are estimates. Not an offer.
Vehicles in stock right now
Browse all inventory →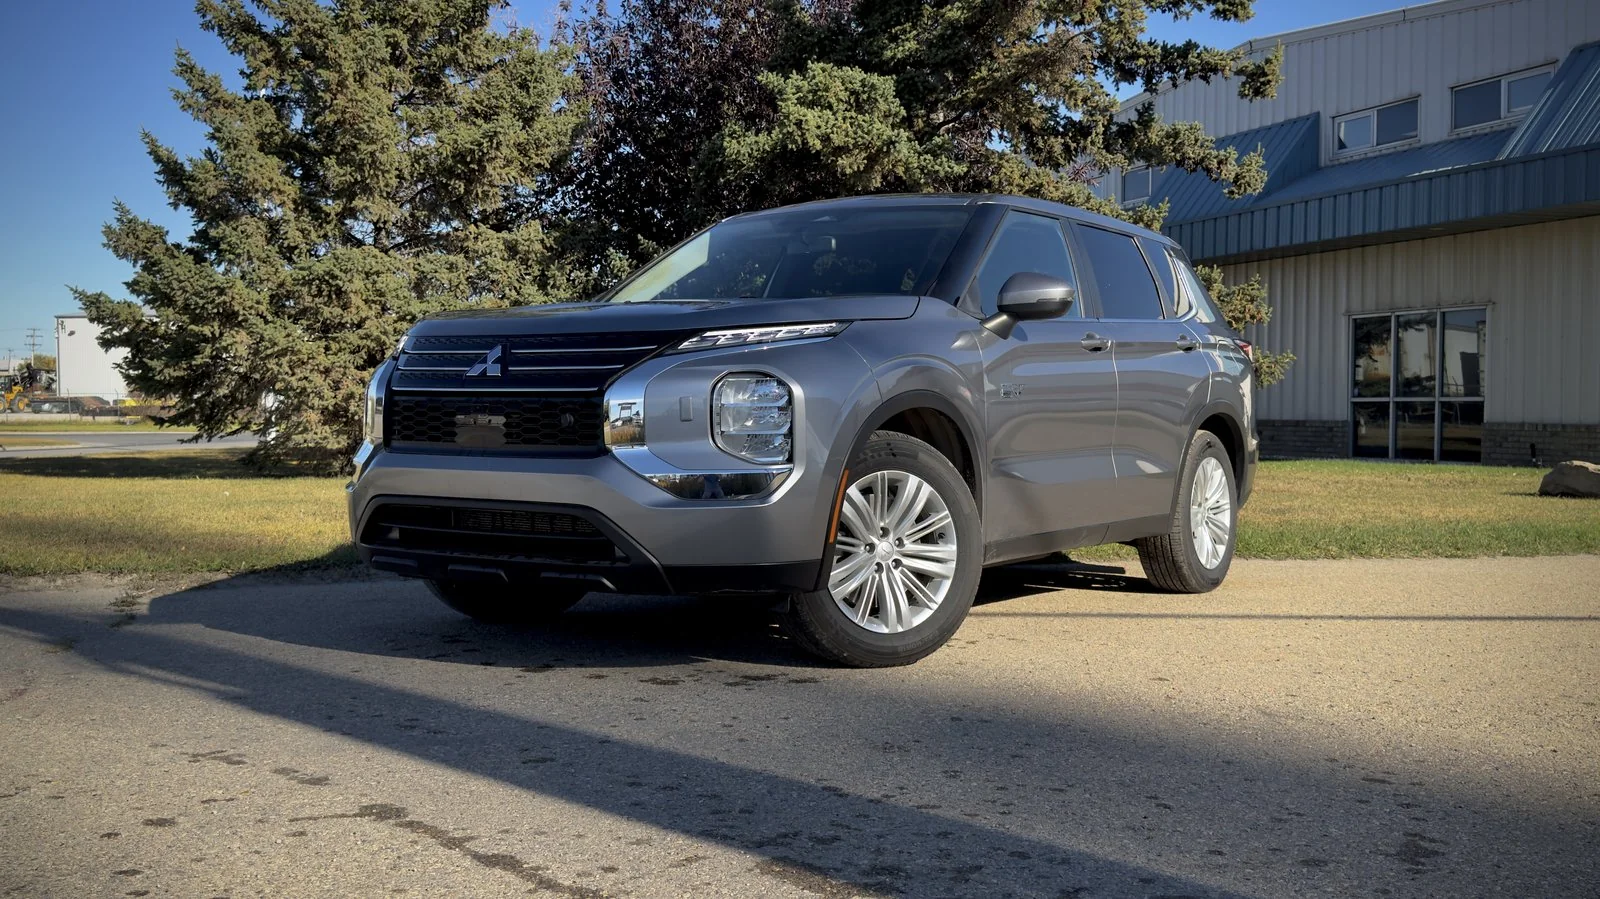
2023 Mitsubishi Outlander ES PHEV
$192 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $6,872
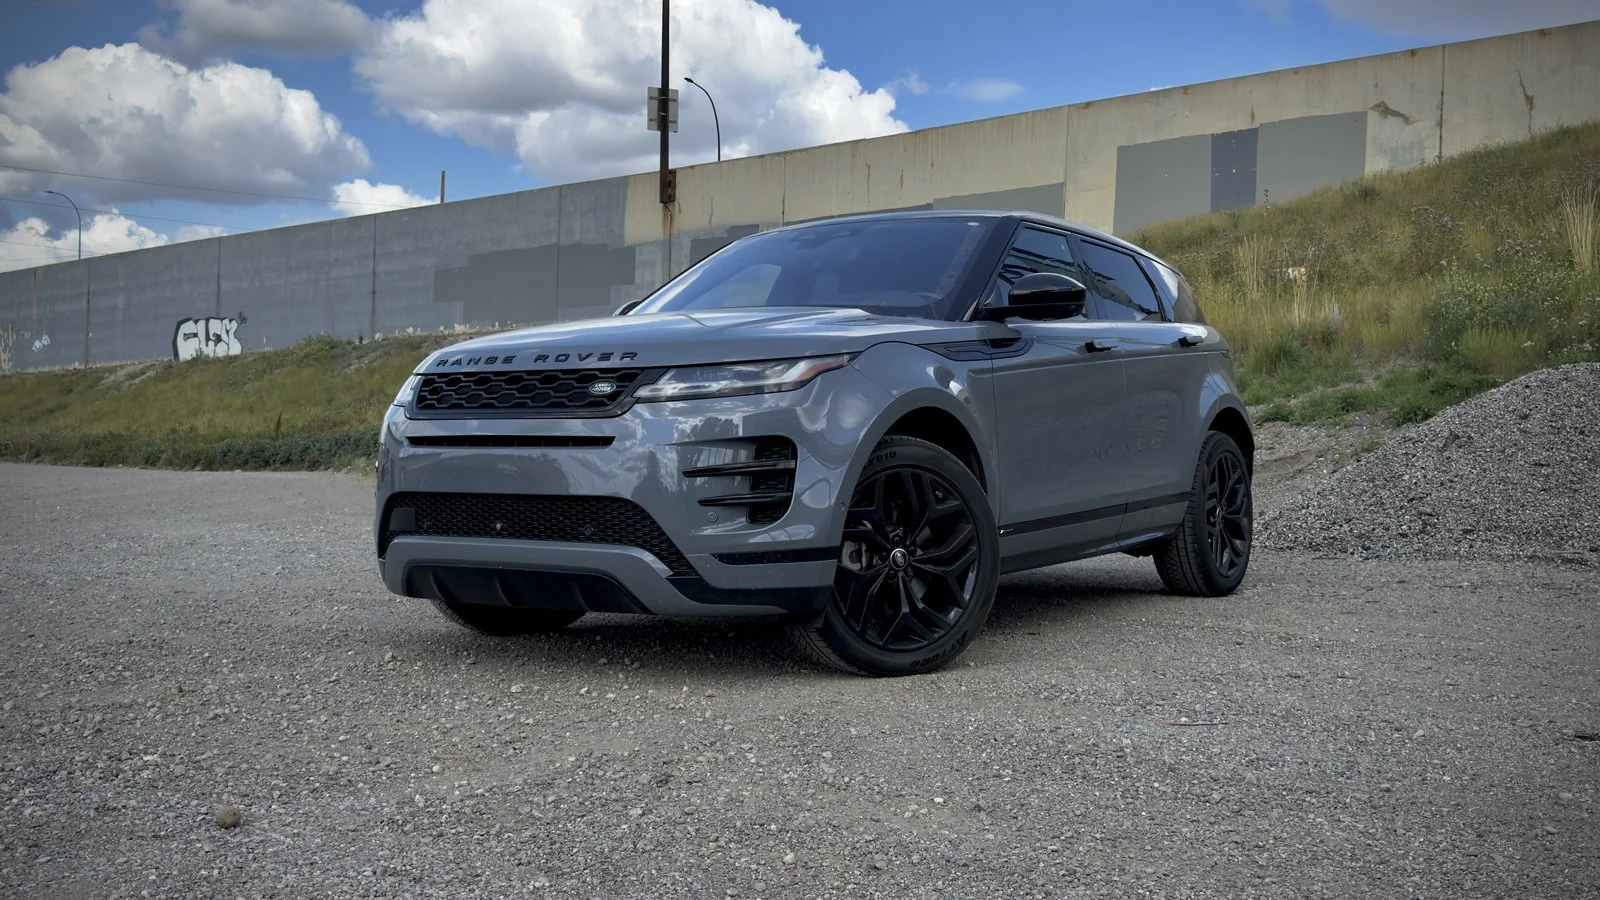
2021 Land Rover Range Rover Evoque R-Dynamic HSE
$212 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $7,609
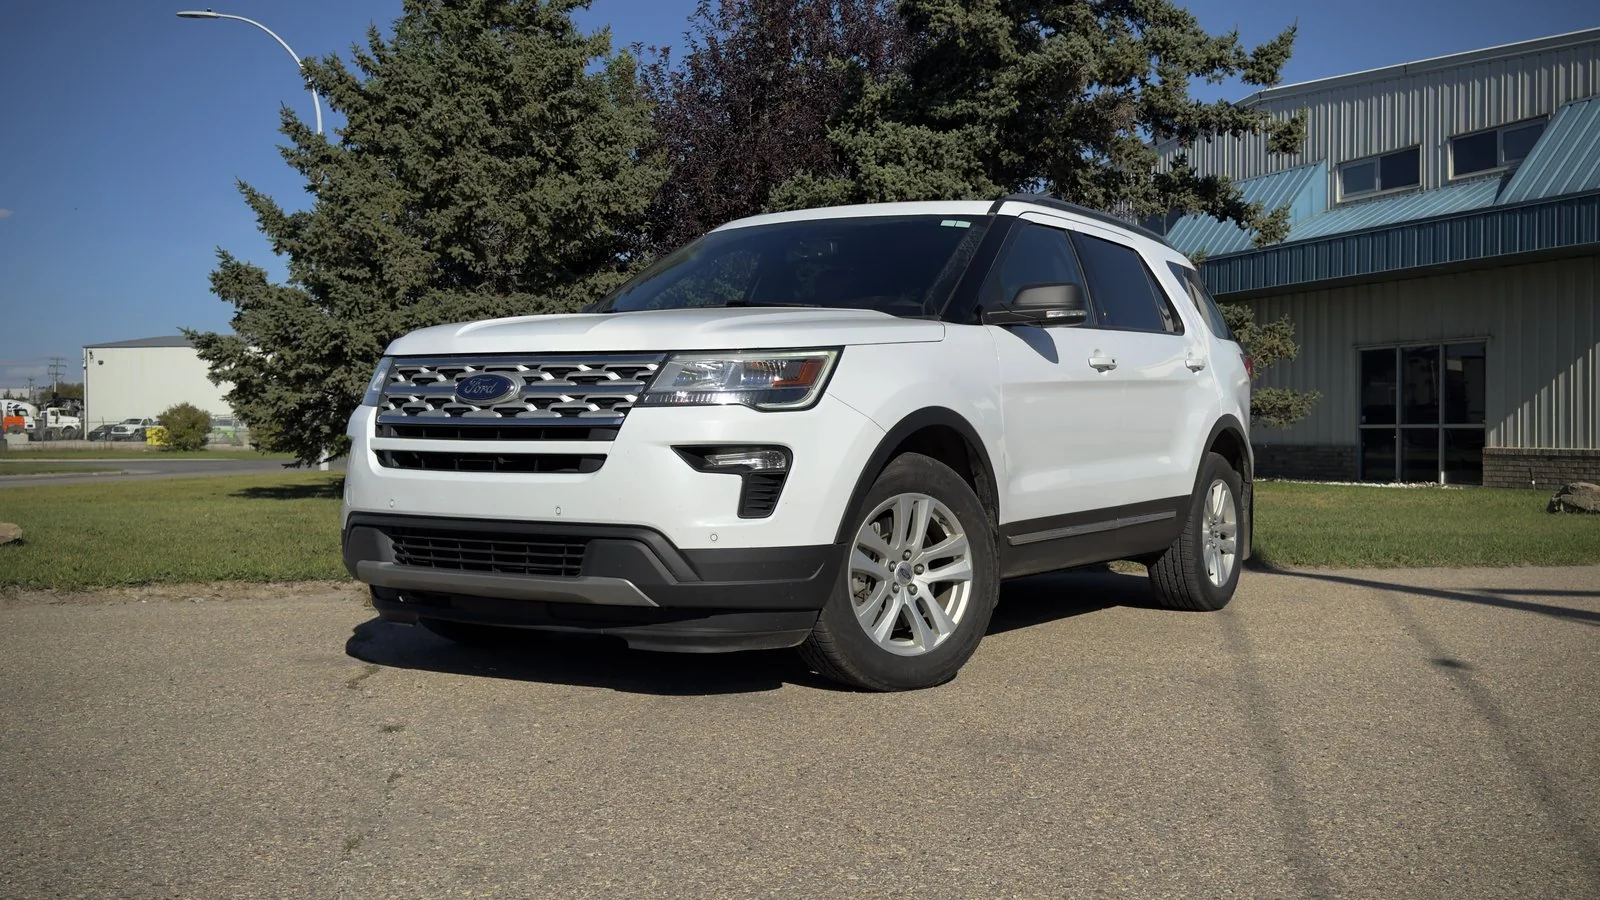
2019 Ford Explorer XLT
$123 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $4,416
OAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Flat-rate and commission pay: common questions
Can a flat-rate technician get a car loan in Alberta?
You can apply. Lenders compare your proven pay with the payment and look at how long you have worked. When pay moves with the work, a lender may ask for more than one pay stub. We cannot promise a result. We review every application and call you back, and each lender decides each file.
How do lenders count flat-rate or commission pay?
None of the lender pages we read gives a formula. They list documents. How much of your variable pay a lender counts is each lender’s call. A pay stub shows one pay period, so a T4, a year-end stub or an employer letter can show the pattern.
Is a T4 enough, or do I need pay stubs?
One bank’s credit-granting page says: “A T4 slip or a pay stub is generally required as minimum proof of income. Depending on the type of income you earn (for example, if you are self-employed or a contracted employee) and the type of loan you require, more information may be requested.” So a T4 or a pay stub is the usual minimum, and a lender may ask for more when pay varies.
How many months of pay stubs should I bring if my pay changes?
There is no one number, and every lender sets its own list. One loan guide says: “Be sure that you have records going back at least three months.” Bringing more than the minimum helps a lender see the pattern: your last two stubs, a longer run of recent ones, and your year-end stub or T4.
What should my employer’s letter say?
A loan guide says: “One of the most essential parts of any letter from your employer is your salary information and pay/compensation structure.” Ask for a letter on company letterhead that gives your job title and start date and explains how you are paid: flat rate, hourly, commission or a mix. If there is a base amount or a minimum number of paid hours, ask for it to be stated.
What if I just changed shops or pay plans?
A recent change means a shorter pay history. Bring your offer letter or a letter that describes the new pay plan, plus your first pay stubs. See how lenders handle a new job or probation on our new-job page. We review every application and call you back.
Sources (pages opened October 6, 2026): TD Canada Trust: Credit granting; Affinity Credit Union: loans; ATB: Navigating car loans in Alberta; CIBC: Personal Car Loan; Loans Canada: letter of employment; Loans Canada: car loan approval; Canada Revenue Agency: Line 10120, commissions included on line 10100; Canada Revenue Agency: Line 10100, employment income; Government of Alberta: Employment standards rules, payment of earnings. These are public pages, quoted as written. Every lender sets its own rules, so check the lender’s own page before you rely on a detail.
Last reviewed October 2026 by the Shift Happens finance team
What Our Customers Say
“Great experience with the team at Shift. The whole experience was easy from start to finish. Wes was quick to respond and answer all my questions. Luke was a dream with the paperwork.”
“Luke and Wes were beyond wonderful and helpful to deal with. Luke went above and beyond multiple times to make this purchase happen. Wouldn't hesitate to recommend to anyone I know!”
“Had an amazing experience at this dealership from start to finish. Huge thanks to Luke for being professional, knowledgeable, and genuinely making the whole process stress-free.”
Other Financing Options
See what you pre-qualify for
Apply online. We review every application and call you back.
★★★★★ 118+ Google Reviews · AMVIC Licensed · Free Delivery 300km