
Financed SUV or a Cheap Marketplace Car: What Does Each Really Cost?
Is a financed SUV or a cheap Marketplace car the better deal?
A cheap Marketplace car costs less up front and has no interest if you pay cash, but nobody knows what it needs until it is inspected. A financed $24,000 SUV costs about $531 a month in our example, with an inspection and a written vehicle history before you sign. Which costs less depends on repairs. Example, not an offer.
This page is part of our guide to private sale car financing in Alberta. For the wider question of buying from a private seller or a dealer, see private sale vs dealer purchase. Most private sellers are ordinary people selling a car they have driven. This page is about who carries the risk, not who is selling.
Who this page is for
- You are looking at a cheap car on Facebook Marketplace or Kijiji and wondering if a financed SUV is the smarter buy.
- You work, and your credit took a hit.
- You want the real numbers, and an honest list of what nobody can know yet.
In our experience, lenders typically look for about $2,800 a month in income you can prove, from all sources combined. If you are under that, talk to us first. A co-applicant, a bigger down payment or a few months of income history can change the picture.
Key Facts
- The question
- A cheap private-sale car, or a financed SUV
- Example private-sale car
- $9,000, paid in cash
- Example financed SUV
- $24,000 plus GST, 72 months
- Example payment
- About $531 a month (~$245/bi-weekly)
- Rate used
- 14.9% APR, the middle of the 550–599 band
- A licensed dealer must give you
- A Mechanical Fitness Assessment and the vehicle's history, in writing, before you sign
See what you pre-qualify for
A few quick answers. No commitment.
What does a cheap Marketplace car really cost?
Start with the price: $9,000 in our example, paid in cash. The Canada Revenue Agency says GST does not generally apply to a private sale, such as a purchase from a person who is not a GST/HST registrant. Then add what it costs to find out what you are buying. Those checks are yours to arrange and pay for.
- A lien search. A registry agent searches the Personal Property Registry using the vehicle's VIN. Fees vary by agent: one charges $10.00, another $15.00 plus disbursements. The Government of Alberta says that if you buy a car with a lien you may be responsible for it.
- A pre-purchase inspection. AMVIC, the council that licenses Alberta's vehicle dealers, recommends a pre-purchase mechanical inspection by an automotive technician. Ask the shop its price before you book.
- An out-of-province inspection, if the car came from another province. The car has to pass one before it can be registered in Alberta. Inspection facilities set their own prices and must post them, and the vehicle owner pays.
Those checks are only part of the picture. The line that decides the real cost is the one nobody can fill in yet: what the car needs. The sections below show who carries that risk.
What does a financed SUV cost, interest included?
Take a $24,000 used SUV. At a licensed Alberta dealer, GST at 5% is added to the advertised price: $1,200. With $0 down, the loan is $25,200. At the middle of the 550–599 band's rate over 72 months, that is about $531 a month, or ~$245/bi-weekly.
Worked example
- Gross pay
- $5,500 a month
- Credit score
- 550–599
- Vehicle
- used SUV ($24,000 plus GST), $25,200
- Down payment
- $0
- Amount financed
- $25,200 over 72 months
- Example rate
- 14.9% APR (the middle of the 550–599 band)
Payment: ~$245/bi-weekly (or ~$531/mo)
That is about 10% of gross monthly pay. A common rule of thumb is to keep a car payment under 15% of gross pay.
Example, not an offer. Your rate depends on your file; rates run from 4.99% APR (prime) to 29.9% APR (deep subprime).
Over the whole loan you would pay about $38,270 in payments, and about $13,070 of that is interest. That interest is the price of borrowing, and it is real money. The Financial Consumer Agency of Canada's advice is to look at the full cost over the term of the loan, interest included, and not only the monthly payment.
The example leaves out any fee a lender charges. In Alberta, the advertised price of a licensed dealer's vehicle must include all fees except GST and the cost of financing, and AMVIC notes that separate financing costs or charges may apply if you finance. Ask for the full cost of borrowing in writing before you sign.
On the rule of thumb of a payment near 15% of gross monthly pay, that payment fits gross pay of about $3,600 a month. To see what pay a bigger loan needs, read the income a 3-row SUV or minivan loan needs.
How do the two compare, line by line?
One row for each thing a buyer can weigh. The prices are examples and the SUV's numbers are computed. The last row is the one that no table can fill in.
Slide the table sideways to see both columns.
| Cheap private-sale car | Financed, inspected SUV | |
|---|---|---|
| Price (example) | $9,000 | $24,000 |
| GST | Not generally charged on a private sale | $1,200 at 5% |
| Interest | None if you pay cash | About $13,070 over 72 months |
| What you pay | $9,000 up front, plus the checks | About $531 a month, $0 down |
| Checking the car | You arrange and pay for the lien search, a vehicle history report and an inspection | A licensed dealer must give you a Mechanical Fitness Assessment and the vehicle's history in writing before you sign. Ours is a 162-point inspection |
| Liens | You search. If you buy a car with a lien, you may be responsible for it | A licensed dealer must pay out any lien within seven days of the sale |
| If something breaks | Yours from the day you buy it | Still possible on a used vehicle. Ask what any warranty covers, in writing |
Read it honestly: if the $9,000 car is sound and you can pay cash, you will spend less on it than on the financed SUV, with no interest and no GST. The two are not the same vehicle, so what the extra money buys is a different car, information before you sign, and a fixed payment you can plan around. The inspection we do on every vehicle is covered on its own page, and our warranty options show what extra cover looks like.
Who pays when something goes wrong?
Alberta's consumer rules for vehicle sales cover sales by businesses to consumers. AMVIC puts it this way: “The rules only apply to transactions between businesses and consumers.” A licensed business must give you a completed Mechanical Fitness Assessment before you sign a contract to buy a used vehicle, and it must tell you the vehicle's history in writing before you buy: for example, whether it was ever a salvage vehicle, a taxi or a rental. AMVIC also says: “Private sellers are not required to provide a Mechanical Fitness Assessment.”
Be clear about what a Mechanical Fitness Assessment is. AMVIC says it is “an assessment” and “not a pass/fail inspection,” and it is valid for 120 days. It is not a warranty. The Government of Alberta says that any warranty offered with a sale should be in writing and should state exactly what is covered and who is providing it. So on either side of this page, a used vehicle can still need repairs. The difference is what you can see before you sign.
AMVIC also warns about curbers: unlicensed businesses that sell vehicles, some of them posing as private sellers. An ordinary private seller is not a curber, but the same checks protect you from both. Consumers can ask AMVIC to investigate if a licensed business does not operate lawfully.
When does the cheap car make sense, and when does the financed SUV?
The cheap car can be the right call when you have the cash and still have money left for a repair, you have a technician you choose inspect it before you pay, and the lien search and the history report come back clean.
The financed SUV can be the right call when a surprise repair would push you to borrow anyway, you want one fixed payment you can plan around, and you want an inspection report and the vehicle's history in writing before you sign.
Neither is right if the payment would not fit your pay. Try the rule of thumb in how much car loan your pay can carry, or call us at (825) 736-4438 and we will go through your numbers.
Can I finance the Marketplace car instead?
Sometimes. Lenders treat a private purchase differently from a dealer purchase, so it depends on the file. We can look at financing a car you found on Marketplace or Kijiji, and every lender decides each file. Send us the listing before you pay the seller, so the checks happen in the right order. The steps are in buying from a Marketplace seller in Alberta, step by step, and the full process is in our guide to financing a private sale.
Example payments are estimates. Not an offer.
SUVs in stock right now
Browse all inventory →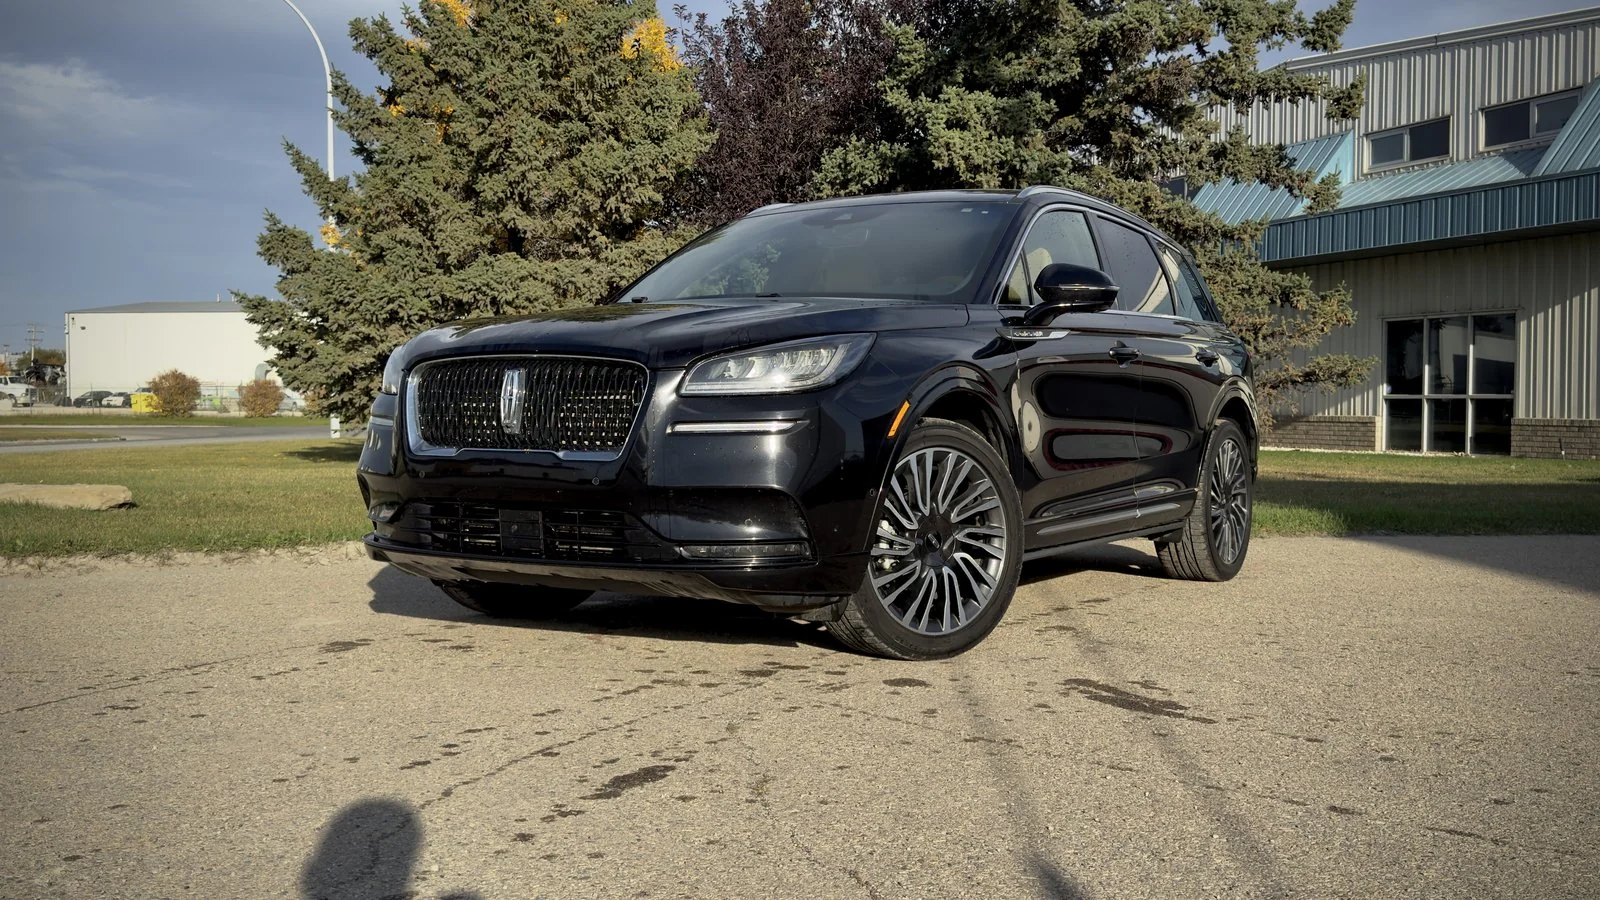 Reconditioning
2021 Lincoln Corsair Reserve
$198 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $7,117
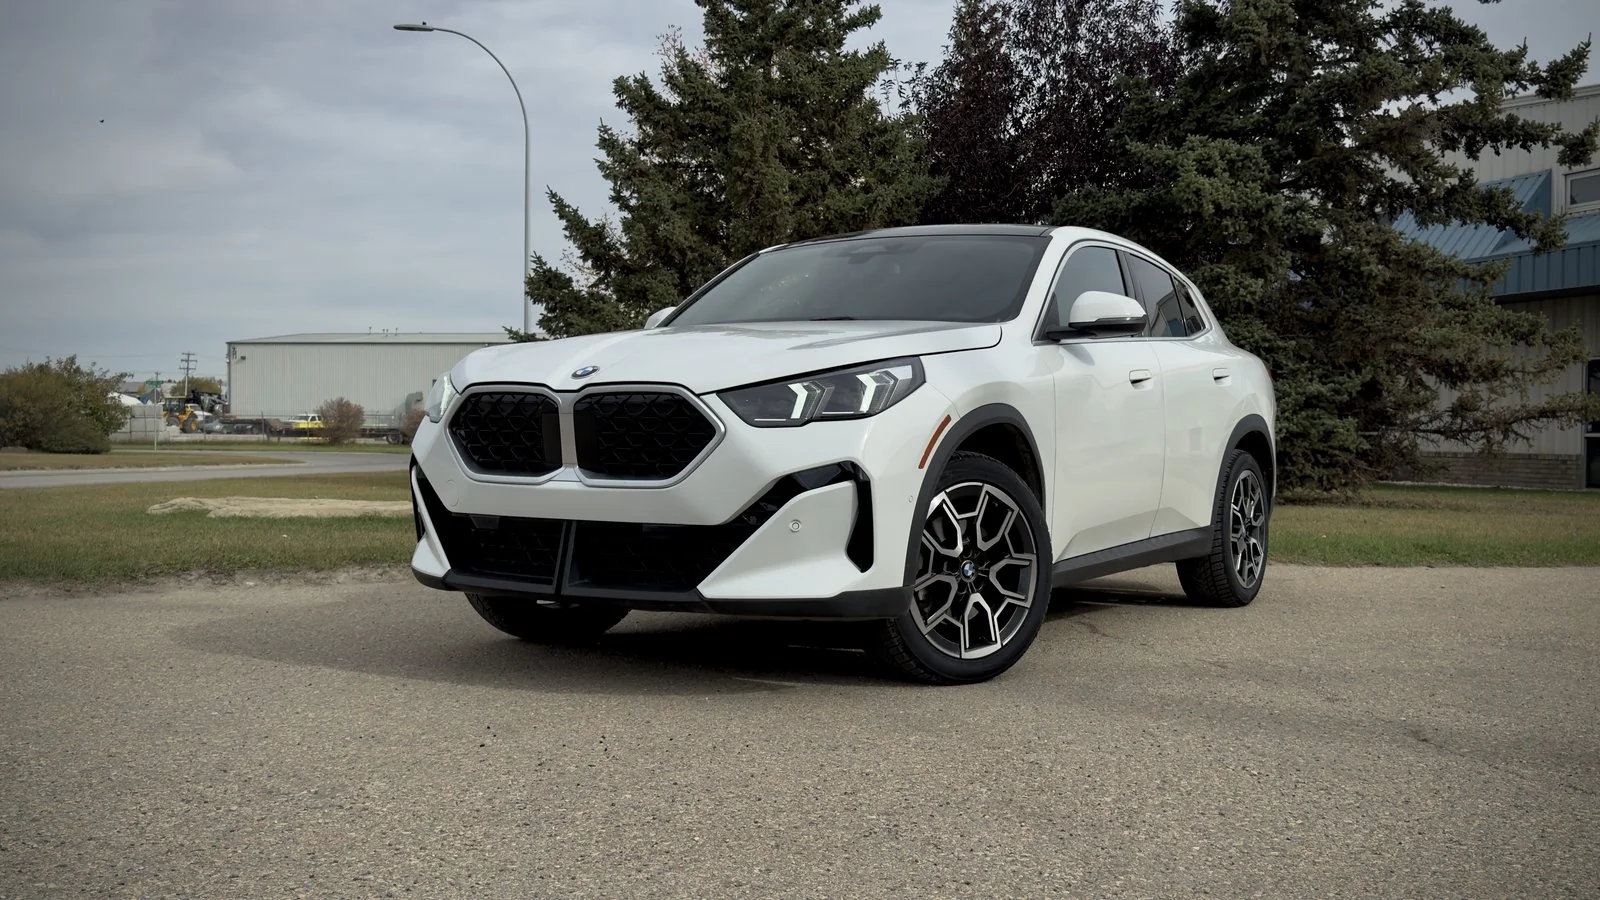
2025 BMW X2 xDrive28i
$246 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $8,835
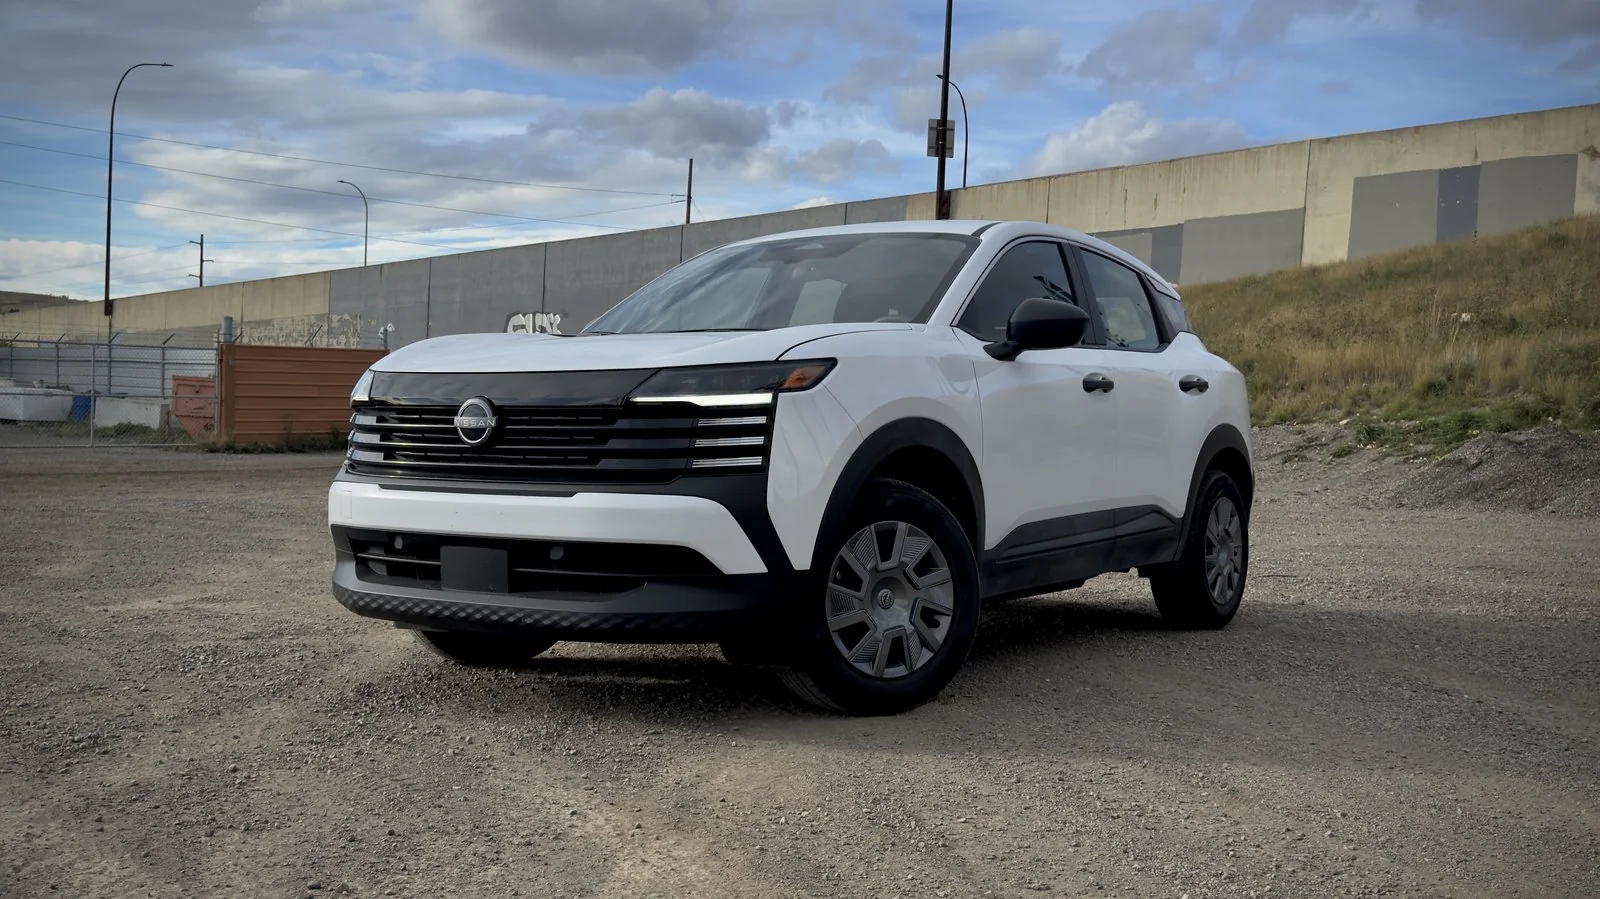
2026 Nissan Kicks S
$185 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $6,626
OAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Financed SUV or Marketplace car: common questions
Is it cheaper to buy a car on Facebook Marketplace?
The price can be lower, and a private sale does not generally carry GST. What it does not come with is a Mechanical Fitness Assessment or a written vehicle history, and any repair is yours from the day you buy. The real cost depends on what the car needs, which is why a pre-purchase inspection comes first.
Do I need an inspection to buy a car from a private seller in Alberta?
The Government of Alberta lists a safety inspection as a step before you buy, and AMVIC recommends a pre-purchase mechanical inspection by an automotive technician. A car last registered outside Alberta must also pass an out-of-province inspection before it can be registered there. Ask the shop its price before you book.
What is a Mechanical Fitness Assessment?
A licensed dealer must give you a completed Mechanical Fitness Assessment before you sign a contract to buy a used vehicle. AMVIC describes it as an assessment, not a pass/fail inspection, and it is valid for 120 days. A private seller is not required to give you one.
How much is the payment on a financed $24,000 SUV?
In our example, about $531 a month (~$245/bi-weekly) over 72 months with $0 down, GST included, at the middle rate of the 550–599 score band. Interest over the loan is about $13,070. Example, not an offer: your rate depends on your file, and every lender decides each file.
Can I finance a car I found on Marketplace?
Lenders treat a private purchase differently from a dealer purchase, so it depends on the file. We can look at financing a private-sale car: the lien status, the inspection and your income all matter. Send us the listing before you pay the seller. We review every application and call you back, and every lender decides each file.
What if I can only afford the cheap car?
Then protect yourself with the checks: a lien search, a vehicle history report and an inspection by a technician you choose, and keep some money aside for repairs. AMVIC suggests negotiating the cost of any necessary repairs into the purchase agreement, and not rushing: there are other vehicles out there.
Sources (pages opened October 5, 2026): Government of Alberta: buying a vehicle from a private seller; Government of Alberta: inspect before you buy; Government of Alberta: out-of-province vehicle inspections; AMVIC: buying used; AMVIC: before you go shopping; AMVIC: all-in pricing is the law; Canada Revenue Agency: GST/HST and motor vehicles; Financial Consumer Agency of Canada: how much car can you truly afford?; Accu-Search Registries: lien search; CNN Corporate Services: personal property searches. Wording and prices are as each page showed them that day; registry agents set their own fees. The prices, payments and interest above are our own examples, worked out from the maths on this page.
Last reviewed October 2026 by the Shift Happens finance team
What Our Customers Say
“The truck is gorgeous and it's exactly what they said it was. I recommend to anyone.”
“Simply amazing! Finding an affordable car these days is almost impossible, but Shahdeen and Luke made the entire process so smooth and stress-free. Knowledgeable, honest, and no pressure.”
“I honestly can't thank Luke enough. From start to finish he was patient, respectful, transparent, and genuinely cared about helping me find the right vehicle instead of just making a sale.”
Other Financing Options
See what you pre-qualify for
Apply online in about three minutes. We review every application and call you back.
★★★★★ 118+ Google Reviews · AMVIC Licensed · Free Delivery 300km