
Owner-Operator vs Employee Trucker Car Loans
In this article
- Do Owner-Operators Face Different Car Loan Rules Than Employee Truckers?
- What Does an Employee Trucker Bring?
- What Does an Owner-Operator Bring?
- What Does a Tax Return Show After Write-Offs?
- Does It Matter If My Truck Runs Through a Corporation?
- How Does My Truck Loan Affect a Personal Car Loan?
- What If My Income Moves With the Seasons?
- Frequently Asked Questions
- Can owner-operators in Alberta qualify for personal vehicle loans?
- Do trucking per diems count toward car loan income in Alberta?
- How long does a car loan decision take for a self-employed trucker?
- What credit score do I need for a car loan as an Alberta owner-operator?
- What Should I Do Next?
Check Your Options in 3 Minutes
No credit impact. All credit situations welcome.
★★★★★ 118+ Google Reviews · AMVIC Licensed · Free Delivery 300km
Two truckers can run the same routes and earn the same on the road. One drives for a carrier and gets pay stubs and a T4. The other owns the truck and files a tax return. A lender reads those two paper trails differently.
This post covers what each trucker brings to a car loan, and what an owner-operator can put next to a tax return that looks low after write-offs. The documents are listed on our page about what else can show your income when write-offs lower your taxable income. If your credit took a hit, the papers are the part you can get ready ahead of time.
See what you pre-qualify for
Three quick answers — soft check, no commitment.
Do Owner-Operators Face Different Car Loan Rules Than Employee Truckers?
The paperwork is different. Lender pages commonly list a pay stub, an employer letter or a T4 for employees, and a Notice of Assessment and T1 General for self-employed applicants. Every lender sets its own list and decides each file. We review every application and call you back.
What Does an Employee Trucker Bring?
If you drive for a carrier, you bring what any employee brings. The lender pages we read list a recent pay stub, a letter from your employer, or a T4. One bank asks for your last two pay stubs. One credit union asks for two sources: your last two pay stubs or an employer letter, plus your latest T4 or Notice of Assessment.
Trucking has one wrinkle. The CRA says employment income is usually shown in box 14 of your T4, and an employer reports a taxable allowance there too. A per diem or other allowance that is not taxable may not be on your T4 at all, and a lender can only read what the papers show. If part of your pay arrives that way, ask your employer for a letter that sets out your pay and how it is made up. Each lender decides how much of it counts.
What Does an Owner-Operator Bring?
If you own your truck, a lender's list looks like a self-employed list: your Notice of Assessment and your T1 General, which is your tax return. One bank asks for your last two Notices of Assessment, another for the last two years of T1 General with the matching Notices, and one credit union for three years of T1 General and T2125, plus financial statements if you are incorporated. One Alberta lender also lists bank statements next to the tax returns. Ask how many years a lender wants before you pull everything.
You may also get a T4A from the carriers you haul for. The CRA says payments over $500 in a calendar year for services must be reported, usually on a T4A slip, and it has lifted its penalty moratorium for the trucking industry starting with the 2025 tax year. A T4A shows what a carrier paid you. It does not show what you kept after fuel, insurance and repairs. That is on your tax return, on the T2125, the form that reports your business income and your expenses.
What Does a Tax Return Show After Write-Offs?
Here is an example with made-up numbers, not a real file.
| Line on the example return | Example |
|---|---|
| Revenue from loads | $180,000 |
| Business expenses: fuel, insurance, permits, repairs and other costs of running the truck | $119,000 |
| Net income on the return | $61,000 a year, about $5,083 a month |
The CRA says that, as a rule, you can deduct any reasonable current expense you incur to earn income, so the net income on your return is lower than what came in. That is normal. The Notice of Assessment lists total income, net income and taxable income, and the CRA says you may be asked to give a copy to a financial institution to prove what your income was in the previous year.
Which line a lender uses, and how it treats your write-offs, is not published. None of the lender pages we read gives a formula, and we will not guess at one. Tell us what your Notice of Assessment shows and what your business really brings in, and we will say what to bring.
For scale: a $28,000 used pickup over 72 months at the Subprime example rate of 16.9% APR is about $621 a month ($286 bi-weekly), roughly 12% of $5,083. A common rule of thumb is to keep a car payment under 15% of gross pay. Example, not an offer: your rate depends on your file, and rates run 4.99%–29.9% APR.
Does It Matter If My Truck Runs Through a Corporation?
It can change which slip shows your pay. When a business is incorporated, its profits and losses are not automatically passed along to the owner, who can be paid a salary as an employee of the business or in dividends. A salary is employment income, usually shown in box 14 of your T4. Dividends are profits you receive from your shares in a corporation, usually reported on an information slip such as the T5. The company's own financial statements are a separate document, and one credit union asks incorporated owners for them for the last three years. How much of the money still inside the company a lender counts is the lender's call, and none of the pages we read says. How you pay yourself is a tax question for your accountant. We do not give tax advice.
How Does My Truck Loan Affect a Personal Car Loan?
Lenders look at what you already pay each month. One Canadian auto lender says its debt service ratio takes in "your total monthly payments including vehicle payment, vehicle insurance, rent/mortgage payments and any other liabilities you may have." Whether a lender counts a truck loan that your business pays is up to that lender. In our experience, it helps to say up front who pays it and to bring the papers that show it. Example with a made-up truck payment of $1,800 a month: add the $621 car payment from above and you have $2,421 a month in vehicle payments before living costs. The payment calculator lets you try prices and terms.
Lenders also ask what the vehicle is for. One Canadian auto lender says every vehicle it funds must be for personal use only. This post is about a personal vehicle, not your rig.
What If My Income Moves With the Seasons?
If your pay rises and falls through the year, bank statements show deposits as they land, and some lenders list them next to tax returns, so a slow stretch will show. If your latest months are your slowest, tell us up front, and ask how many months of statements a lender wants before you pull them. Our page on seasonal worker car financing covers pay that follows the calendar.
Frequently Asked Questions
Can owner-operators in Alberta qualify for personal vehicle loans?
You can apply. Lenders ask self-employed applicants for tax documents such as the Notice of Assessment and the T1 General, and each lender decides how much weight those numbers carry. We review every application and call you back.
Do trucking per diems count toward car loan income in Alberta?
It depends on the lender. The lender pages we read list pay stubs, T4s and employer letters, and none says how it treats a per diem. The CRA says a meal allowance is generally taxable, though it may not be in some situations, and a taxable allowance is reported in box 14 of the T4. Bring a letter from your employer that sets out how your pay is made up, with your pay stubs.
How long does a car loan decision take for a self-employed trucker?
We do not promise a time. It depends on the lender and on whether your papers are ready. Have your Notice of Assessment, T1 General and recent bank statements on hand. We review every application and call you back.
What credit score do I need for a car loan as an Alberta owner-operator?
There is no single cutoff. Lenders weigh your credit, your income and your job history together, and every lender decides each file. Your score also places you in a rate band. For example, a score of 650–749 sits in the Near-Prime tier at 6.9–12.9% APR, and 500–649 sits in the Subprime tier at 7.9–24.9% APR. Rates run 4.99%–29.9% APR overall. See car loan rates in Alberta for all seven score bands.
What Should I Do Next?
If you are an Alberta trucker, T4 employee or owner-operator, looking for a personal vehicle, the quickest start is the online application. We work with 21+ lenders, every lender decides each file, and we review every application and call you back.
Sources (pages opened October 6, 2026): CIBC: Personal Car Loan; Affinity Credit Union: personal loans; TD: personal loan application checklist; BMO: what to bring to a lending appointment; ATB: Navigating car loans in Alberta; Santander Consumer Bank (Canada): our loans; Canada Revenue Agency: line 10100, employment income; Canada Revenue Agency: lines 12000 and 12010, dividends; Canada Revenue Agency: employers' guide, taxable benefits and allowances; Canada Revenue Agency: meals provided by the employer; Canada Revenue Agency: reporting fees for service; Canada Revenue Agency: reading your notice of assessment; Canada Revenue Agency: business expenses; Canada Revenue Agency: completing Form T2125; BDC: what is a corporation.
Financing Resources
Cars you could drive home
Browse all inventory →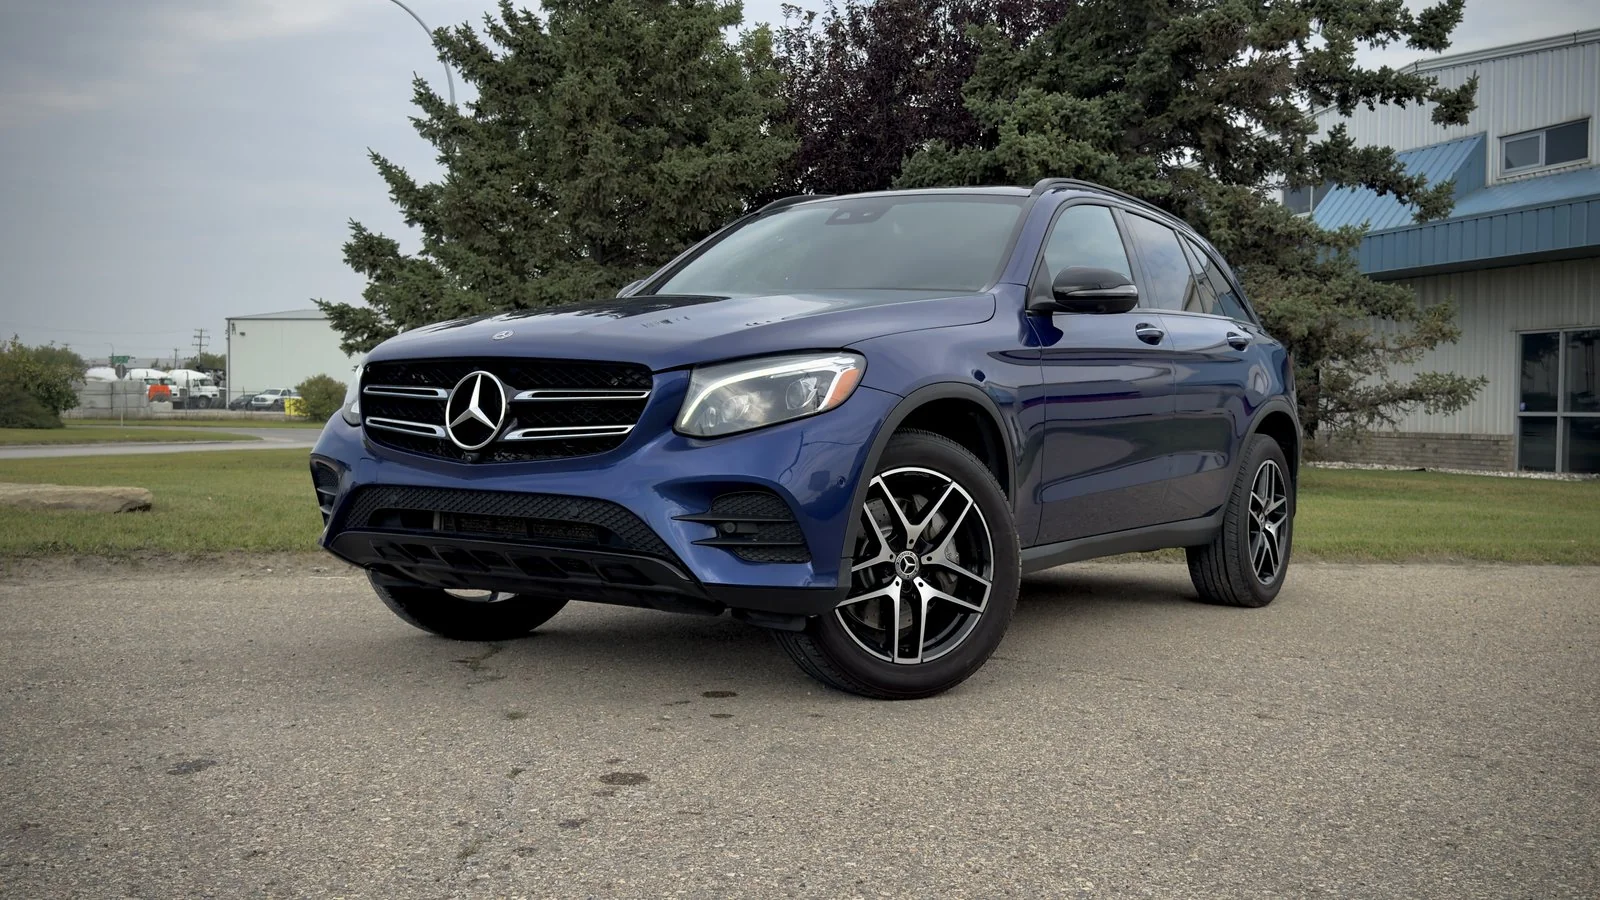
2019 Mercedes-Benz GLC-Class GLC300
$164 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $5,889
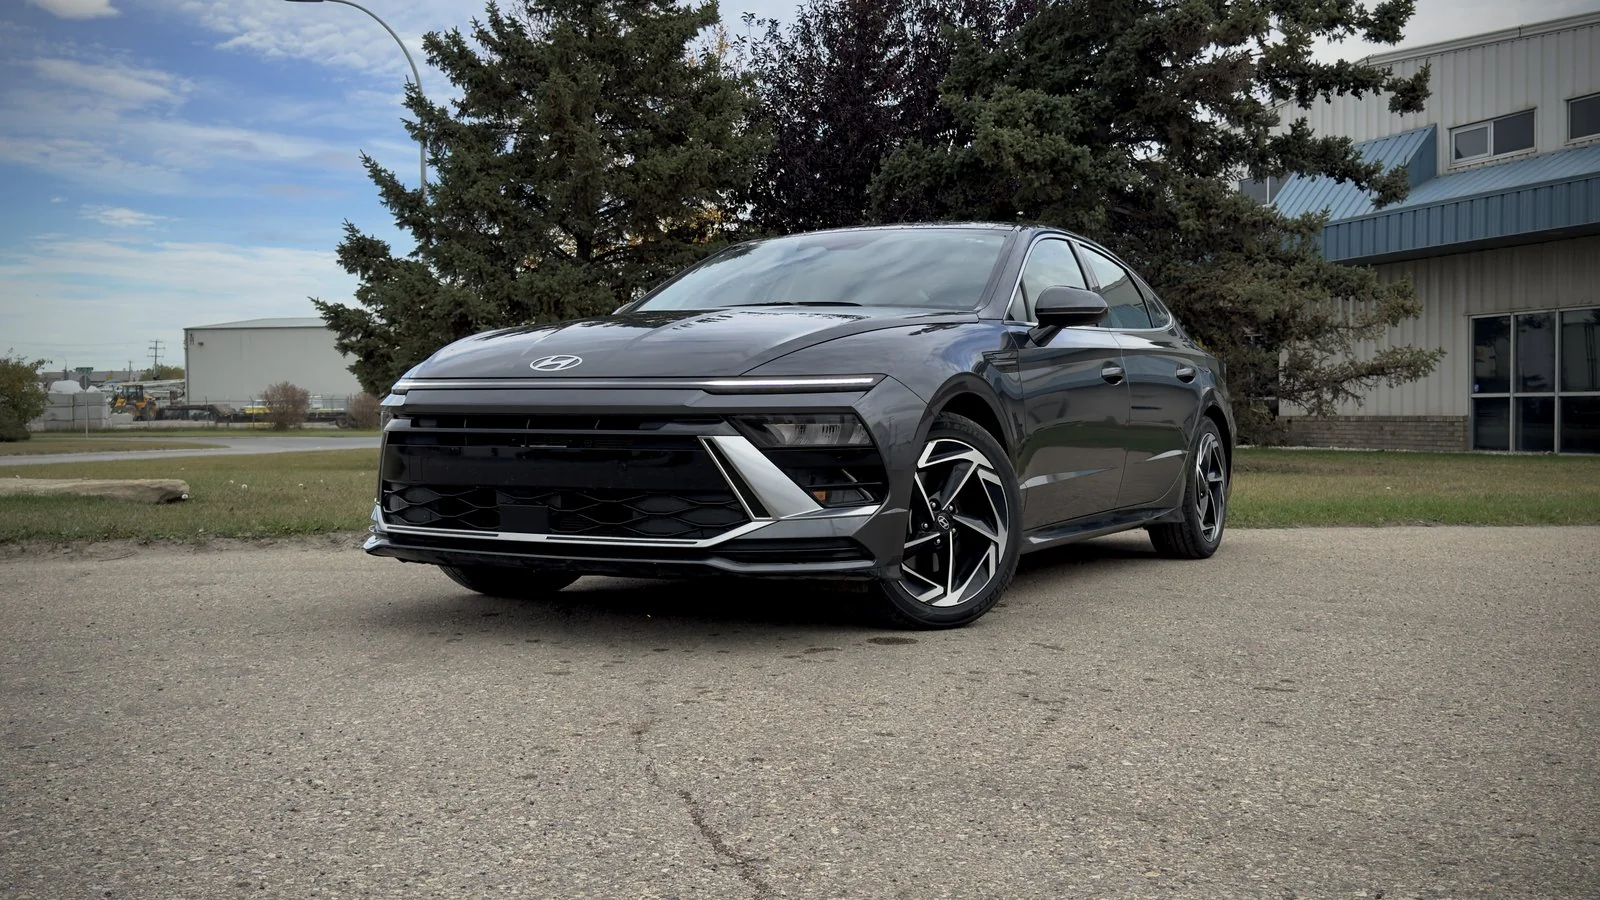
2025 Hyundai Sonata Preferred w/ Trend
$192 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $6,872
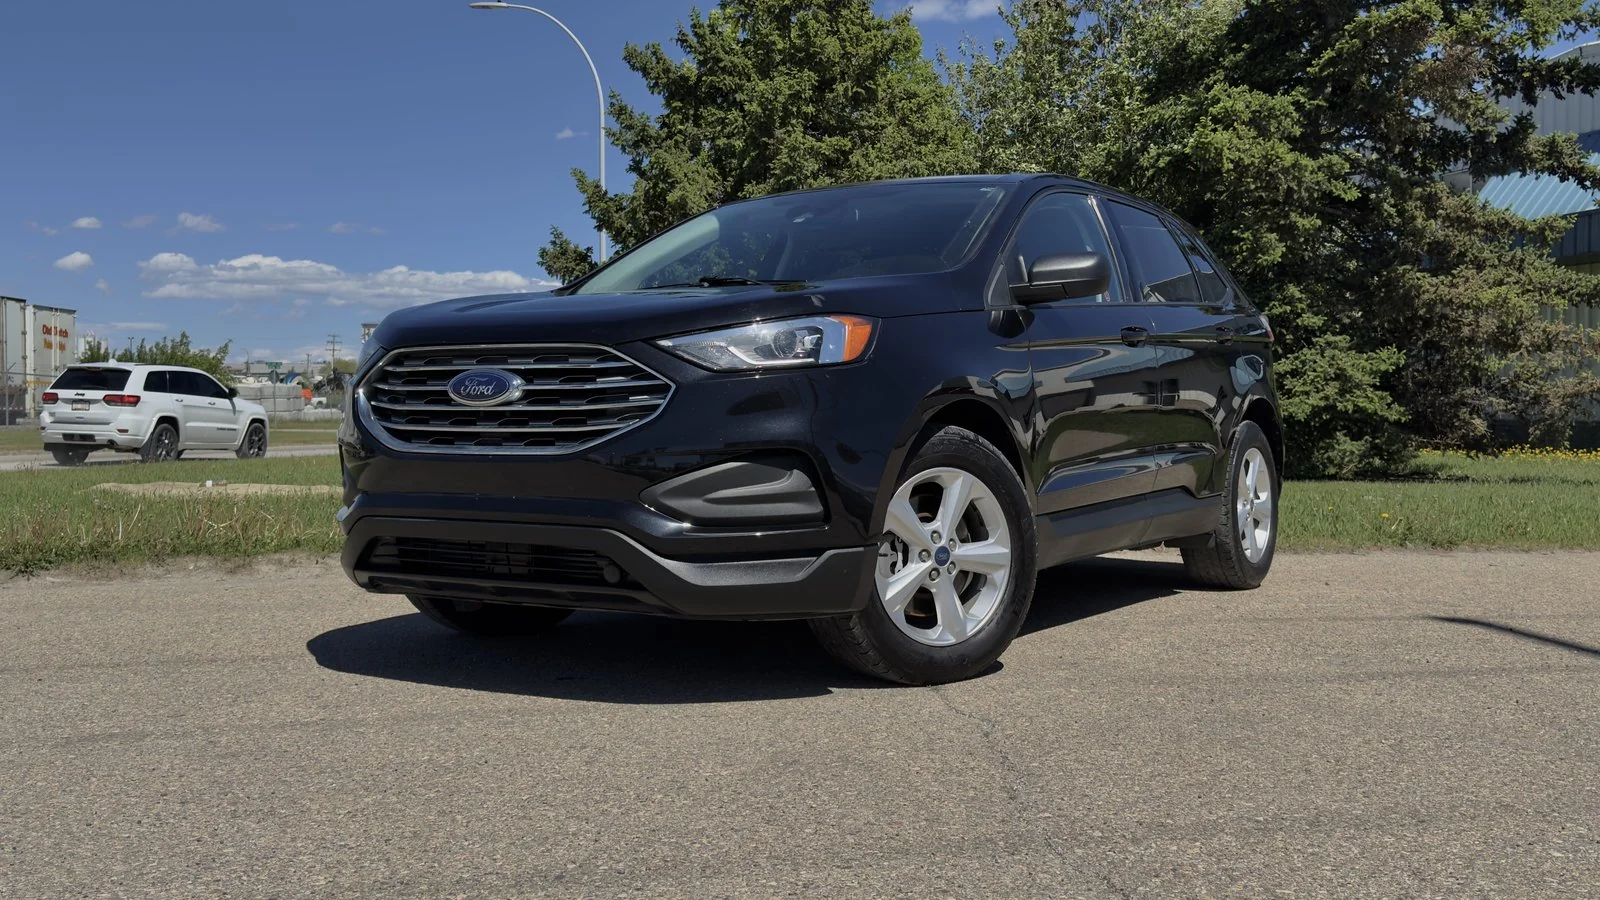
2020 Ford Edge SE
$150 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $5,398
OAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Related Articles
Ready to Find Your Vehicle?
Browse our inventory or apply for financing. All credit situations welcome.
★★★★★ 118+ Google Reviews · AMVIC Licensed · Free Delivery 300km