
Auto Score
What is an auto score?
An auto score is a credit score built for vehicle lending. Equifax Canada says that when you are buying a vehicle, the lender’s scoring model “may weight your payment history on vehicle loans more heavily.”
What Equifax Canada says about vehicle scores
“Some lenders may use credit scores that are specific to a certain industry – if you’re buying a vehicle, for instance, the credit scoring model the lender uses may weight your payment history on vehicle loans more heavily. These credit scores will differ based on the industry and are not the same as the credit scores you may receive from the two nationwide credit bureaus.”— Equifax Canada
In plain terms: a lender may use a score tuned to one industry, here car loans. It is a different score from the one a credit bureau shows you.
Why it can differ from the score you see
Equifax Canada says the credit scores available to you are often called “educational scores”, meaning “provided to you for your own education, but isn’t necessarily the same scores being used by lenders.” It also says: “Each credit bureau has multiple scoring algorithms and lenders typically request only one of them when making decisions.”
The Financial Consumer Agency of Canada (FCAC) puts it this way: “The credit score you see may be different than the score a lender sees. This is because a lender may give more weight to certain information when they calculate your score.”
What to check before you apply
- Get your report from both bureaus and read the accounts behind the number: how to check your credit score for free.
- See why scores differ from one place to the next: how credit scores work in Canada.
- Remember the number is one input. Equifax Canada says the other factors “may include information such as your income, your down payment, or the amount of the loan.”
What we can and cannot tell you
Frequently Asked Questions
Is an auto score the same as my Equifax or TransUnion score?
Equifax Canada says industry scores “are not the same as the credit scores you may receive from the two nationwide credit bureaus.”
Does a car lender only look at my score?
Equifax Canada says: “While credit scores are important, they are only one of several pieces of information an organization will generally use to evaluate your creditworthiness.” It adds that the other factors “may include information such as your income, your down payment, or the amount of the loan.” We review every application and call you back.
Which score will a car lender use for me?
That is up to the lender, and the formulas are not published. The Financial Consumer Agency of Canada (FCAC) says: “Credit bureaus and lenders use different formulas to calculate your score, but they don’t share the exact details.” We cannot say what score a lender will see, and every lender decides each file.
Cars you could drive home
Browse all inventory →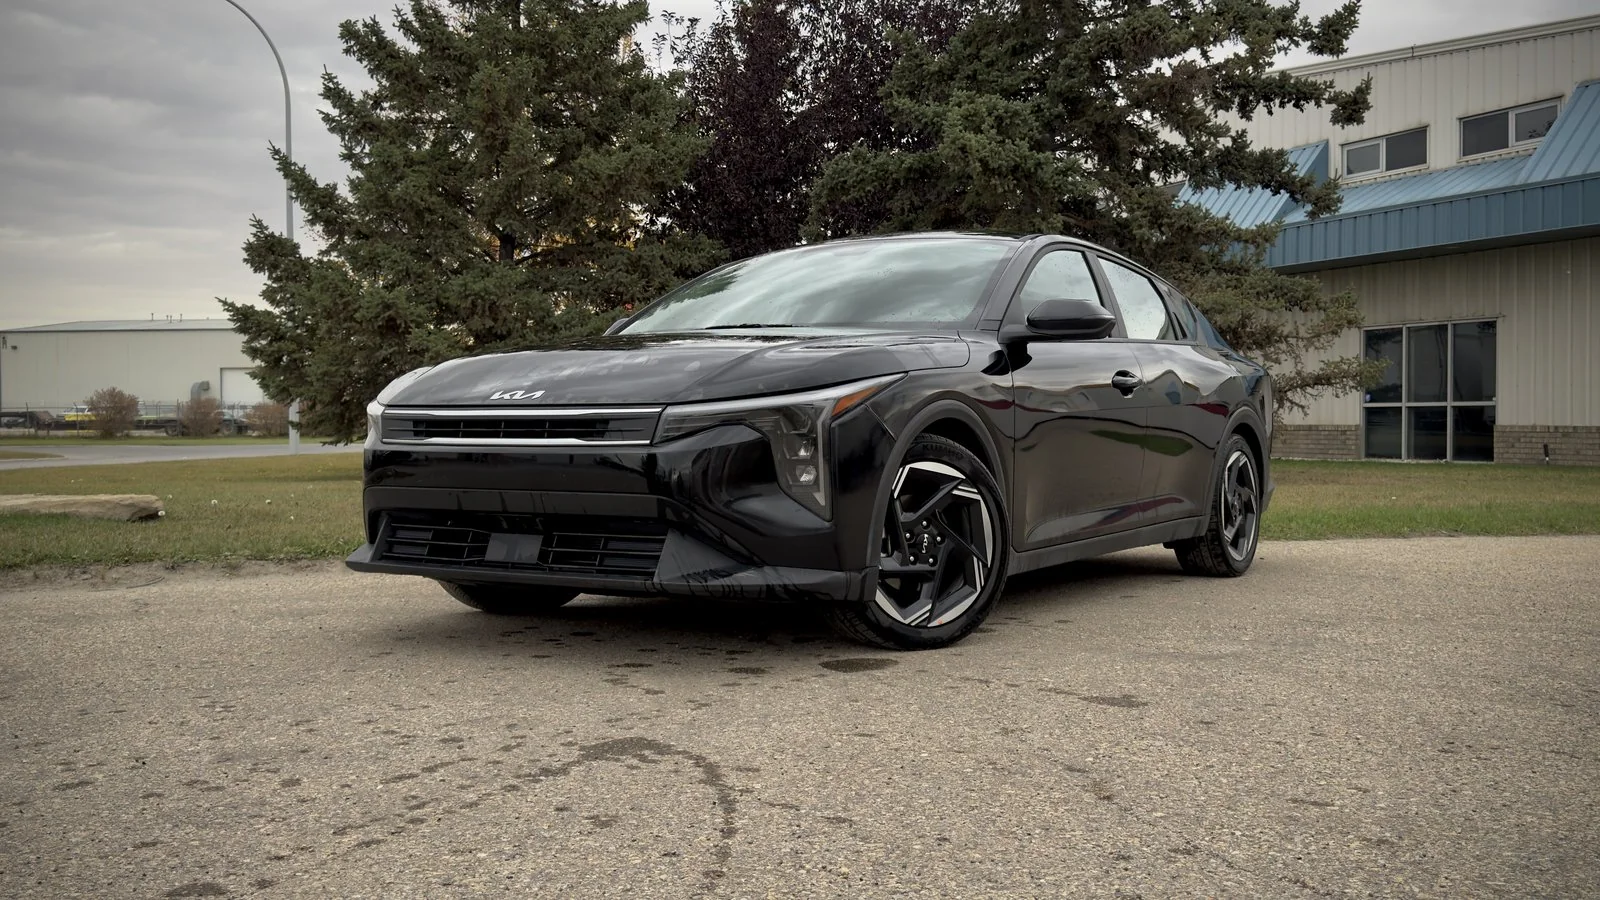
2025 Kia K4 EX
$171 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $6,136
 Reconditioning
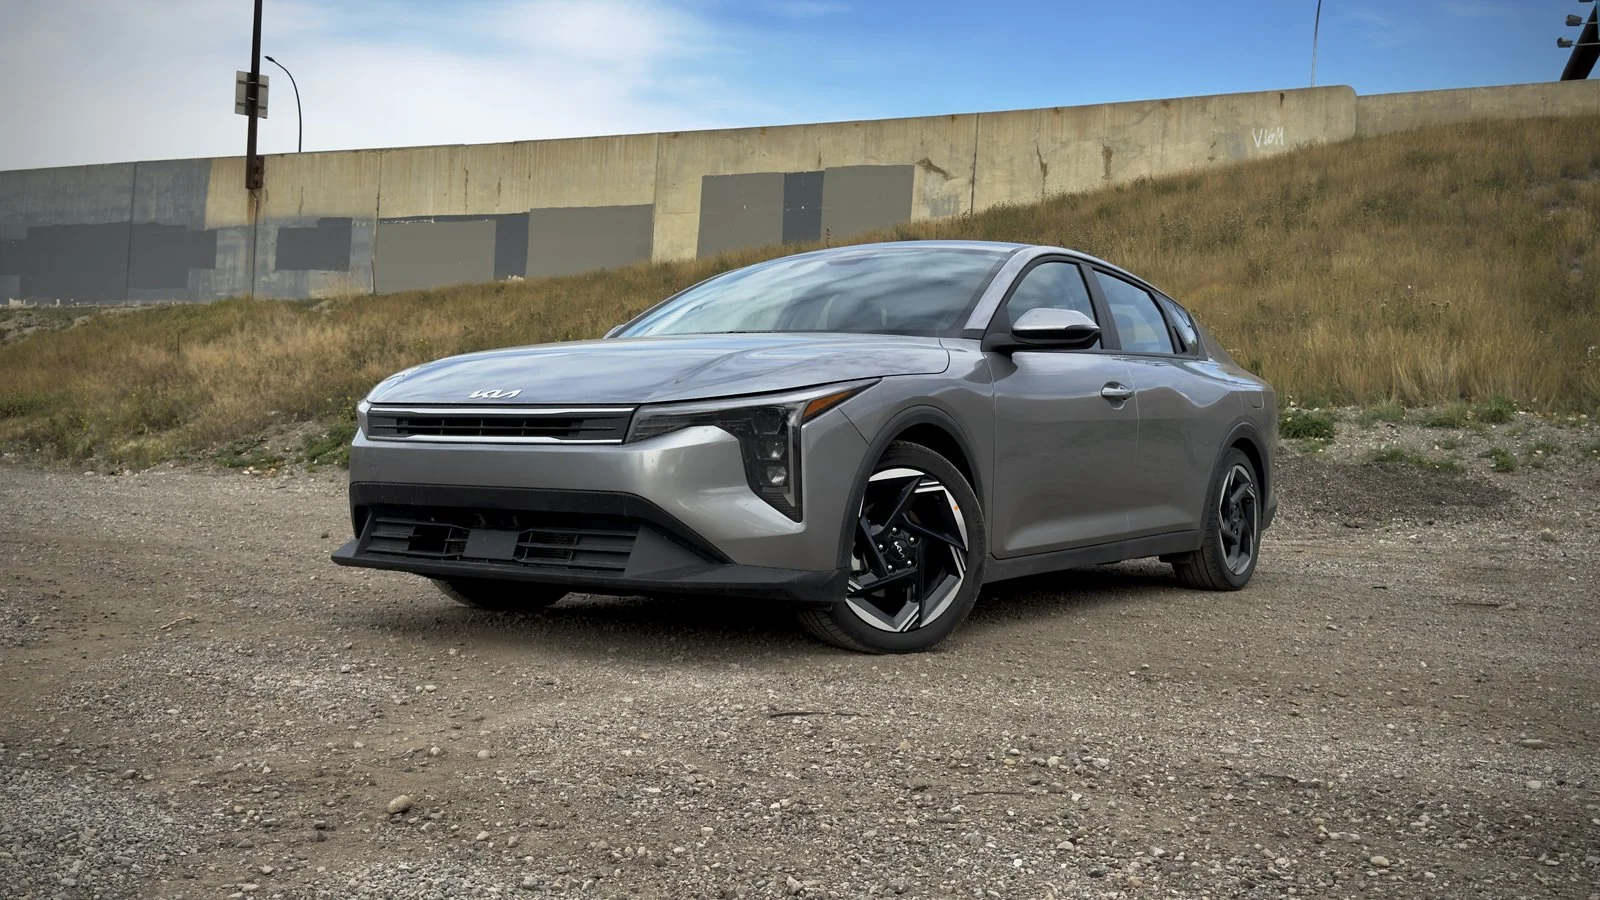
2025 Kia K4 EX
$171 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $6,136
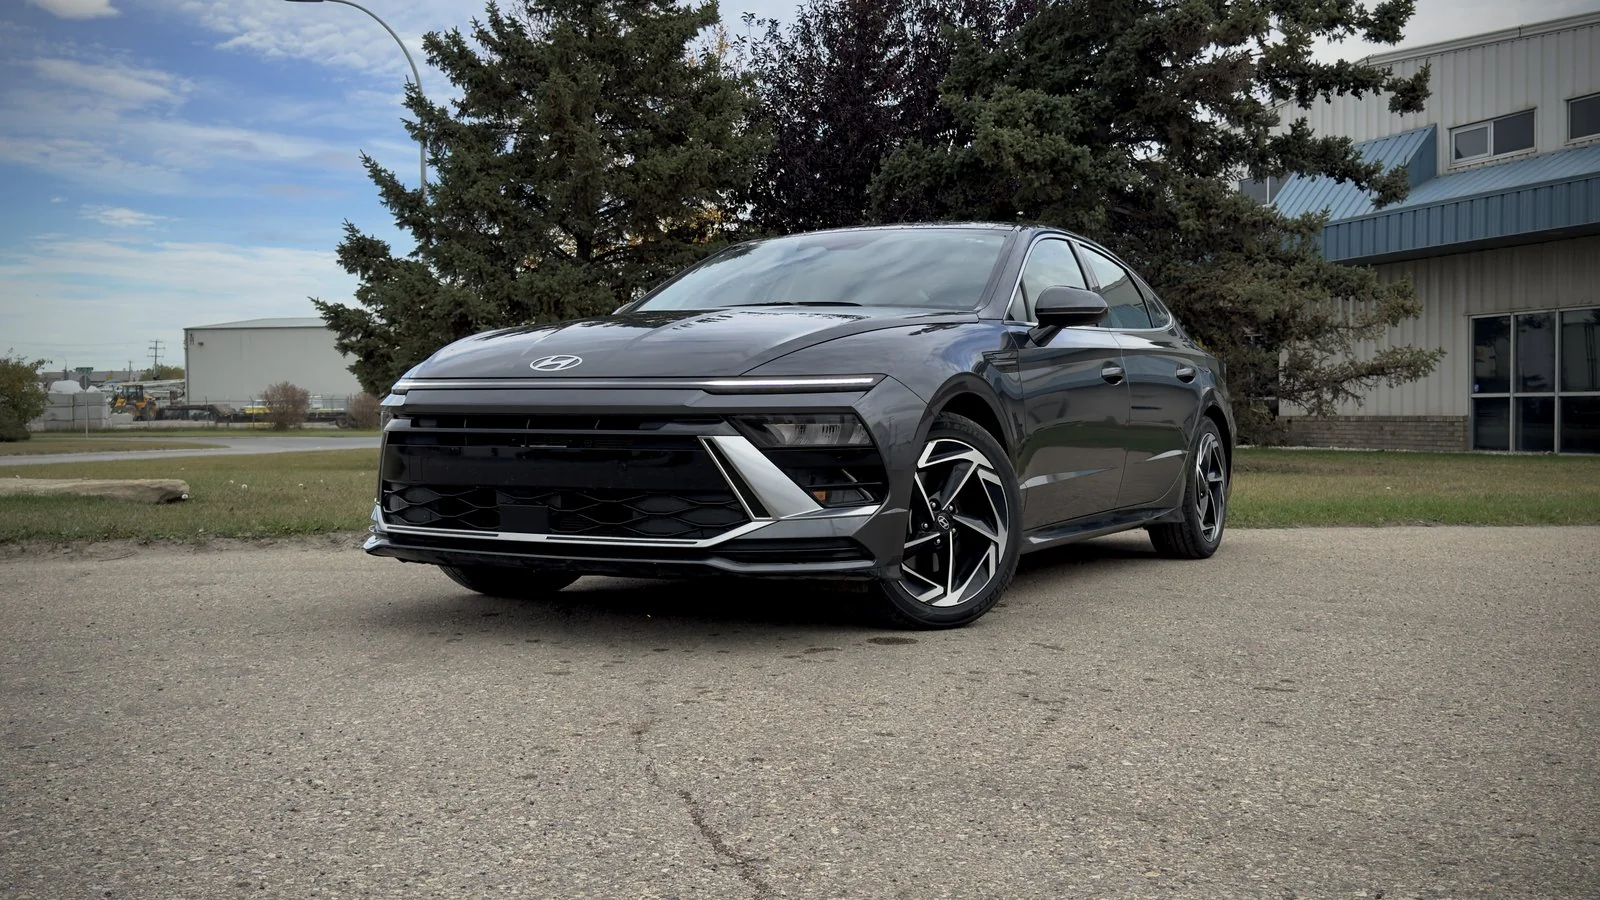
2025 Hyundai Sonata Preferred w/ Trend
$192 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $6,872
OAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Related Terms
Sources (pages opened October 6, 2026): Equifax Canada: 5 Things to Know About Your Credit Scores; Equifax Canada: How Can You Check Your Credit Scores?; Equifax Canada: How Is Credit Score Calculated?; Equifax Canada: Why You May Have Different Credit Scores; Financial Consumer Agency of Canada: Credit report and score basics. These are public pages, quoted as written. Scoring models change, so check the bureau's own page before you rely on a detail.
Last reviewed October 2026 by the Shift Happens finance team
Wondering what a lender will see?
Tell us about your file when you apply. We review every application and call you back.