
Construction PM Car Loans: T4 vs T4A Income
In this article
- How Do Lenders Qualify Construction Project Managers With Mixed T4 and T4A Income?
- The Three Income Structures Construction PMs Have
- Pattern 1: Employee on a T4
- Pattern 2: Your Own Corporation
- Pattern 3: Employee, Then Contractor, Then Employee Again
- What If I Am Between Projects?
- Frequently Asked Questions
- Can I use T4A contract income to qualify for a car loan in Alberta?
- What happens if my income jumped in the past year?
- Can I get a car loan if I have not filed this year's taxes yet?
- Does my personal credit score matter if my income is very high?
- What Should I Do Next?
Check Your Options in 3 Minutes
No credit impact. All credit situations welcome.
★★★★★ 118+ Google Reviews · AMVIC Licensed · Free Delivery 300km
A project manager's pay does not always come on one slip. You might have a T4 from one employer, a stretch of contract work between projects, and a corporation that bills your clients. A lender reads each of those papers differently, so it helps to know which paper shows what. This post sorts that out.
If you are an employee, the basics are on our page about what lenders verify about your pay and your job. If your credit took a hit, the paperwork is the part you can get ready ahead of time, and every lender decides each file.
See what you pre-qualify for
Three quick answers — soft check, no commitment.
How Do Lenders Qualify Construction Project Managers With Mixed T4 and T4A Income?
It depends on the lender. Lenders commonly ask employees for a pay stub, an employer letter or a T4, and contract or self-employed applicants for a Notice of Assessment and T1 General. How a lender combines the two is not published. We review every application and call you back.
The Three Income Structures Construction PMs Have
Pattern 1: Employee on a T4
If you are on payroll with a general contractor, a developer or a construction management firm, your pay shows on pay stubs and a T4. The CRA says employment income consists of salary, wages, commissions, bonuses, tips and similar amounts, and that it is usually shown in box 14 of your T4. A project bonus is part of that. None of the lender pages we read gives a formula for bonuses, so each lender decides how much of one counts. A T4 adds up the whole year, so it can show a pattern that one pay stub cannot.
Pattern 2: Your Own Corporation
If you bill clients through your own company, your personal return shows what the company paid you, not what the company earned. A salary is employment income, usually shown in box 14 of your T4. Dividends are profits you receive from your shares in a corporation, and they are usually reported on an information slip such as the T5.
Example with made-up numbers: your company pays you a $90,000 salary. Your T4 shows $90,000, or $7,500 a month. Whatever else the company bills is on the company's books, not on your personal return. The company's financial statements are a separate document, and one credit union asks incorporated owners for them for the last three years. How much of the money still inside the company a lender counts is the lender's call, and none of the pages we read says. How you pay yourself is a tax question for your accountant, and we do not give tax advice.
Pattern 3: Employee, Then Contractor, Then Employee Again
Some PMs work a long stretch on payroll, take a contract between projects, then go back on payroll. Contract work may come with a T4A. The CRA says payments over $500 in a calendar year for services must be reported, usually on a T4A slip, but its penalty moratorium stays in place for every industry except trucking, so some payers may not send one. The CRA says to report your gross and net self-employment income on lines 13499 to 14300 of your return, and it sends you a Notice of Assessment for every return you file.
For a mixed year, one bank asks for the last two years of T1 General with the matching Notices of Assessment for self-employed or variable income. So bring both years in full, along with your latest pay stubs or an employer letter. A short note that explains the pattern, who you work for now and when you contracted, gives the lender the story behind the papers.
What If I Am Between Projects?
A gap between projects shows up in your pay history and on your bank statements. Lenders set their own rules on time on the job. One Canadian auto lender publishes a minimum of three months on the job, with exceptions when you take a new job in the same or a similar field after at least a year at your last one. A PM who moves from one employer to the next may fit that exception, but every lender decides each file. Tell us your start date and bring the signed offer or contract. Our page on starting a new job in Alberta covers offer letters and probation.
Frequently Asked Questions
Can I use T4A contract income to qualify for a car loan in Alberta?
You can apply. Lenders commonly ask for your Notice of Assessment and T1 General, and a few add the T2125 or bank statements. How many years they want varies: on the pages we read, from a recent Notice up to three years. Each lender decides how much weight contract income carries. We review every application and call you back.
What happens if my income jumped in the past year?
A pay stub or an employer letter shows what you earn now. A tax return shows the years you have filed. If you have a promotion, a raise or a new role, bring your latest pay stubs or an employer letter next to your last Notices of Assessment. How a lender weighs a jump against earlier years is not published, so tell us what changed and we will say what to bring.
Can I get a car loan if I have not filed this year's taxes yet?
The CRA sends a Notice of Assessment for every return you file, so without a filed return there is no Notice to show. If you are behind, getting your returns filed with your accountant's help comes first. Tell us where you are.
Does my personal credit score matter if my income is very high?
Yes. Lenders weigh your credit, your income and your job history together, so a high income does not replace a score. Your score also places you in a rate band. A score of 520 falls in the 500–549 band at 14.9–24.9% APR, and a score of 720 falls in the 650–749 band at 6.9–12.9% APR.
Here is what that does to a payment. Take a $40,000 loan over 72 months. At the Near-Prime example rate of 9.9% it is about $739 a month. At the Subprime example rate of 16.9% it is about $888 a month. That is $149 more a month and about $10,699 more interest over the term. Example, not an offer: rates run 4.99%–29.9% APR. The Financial Consumer Agency of Canada says payment history is the most important part of your credit score and suggests using less than 30% of your total credit limit. For all seven score bands, see car loan interest rates in Alberta.
What Should I Do Next?
If you are an Alberta construction PM with T4, T4A or mixed income, the quickest start is the online application. Tell us how your pay arrives and what your returns show, and we will say what to bring. We work with 21+ lenders, every lender decides each file, and we review every application and call you back.
Sources (pages opened October 6, 2026): CIBC: Personal Car Loan; Affinity Credit Union: personal loans; TD: personal loan application checklist; TD: credit granting process; Scotiabank: Scotia Plan Loan documents; BMO: what to bring to a lending appointment; ATB: Navigating car loans in Alberta; Santander Consumer Bank (Canada): our loans; Canada Revenue Agency: line 10100, employment income; Canada Revenue Agency: T4 slip, information for employers; Canada Revenue Agency: lines 12000 and 12010, dividends; Canada Revenue Agency: reporting fees for service; Canada Revenue Agency: lines 13499 to 14300, self-employment income; Canada Revenue Agency: reading your notice of assessment; BDC: what is a corporation; Financial Consumer Agency of Canada: improve your credit score.
Financing Resources
Cars you could drive home
Browse all inventory →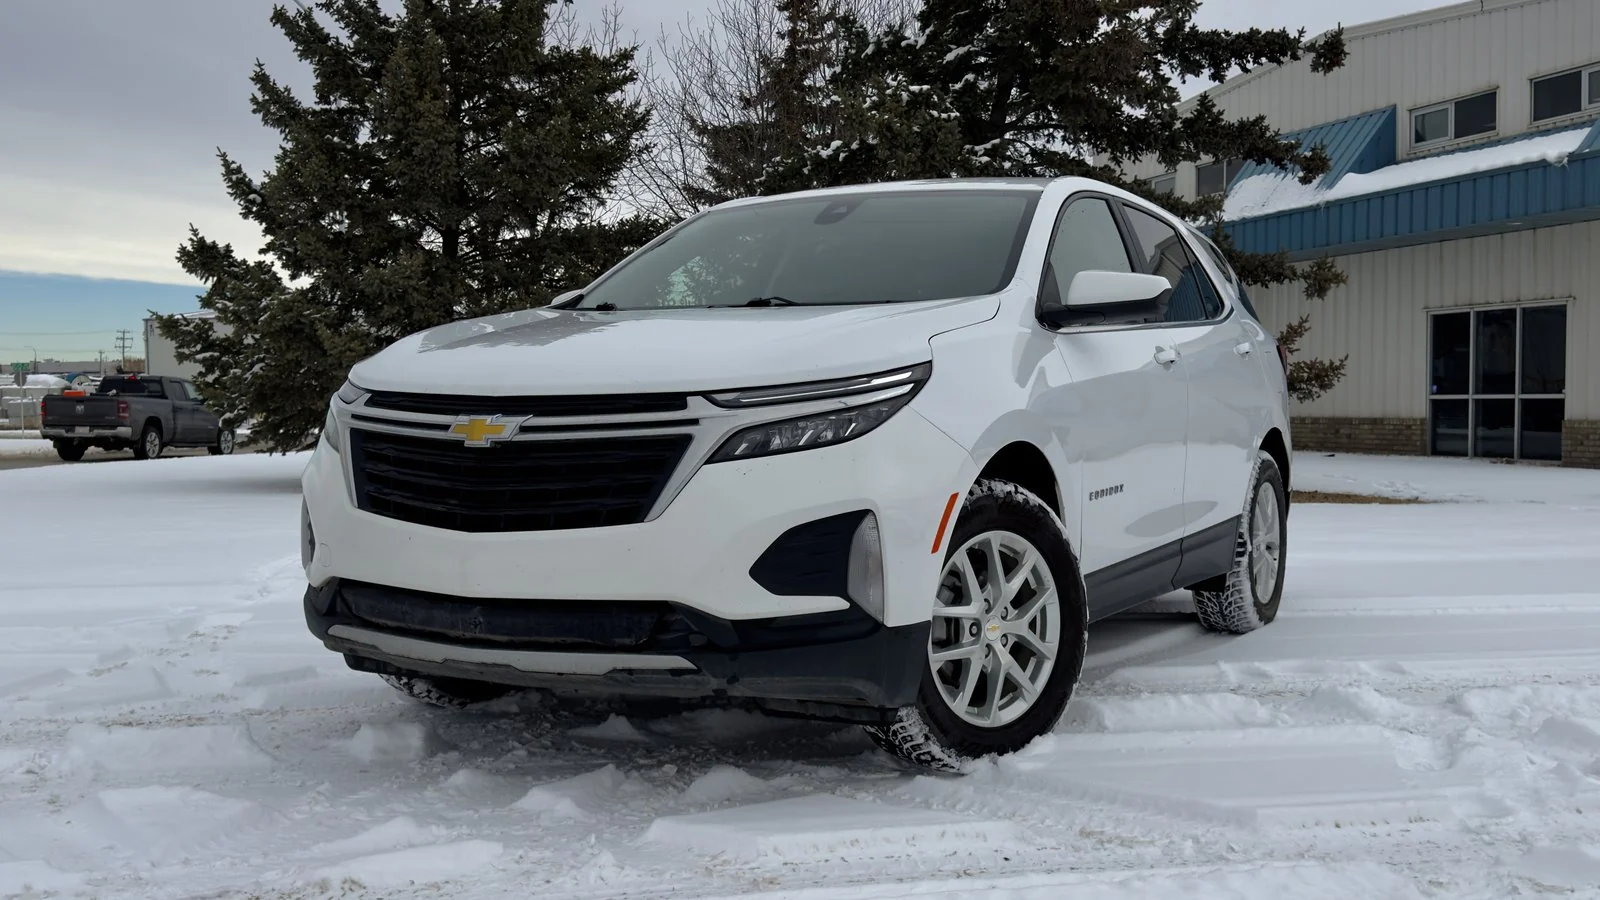
2022 Chevrolet Equinox LT
$157 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $5,644
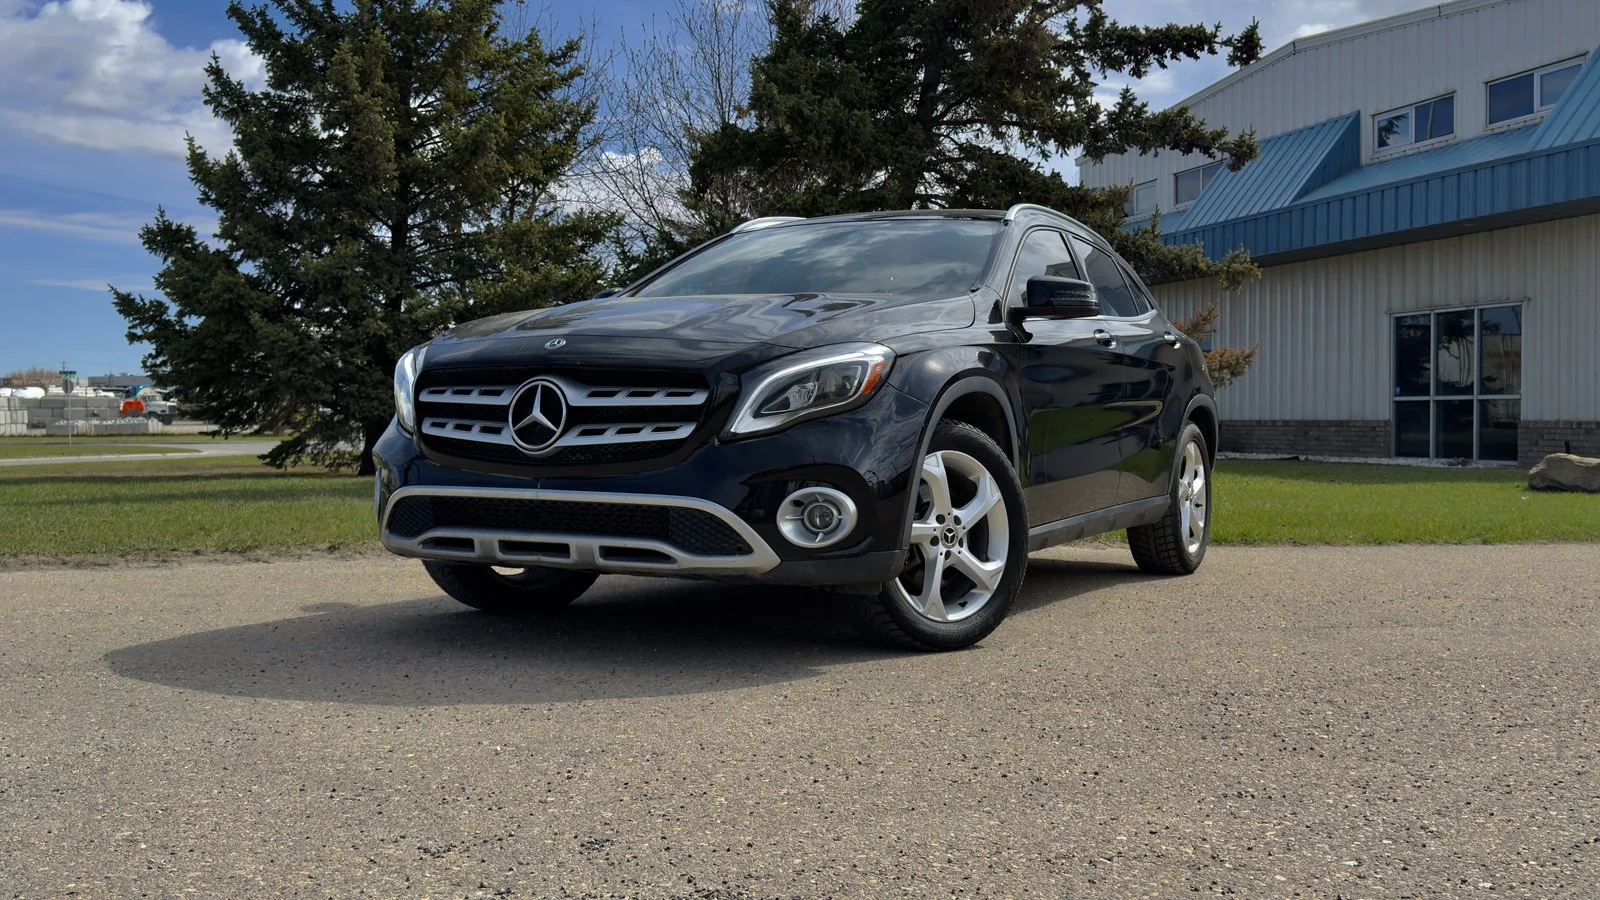
2020 Mercedes-Benz GLA250 4Matic
$150 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $5,398
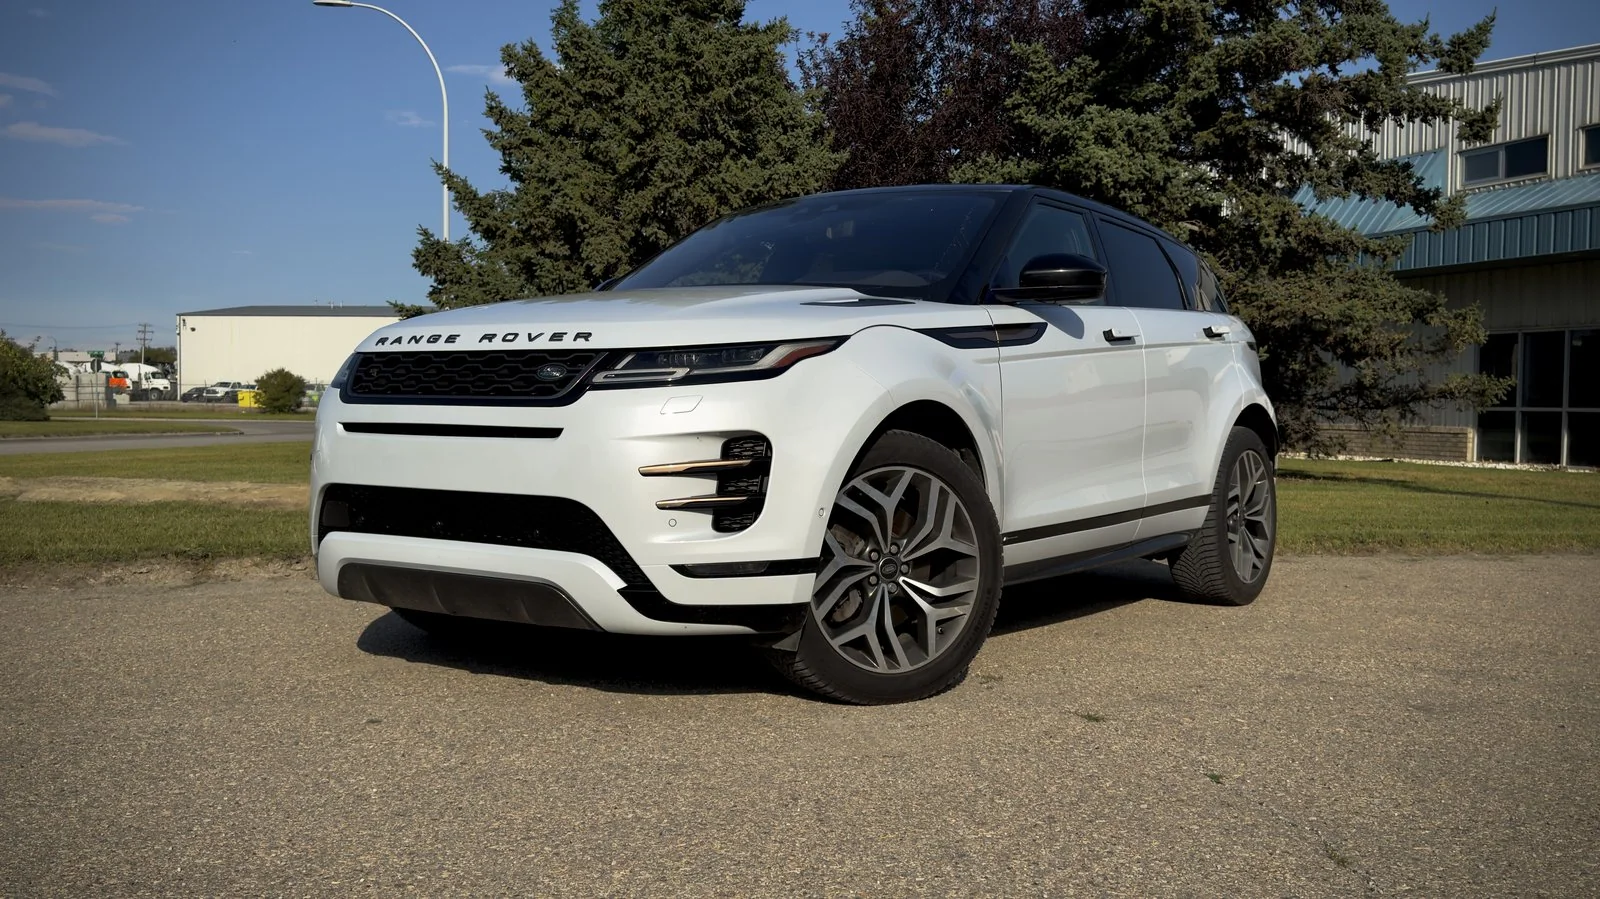
2020 Land Rover Range Rover Evoque P250 First Edition
$178 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $6,381
OAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Related Articles
Ready to Find Your Vehicle?
Browse our inventory or apply for financing. All credit situations welcome.
★★★★★ 118+ Google Reviews · AMVIC Licensed · Free Delivery 300km