How Long After a Repossession Can You Get a Car Loan?
In this article
- How Long After a Repossession Can You Get a Car Loan in Alberta?
- What Does a Repossession Show on Your Credit Report?
- How Long Does a Repossession Stay on Your Credit Report?
- Is There a 12-Month Rule After a Repossession?
- What Happens to the Balance After the Car Is Sold?
- How Much Does a Down Payment Help After a Repossession?
- What Income Do Lenders Want to See After a Repossession?
- What Kind of Vehicle Do Lenders Prefer After a Repossession?
- What Can You Do Now to Make Your File Stronger?
- Adjacent Situations
- Is This a Fit for Your Situation?
- Frequently Asked Questions
- Can I get a car loan the day after a repossession in Alberta?
- Does a voluntary repossession hurt my credit differently than an involuntary one?
- How much will my interest rate be after a repossession in Alberta?
- Will a co-signer help after a repossession?
- Does a repossession change how I apply?
- Compare and Apply
Check Your Options in 3 Minutes
No credit impact. All credit situations welcome.
5.0118+ Google ReviewsAMVIC LicensedFree Delivery 300km
A repossession is hard to live through, and the next question is a practical one: when can you get another vehicle? We know of no set date. Each lender decides, and it looks at your credit history, your income and your job history. Our guide to car loans after a repossession covers the wider picture. This post answers the "how long" question and shows where each fact comes from.
How Long After a Repossession Can You Get a Car Loan in Alberta?
It depends on the lender, and we know of no rule that sets a waiting period. Each lender writes its own credit rules and decides each file. A lender looks at the repossession and its dates, whether any balance is still owing, your income today and the payments you have made since. We cannot promise what any lender will decide.
What Does a Repossession Show on Your Credit Report?
Lenders send information about your accounts to the credit bureaus, and the bureaus build your report from it. Equifax's guide to its report lists the ratings an account can carry. Late payments are rated by how late they were. One rating is "8: Repossession (voluntary or involuntary return of merchandise)."
If the car sold for less than you owed and the lender sent the rest to a collection agency, a separate collection entry can appear as well. Equifax says past-due accounts that have been turned over to a collections agency could also be included in your credit report.
Nobody can give you an honest score number in advance. The Financial Consumer Agency of Canada (FCAC) says your score goes up when you pay bills on time and use credit responsibly, and goes down when you miss payments or have too much debt.
How Long Does a Repossession Stay on Your Credit Report?
FCAC says credit bureaus may only keep negative information for a certain period. Its example is "information about late or unpaid credit cards and loans: up to 6 years." Equifax says negative information such as late or missed payments, accounts sent to collection agencies or a bankruptcy "stays on credit reports for approximately six years." For a collection account, Equifax says the six years run "from the date of first delinquency on the account (typically when it went to collection)."
Neither page names repossession, so the dates on your own report are what count. Equifax's guide says an account can show "FRST/DELQ: Date of first payment delinquency by the consumer." Look for that date on your report.
Alberta adds its own limit. Under the Credit and Personal Reports Regulation, a reporting agency must not include unfavourable information about a debt "if more than 6 years has elapsed since the date of the last payment on that debt or the date the debt was incurred, whichever is later."
Is There a 12-Month Rule After a Repossession?
You may read that lenders want a set number of months. We know of no law or credit bureau rule that says so. Any waiting time is a lender's own policy, and policies differ. One major bank says its credit granting policies "vary by product and from one lender to the next."
In our experience, a lender looks at more than the date. It asks what has happened since: whether you have paid your other bills on time, whether any balance from the repossession is still owing, and whether your income is steady. These are patterns, not promises, and every lender decides each file.
What Happens to the Balance After the Car Is Sold?
If the car sells for less than you owed, you may still owe the difference, called a deficiency. Alberta's Personal Property Security Act says that, unless otherwise agreed or provided in an Act, "the debtor is liable for any deficiency." Our post on deficiency balances after a repossession in Alberta walks through the steps and your rights.
An unpaid balance can be sent to a collection agency, where it becomes its own entry. In our experience, lenders would rather see a balance dealt with than ignored: paid, settled in writing, or on a payment plan you keep up. If a collection agency settles with you and you pay the full settlement, Alberta's collection regulation says the agency must give you a receipt that states the amount is "in final settlement of the debt or debts owing." Keep it with your records.
How Much Does a Down Payment Help After a Repossession?
A bigger down payment means a smaller loan. One loan-comparison site says that by putting more money upfront, "you'll reduce the lender's risk as your car loan is less likely to end up upside down." It suggests at least 10% down on a used vehicle. A lender decides how much it wants.
Example, not an offer: a $15,000 loan at 24.9% APR over 60 months is about $202 bi-weekly (about $439 a month). Put $3,000 down, borrow $12,000, and the same loan is about $162 bi-weekly (about $352 a month). 24.9% is the example rate for our Deep Subprime tier (19.9%–29.9%).
What Income Do Lenders Want to See After a Repossession?
Lenders confirm income before they lend. One major bank says: "A T4 slip or a pay stub is generally required as minimum proof of income." It asks for more if you are self-employed or on a contract. In our experience, lenders typically look for about $2,800 a month in income you can prove, from all sources combined. If you are under that, talk to us first.
Lenders also compare what you already pay out each month with your income. One loan-comparison site says a debt-to-income ratio no higher than 44% is generally recommended. Every lender sets its own limit.
A rule of thumb we use is a car payment of about 15% of your gross monthly pay. It is a guide, not a lender rule. At that rule of thumb, the $15,000 example above (about $439 a month) fits gross pay of about $3,000 a month.
What Kind of Vehicle Do Lenders Prefer After a Repossession?
Most car loans are secured, which means the vehicle is the collateral. One Alberta bank says: "If you fail to make payments, the lender can repossess the car." So a lender looks at the vehicle as well as at you.
In our experience, lenders are more comfortable with a newer vehicle, lower kilometres and a mainstream make at a fair price, because it is easier to resell if a loan goes wrong. If your down payment is small, a lower-priced vehicle keeps the loan small too. Our affordability calculator shows how price and down payment change the payment.
What Can You Do Now to Make Your File Stronger?
Time helps, but what you do with it helps more. Here is what you can do now, in order.
- Find out what you owe. Ask the lender or the collection agency for the amount in writing. Alberta's Consumer Protection Act says a collection agency must give a debtor a statement of account on written request. Keep every letter and receipt.
- Get both credit reports. FCAC says you can access your credit report online for free from Canada's 2 main credit bureaus, Equifax and TransUnion. Check the repossession date and any balance listed.
- Pay every bill on time. FCAC says payment history is "the most important part of your credit score."
- Consider a secured credit card. FCAC says one may be an option "if you have bad credit." You give the card issuer a security deposit, and you may pay a set-up fee or an annual fee, so read the terms first.
- Gather proof of income. One Alberta bank lists pay stubs, an employment verification letter, tax returns and bank statements.
Adjacent Situations
If this post was useful, these directly-related guides will help you go deeper:
Is This a Fit for Your Situation?
We sell used vehicles in Alberta and work with buyers whose credit took a hit. If you have steady income and a repossession in your past, we can look at your file. We review every application and call you back. Every lender decides each file, so we cannot promise a result. You can start on our financing application page.
Frequently Asked Questions
Can I get a car loan the day after a repossession in Alberta?
That depends on the lender. We know of no rule that stops you from applying. In our experience, some lenders will look at a recent repossession and others want more time and more payment history. A payment you cannot keep up could put you back where you started, so look at the payment before you look at the speed.
Does a voluntary repossession hurt my credit differently than an involuntary one?
Equifax's guide uses one rating for both: "8: Repossession (voluntary or involuntary return of merchandise)." What a lender then looks at is the date, any balance still owing and what your file shows since. Our post on voluntary repossession in Alberta works through the numbers.
How much will my interest rate be after a repossession in Alberta?
Your rate follows your credit score band and the rest of your file, not the word "repossession." Rates in our lender programs run 4.99%–29.9% APR across all tiers. In the lower score bands the typical ranges are 19.9%–29.9% for 450–499, 14.9%–24.9% for 500–549 and 9.9%–19.9% for 550–599. Every lender decides each file, so these are typical ranges and your own rate can differ. See car loan rates by credit score for every band.
Will a co-signer help after a repossession?
It can. One Alberta bank says that adding a co-signer with good credit "can improve your chances of approval and potentially lower your interest rate." The co-signer takes on real risk: another major bank describes a co-signer as someone "who will agree to be liable for the debt if you fail to make the payments." Each lender decides each file.
Does a repossession change how I apply?
The application asks for the same basics. One Alberta bank lists a bill of sale, proof of income and employment, a valid driver's license and insurance. In our experience, a lender may also ask about the repossession and whether any balance is owing, so bring any letters or receipts you have.
Compare and Apply
- Complete Bad Credit Car Buying Guide (Alberta) — complete bad credit car buying guide
Sources (pages opened October 6, 2026): Financial Consumer Agency of Canada: Credit report and score basics, How long information stays on your credit report, Getting your credit report and credit score, Improving your credit score, Choosing a credit card; Equifax Canada: Consumer Credit Report User Guide (PDF), What information is in a credit report?, How long does information stay on your credit report?; Alberta King's Printer: Credit and Personal Reports Regulation, Alta Reg 193/1999 (current as of July 16, 2025), Personal Property Security Act (current as of June 1, 2024), Collection and Debt Repayment Practices Regulation, Alta Reg 194/1999 (current as of July 1, 2026), Consumer Protection Act (current as of July 14, 2026); Bank, credit union and loan-site pages: ATB: navigating car loans in Alberta, TD: credit granting process, Loans Canada: how to qualify for a car loan. These are public pages, quoted to show what they say. Check the source page before you rely on a detail. This is general information, not legal advice.
Financing Resources
Cars you could drive home
See all inventory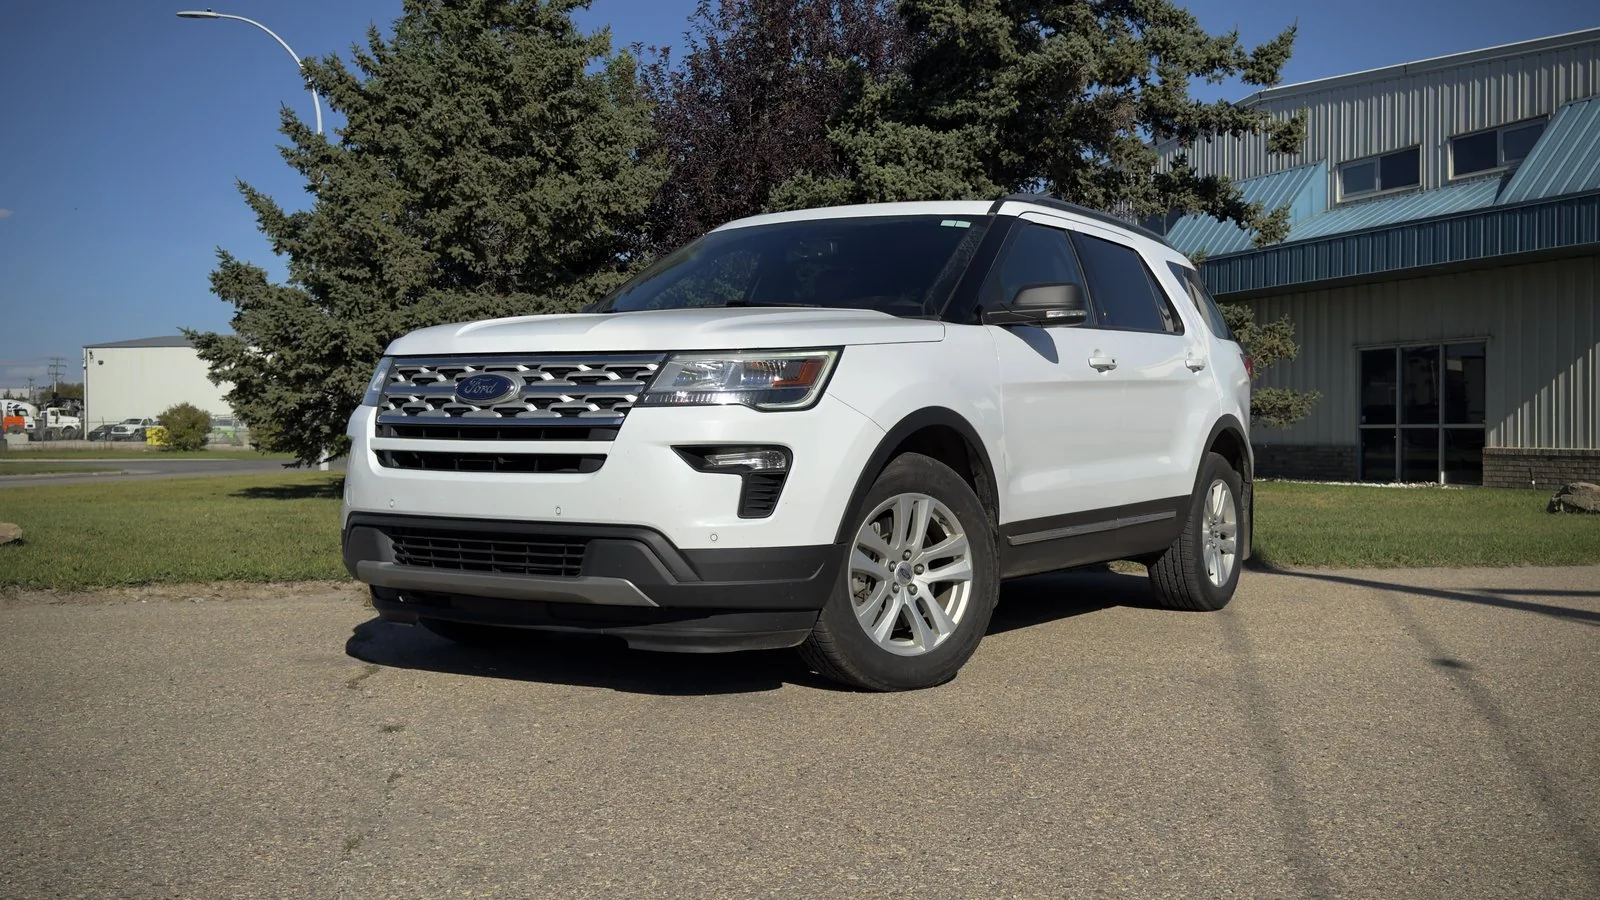
2019 Ford Explorer XLT
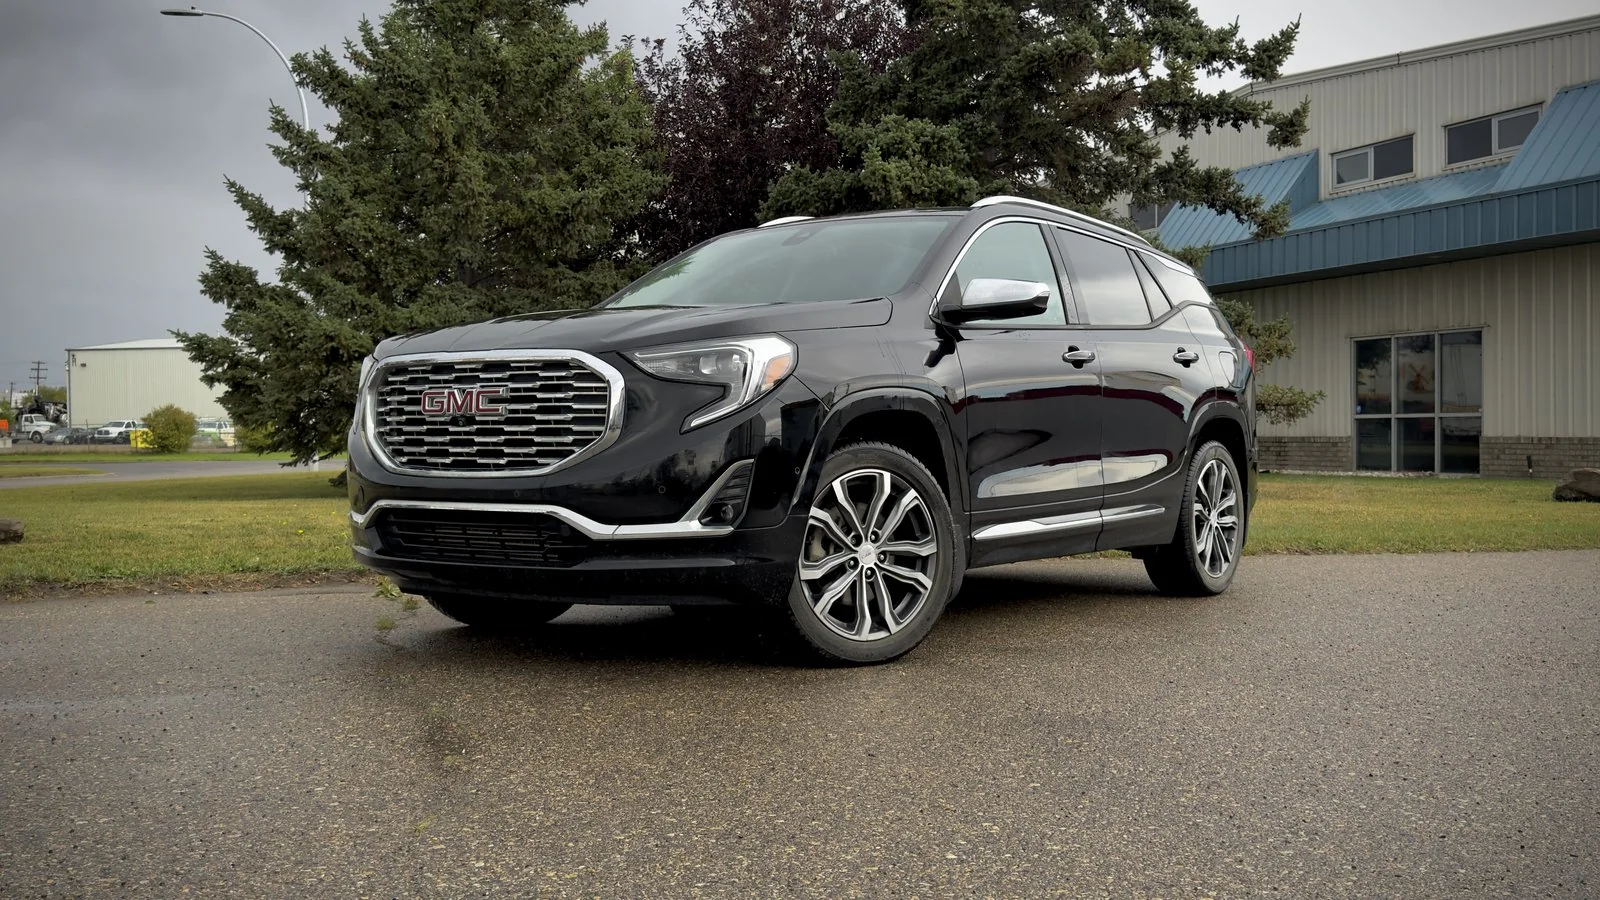
2020 GMC Terrain Denali
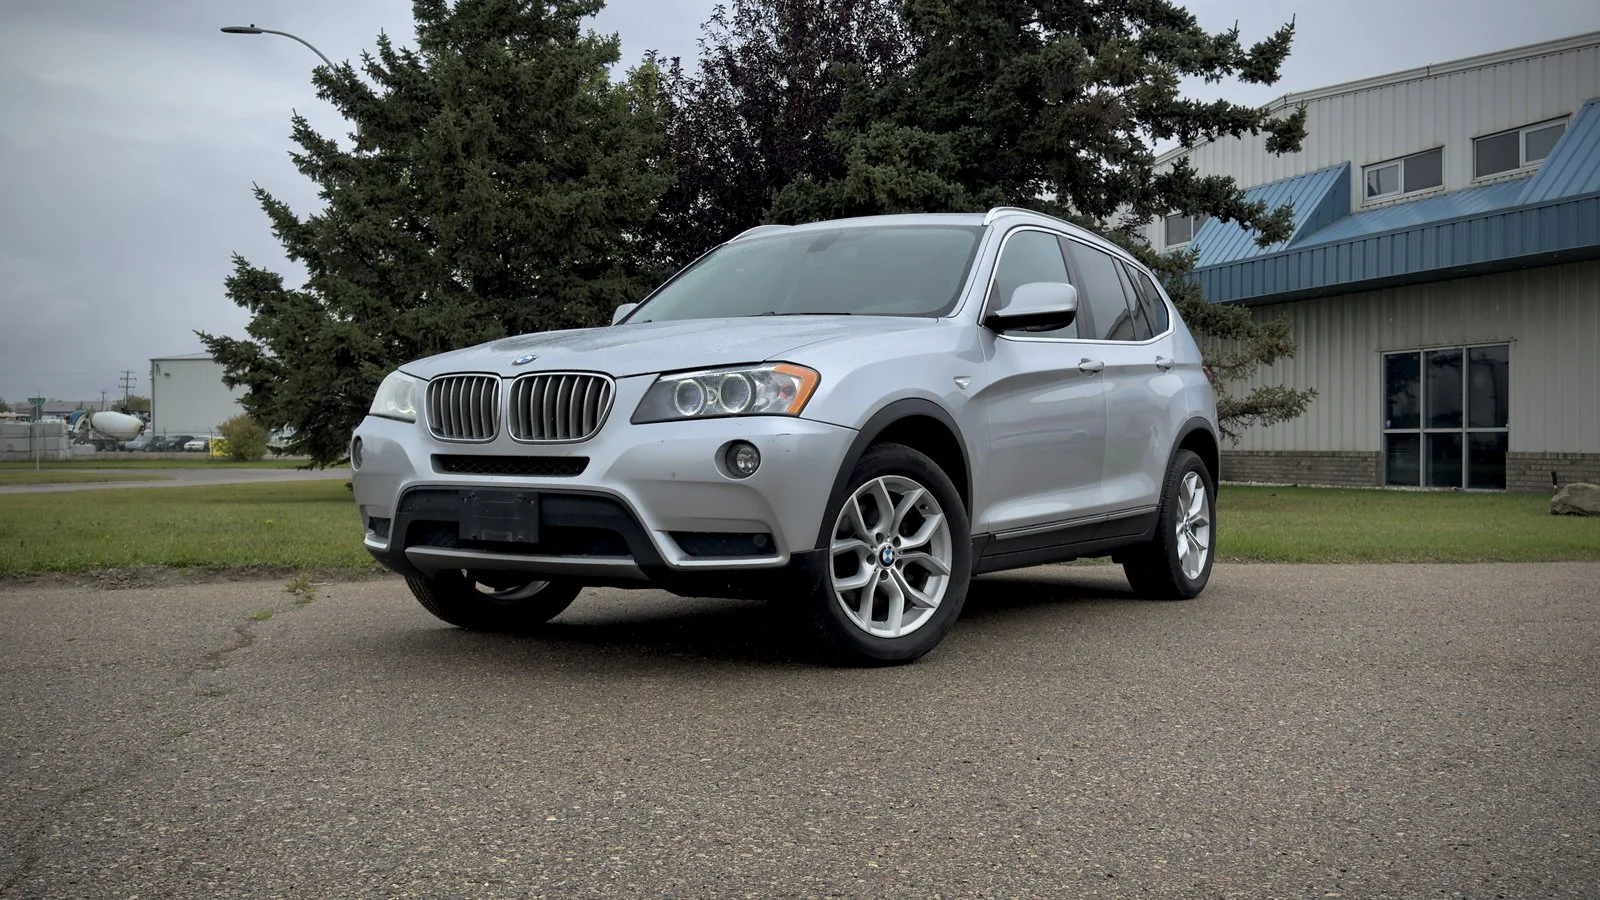
2014 BMW X3 xDrive28i
Not seeing it? We'll find it.
We source through our dealer partner network across Western Canada: 25,000+ vehicles to choose from. Tell us what you want and what works for your budget.
Find my car3 min · no credit impactOAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
Related Articles
Ready to Find Your Vehicle?
Browse our inventory or apply for financing. All credit situations welcome.
5.0118+ Google ReviewsAMVIC LicensedFree Delivery 300km