
A Car Loan Now and a Mortgage Later: How the Car Payment Counts
Does a car loan count against me when I apply for a mortgage?
A car payment counts as a debt when a mortgage lender checks your ratios. For mortgages it insures, CMHC limits your housing costs plus all other debts to 44% of gross household income, and car loans are in that group. A smaller payment leaves more room. Your mortgage broker can work out your numbers. We do not give mortgage advice.
This page is part of our guide to car loan rates in Alberta. It is general information, not mortgage advice.
Who this page is for
- You work, your pay is steady, and your credit took a hit.
- You need a car now and may apply for a mortgage later.
- You want to know how a car payment counts, not get mortgage advice.
General information, not mortgage advice
Key Facts
- Who this is for
- Working, with a mortgage on the horizon
- Counts in your total debt ratio
- Your car payment, with housing costs and other debts
- CMHC limits for the mortgages it insures
- 39% for housing costs (GDS), 44% for all debts (TDS)
- What the housing ratio leaves out
- Car loans and other debts
- Lender network
- 21+ lenders
See what you pre-qualify for
A few quick answers. No commitment.
Does a car loan count when a lender looks at my mortgage application?
Yes, the payment counts. FCAC says: “Mortgage lenders and mortgage brokers use your financial information to calculate your monthly housing costs. They also calculate your total debt load.” CMHC says what goes into that debt load: “Other debt obligations include revolving credit (i.e. credit card debts, lines of credit), personal loans or car loans, etc.”
It is the monthly payment that counts. CMHC’s wording is “payments on all other debt”. Other lenders do a similar sum. One bank’s page says: “Your DSR indicates the percentage of your current monthly income that goes toward paying off debt.”
A mortgage lender looks at your credit too. FCAC says: “A potential lender will look at your credit report before approving you for a mortgage.” If you do not have a good credit score, it says the mortgage lender may “refuse to approve your mortgage” or “require that someone co-sign with you on the mortgage”.
What are GDS and TDS, and which one holds the car payment?
Two ratios, and the car payment sits in the second. CMHC says: “CMHC restricts debt service ratios to 39% (GDS) and 44% (TDS).” FCAC describes them this way:
- “Your total monthly housing costs shouldn't be more than 39% of your gross household income. This is the gross debt service (GDS) ratio.”
- “Your total debt load shouldn't be more than 44% of your gross income. This includes your total monthly housing costs plus all of your other debts. This is the total debt service (TDS) ratio.”
| Ratio | What is in it | CMHC limit | Car payment? |
|---|---|---|---|
| GDS (housing costs) | Mortgage payments, property taxes, heat and part of any condo fees | 39% | No |
| TDS (all debts) | The same housing costs, plus your car payment and every other debt payment | 44% | Yes |
These are limits for the mortgages CMHC insures. Other lenders have their own rules. FCAC says: “Each lender sets their own lending guidelines and policies.” It also says: “You may still qualify for a mortgage even if your TDS ratio is slightly higher. However, you’re increasing the risk of taking on more debt than you can afford.” Which limits apply to you is a question for your mortgage broker.
How much room does a car payment use up?
Here is the arithmetic, using CMHC’s total-debt limit. It shows how a debt payment shrinks the room. It is an illustration, not a mortgage estimate.
Say a household earns $7,000 a month before tax. 44% of that is $3,080 a month for housing costs and every debt together. Take off the car payment, and what is left has to cover the housing costs and all your other debts.
| Example | Car payment | Share of gross pay | Left under the 44% line |
|---|---|---|---|
| No car payment | $0 a month | 0% | $3,080 a month |
| Used SUV, $18,000 | $399 a month | 6% | $2,681 a month |
| Used SUV, $28,000 | $621 a month | 9% | $2,459 a month |
Example, not an offer and not a mortgage estimate. Both cars use a 72-month loan at the Subprime example rate of 16.9% APR; rates run from 4.99% APR (prime) to 29.9% APR (deep subprime). The pay and the prices are examples.
The $28,000 car uses $222 a month more of that room than the $18,000 car. That is money that cannot go to housing costs or other debts. For scale, our rule of thumb for a car payment is about 15% of gross pay, and a payment well under it leaves more room.
Other debts count too. CMHC lists credit card debts, lines of credit and personal loans next to car loans, and FCAC adds student loans and child or spousal support. To try your own car numbers, use the payment calculator. To see what your pay can carry, read the loan size your pay can carry at each score band.
Does paying my car loan on time help later?
It is part of the record a mortgage lender reads. FCAC says your credit report shows “if you make your payments on time or miss payments”, and that your score “goes up when you pay bills on time and use credit responsibly”. CMHC says: “A good credit report and credit score are important factors in determining whether or not you will be approved for a mortgage.” Its advice to borrowers includes: “Pay your bills in full and on time.”
We cannot say how much one loan changes a mortgage decision. That depends on the lender and on your whole file. For how a car loan can build a payment history, read how car payments build credit.
What if I have a debt management plan, a consumer proposal or a bankruptcy on my report?
Each one leaves the report on its own schedule. FCAC says:
- On a debt management plan: “Credit bureaus remove this information from your credit report 2 years after you finish paying off your debts.”
- On a consumer proposal: “Equifax and TransUnion remove a consumer proposal from your credit report: 3 years after you’ve paid off all the debts included in the proposal, or 6 years after you sign the proposal (whichever comes first)”.
- On a bankruptcy: “Usually, both Equifax and TransUnion remove a bankruptcy from your credit report 6 years after you're discharged.”
When a mortgage lender will say yes to a file with one of these is a question for a mortgage broker, and we cannot answer it. For what a code on your report means, see R7, R9 and I9 on your credit report. For how car lenders read a proposal or a bankruptcy, see car loans during or after a consumer proposal and bankruptcy car financing.
What should I ask my mortgage broker?
A mortgage broker can work from your actual file. These questions turn this page into your own numbers.
- Which debt-service limits will you use for me? Are they the 39% and 44% that CMHC lists, or different ones?
- How will you count my car payment: the payment in my contract, or something else?
- If I choose a smaller payment or a bigger down payment on the car, how much more room does that give me?
- What does my credit report look like to you today, and what would you want to see change?
- Does it matter for my application whether I buy the car before or after I apply?
When you are ready for the car side, the quickest start is the online application. We review every application and call you back. Or call us at (825) 736-4438. A bigger down payment lowers the payment; see how down payments work.
Example payments are estimates. Not an offer.
Vehicles in stock right now
Browse all inventory →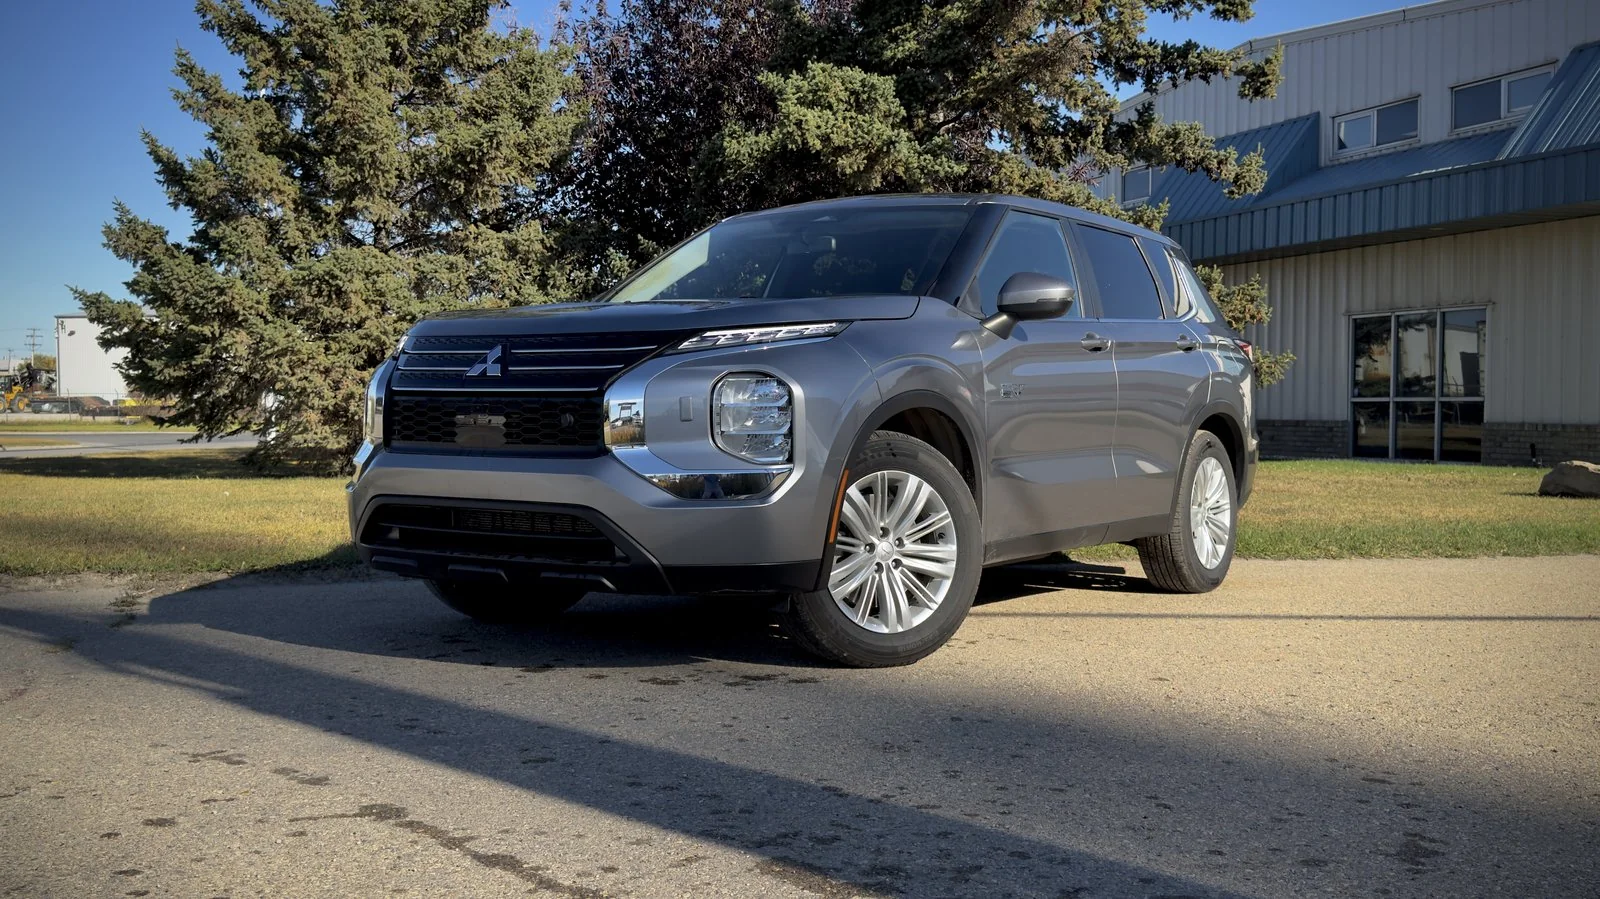
2023 Mitsubishi Outlander ES PHEV
$192 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $6,872
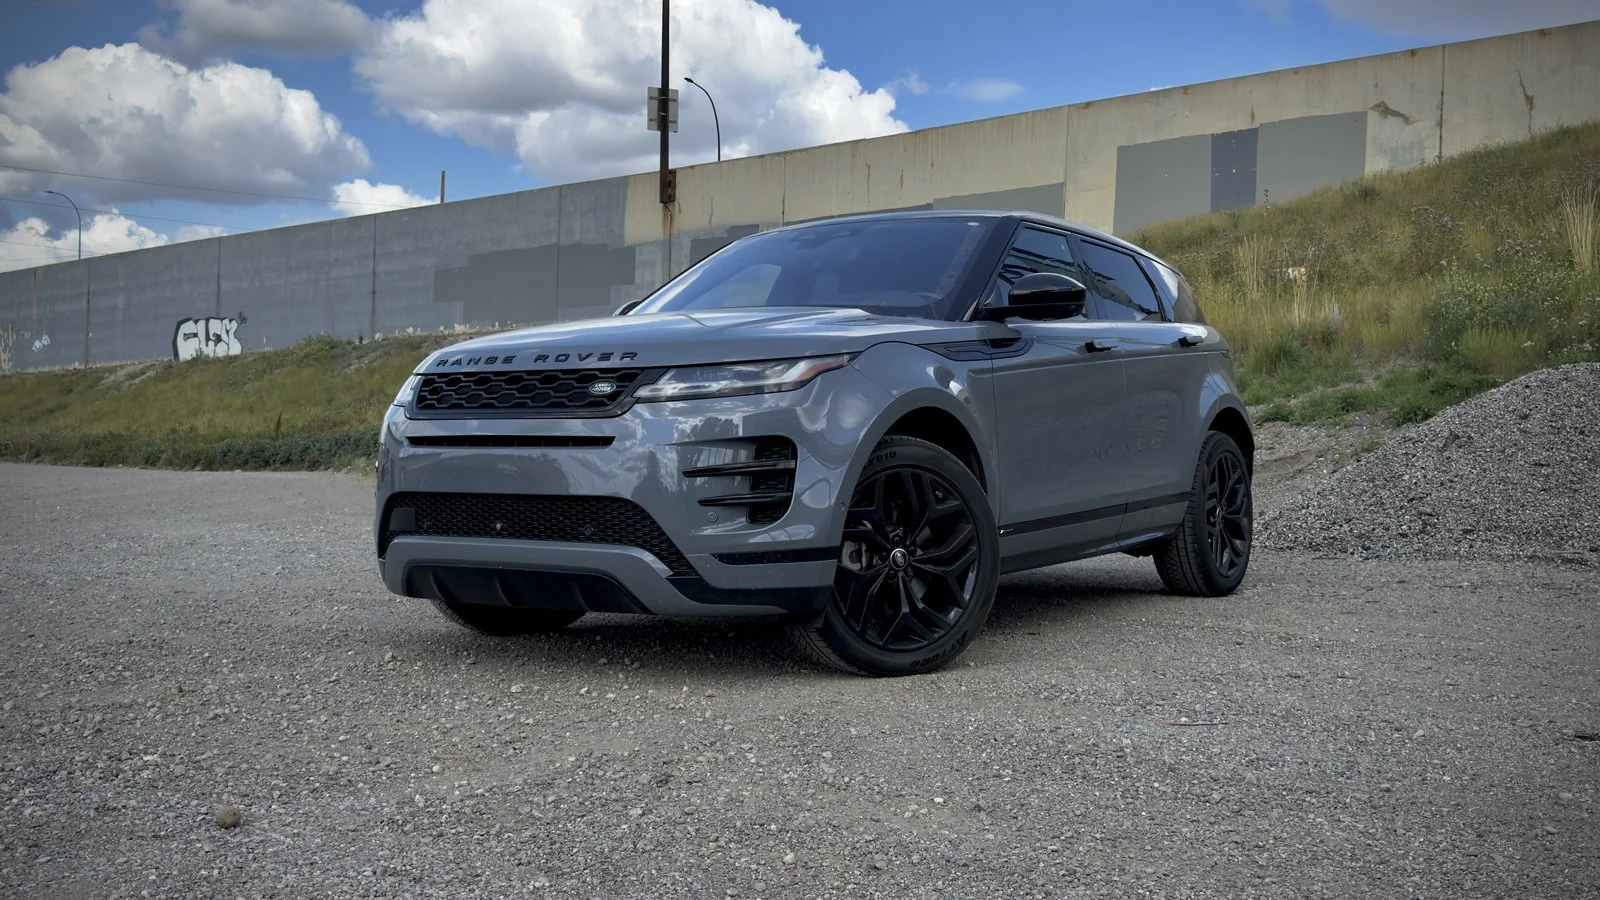
2021 Land Rover Range Rover Evoque R-Dynamic HSE
$212 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $7,609
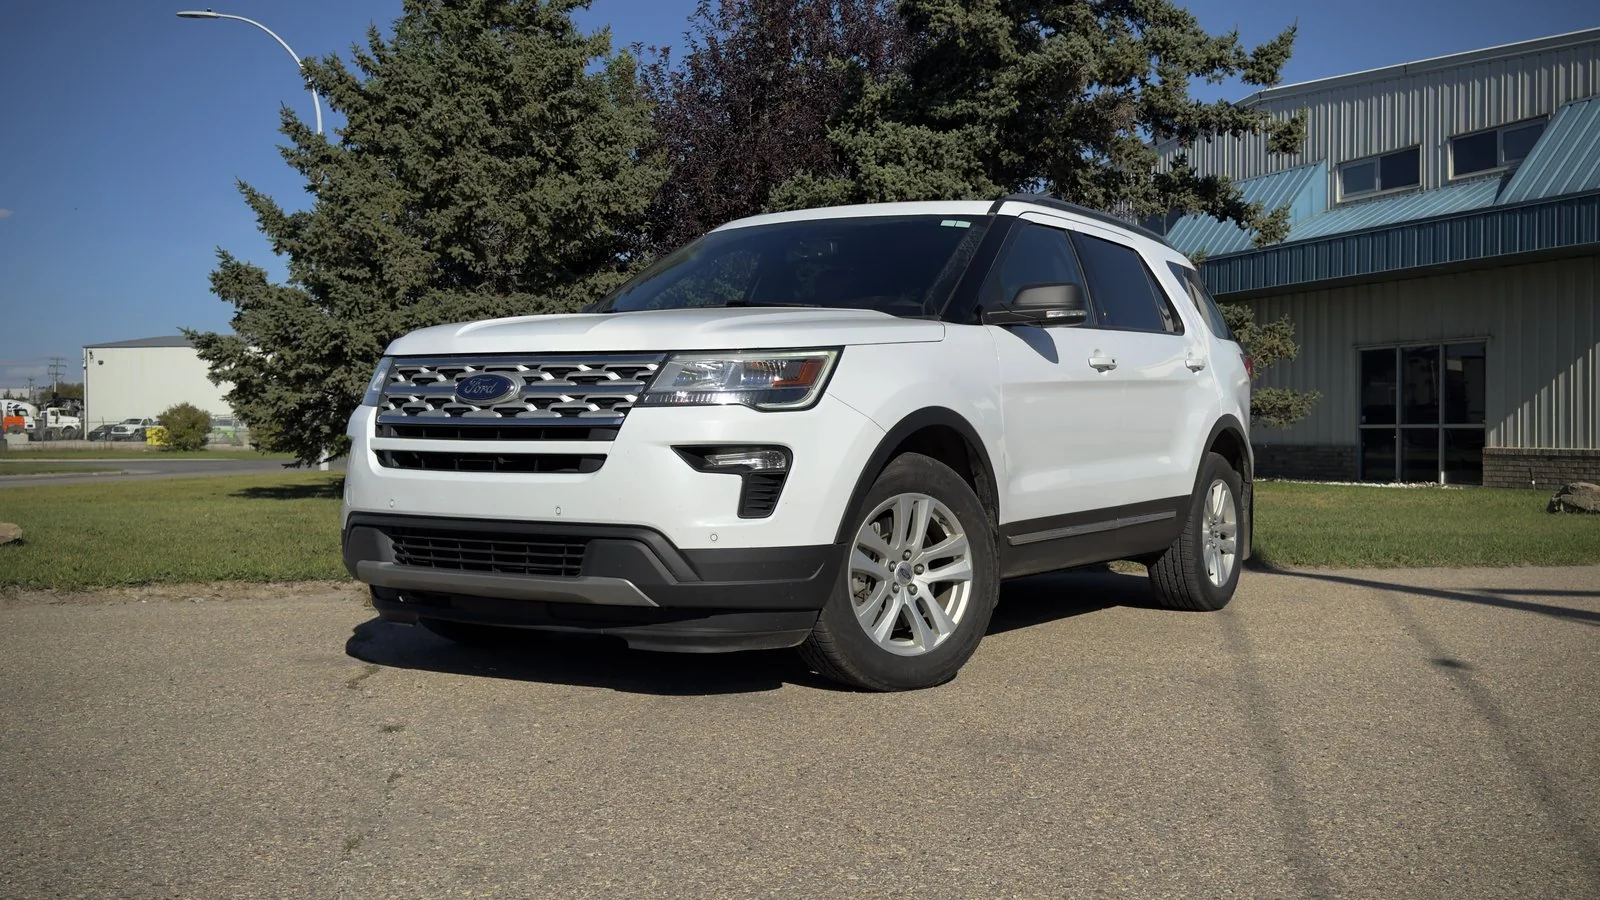
2019 Ford Explorer XLT
$123 bi-weekly OAC
6.49% APR · 84 months · $0 down · cost of borrowing $4,416
OAC = on approved credit. Payments are examples at 6.49% APR over 84 months with $0 down, based on each vehicle's advertised price; GST extra. Your rate depends on your credit (4.99%–29.9% APR).
A car loan before a mortgage: common questions
Will a car loan affect my mortgage approval?
The monthly payment counts as a debt. CMHC says: “Other debt obligations include revolving credit (i.e. credit card debts, lines of credit), personal loans or car loans, etc.” A mortgage lender also looks at your credit report. How a car loan changes your own approval is a question for your mortgage broker. We do not give mortgage advice.
What debt ratios do mortgage lenders use?
For the mortgages it insures, CMHC limits housing costs to 39% of gross household income (GDS) and total debts to 44% (TDS). The Financial Consumer Agency of Canada says: “Each lender sets their own lending guidelines and policies.” Ask your mortgage broker which limits apply to you.
Does a car payment count in GDS or TDS?
In TDS. GDS covers housing costs only. CMHC’s total debt service ratio adds “payments on all other debt”, and CMHC names car loans among those debts.
Should I pay off my car loan before I apply for a mortgage?
We cannot answer that. It depends on your numbers and on the lender. What we can say is that lenders count the monthly payment on a car loan in your debt ratio, so a smaller payment leaves more room. Ask your mortgage broker with your own figures.
How long after a consumer proposal can I get a mortgage?
We cannot say, and every lender decides each file. The Financial Consumer Agency of Canada says: “Equifax and TransUnion remove a consumer proposal from your credit report: 3 years after you’ve paid off all the debts included in the proposal, or 6 years after you sign the proposal (whichever comes first)”. When a mortgage lender will say yes to your file is a question for a mortgage broker.
Can I get a car loan now if I want a mortgage later?
You can apply. A lender decides on your file today, and we cannot promise a result. We review every application and call you back. CMHC says: “A good credit report and credit score are important factors in determining whether or not you will be approved for a mortgage.” Payments made on time help that picture; your mortgage broker can tell you how much.
Sources (pages opened October 6, 2026): Canada Mortgage and Housing Corporation (CMHC): Calculating GDS / TDS; CMHC: What are the general requirements to qualify for homeowner mortgage loan insurance?; CMHC: Credit Scores: What They Mean and How To Manage Them; Financial Consumer Agency of Canada: Preparing to get a mortgage; Financial Consumer Agency of Canada: Getting preapproved for a mortgage; Financial Consumer Agency of Canada: Credit report and score basics; Financial Consumer Agency of Canada: How long information stays on your credit report; TD Canada Trust: Credit granting. These are public pages, quoted as written. Limits and rules change and every lender sets its own, so check the source page and ask your mortgage broker before you rely on a detail.
Last reviewed October 2026 by the Shift Happens finance team
What Our Customers Say
“Had an amazing experience at this dealership from start to finish. Huge thanks to Luke for being professional, knowledgeable, and genuinely making the whole process stress-free.”
“I honestly can't thank Luke enough. From start to finish he was patient, respectful, transparent, and genuinely cared about helping me find the right vehicle instead of just making a sale.”
“The buying experience was handled very professionally. Wes was very attentive and presented everything in an open and honest manner that gave me the reassurance that I made a good purchase.”
Other Financing Options
See what you pre-qualify for
Apply online. We review every application and call you back.
★★★★★ 118+ Google Reviews · AMVIC Licensed · Free Delivery 300km